

Q&A
- +1
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China",
    "Carnegie Russia Eurasia Center"
  ],
  "collections": [
    "U.S.-China Relations"
  ],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia",
    "American Statecraft"
  ],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy",
    "Foreign Policy",
    "Trade"
  ]
}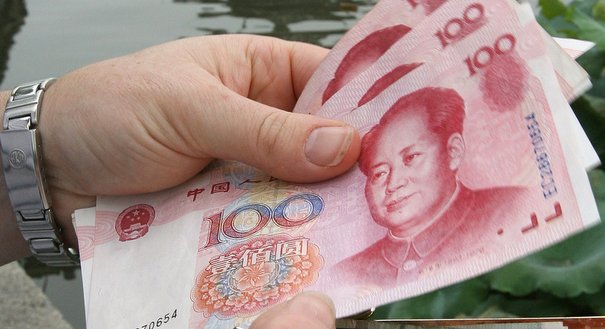
Source: Getty
Bilateral trade balances alone aren’t an accurate reflection of a country’s economic strength.
Source: Wall Street Journal
The recent failure of G-20 financial leaders to reaffirm their support for free trade illustrates the chasm between the views of the U.S. and the other major economies. The White House sees the U.S. trade deficit as impeding economic growth and prefers taking a bilateral approach to trade imbalances. This includes protectionist options such as dropping the Trans-Pacific Partnership, renegotiating the North American Free Trade Agreement and de-emphasizing the World Trade Organization. This line of reasoning is misguided.
America’s overall trade balance has little to do with the bilateral deficits of any specific country, even China. Bilateral trade balances don’t matter. What matters is a country’s overall trade balance.
Consider a simple three-country world. Country A sells something to country B, country B sells something of similar value to country C and country C sells something of similar value to country A. Each country has a bilateral surplus or deficit with the other two, but overall each country’s trade is balanced.
Moreover, a country’s trade balance doesn’t depend on whether its trade regime is relatively open or protected. Brazil and India have highly protected trade systems but incur persistent deficits. Germany and Singapore have relatively open economies yet generate large trade surpluses.
The link between trade deficits and growth is also tenuous at best. Rapidly growing economies often experience trade deficits because surging consumption requires more imports, while a stagnant economy has less need for imports.
Donald Trump’s trade advisors get it wrong when they inappropriately use the basic GDP accounting identity, which indicates that gross domestic product is the sum of consumption, investment and exports minus imports. They argue that if exports are increased, or imports decreased, GDP will increase. This tells us nothing about the secondary consequences of changes.
Simply levying higher tariffs to reduce imports would also cause firms to curb their purchases, leaving overall GDP unchanged. Alternatively, a country-specific tax would cause firms to buy from another country, altering the source of the imports but not its value.
Persistent trade deficits reflect a range of structural and macroeconomic policies. For one, trade-deficit countries aren’t saving enough relative to investment needs, while trade-surplus countries are saving too much.
America’s low savings rate is the consequence of its large budget deficits and households spending beyond their means. But a country’s savings rate isn’t independent of the savings rates of its trading partners.
China’s high savings rate over the past decade led to huge capital flows to the U.S. This helped drive down interest rates, making it easier for the U.S. government and households to borrow. The resulting decline in net savings then shows up in America’s persistent trade deficits, as net savings are equal to net exports.
The pattern is exacerbated because the U.S. is the preferred global safe-haven for capital flows. This boosts the value of the dollar, making it virtually impossible for the U.S. to avoid running a trade deficit.
From this perspective, America’s trade deficit has little to do with alleged unfair trade practices and more with the unique role of the dollar. This gives the U.S. the “exorbitant privilege” of running deficits with impunity.
Compare, for example, the trade balance of the U.S. with that of the European Union and China. Both the U.S. and EU in 2015 had significant bilateral trade deficits with China, contributing to China’s overall trade surplus of $600 billion. What is striking is that the EU has an overall surplus of $93 billion, while the U.S. has an overall deficit of $811 billion.
Back in 2010, however, the EU had an overall trade deficit. Its shift to a surplus has been facilitated by a sharp fall in the euro—which improved its trade balance—and to member countries such as Greece, Italy, Spain and the U.K. which tightened their budgets after the financial crisis.
These shifts illustrate the complex interactions of differing policies across countries. Bilateral trade balances alone aren’t an accurate reflection of evolving economic strengths.
The irony is that a U.S. trade deficit will likely continue to increase, as the U.S. is further along in its economic recovery compared with the EU, and the dollar remains overvalued. In contrast, China’s trade surplus is likely to increase as its prolonged growth slowdown depresses imports while its exports rebound with stronger U.S. growth.
This piece was originally published in the Wall Street Journal.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Yukon Huang, Isaac B. Kardon, Matt Sheehan
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
In an interview, Ian Lustick and Eli Clifton discuss their new book on why a prominent ally has so much influence in America.
Michael Young
Countries like Germany and India are caught between the great powers when developing AI. Racing ahead to develop AI has benefits and risks, as does depending on those great powers.
Anton Leicht, Sam Winter-Levy
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
Trump has promised Belarus a massive potash deal. But Minsk is seeking something greater: restored Western transit and greater room for maneuver from Russia.
Balázs Jarábik
The real test may come after the leaders leave the room.
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …