

Commentary
Alexander Gabuev
{
  "authors": [
    "Alexander Gabuev"
  ],
  "type": "commentary",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Russia Eurasia Center"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "East Asia",
    "China",
    "Russia"
  ],
  "topics": [
    "Economy",
    "Trade",
    "Civil Society"
  ]
}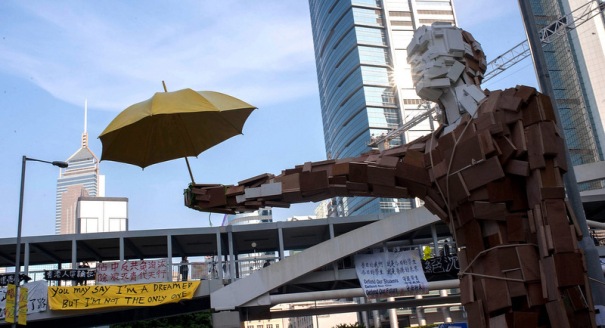
Source: Getty
For Russian business interests who use Hong Kong as a base for operations in mainland China or the Asia-Pacific region, or are listed on the Hong Kong Stock Exchange (HKEx), prodemocracy demonstrations were bad news.
When prodemocracy demonstrations erupted in Hong Kong in the last week of September, it was bad news for many stakeholders. Firstly, it was bad news for the Chinese leadership. Mass protest rallies in this Special Administrative Region (SAR) posed a challenge for Beijing and the “one country two systems” model it promotes to peacefully regain control over Taiwan. The possible collapse of the model, not the spread of the protests to other PRC regions, which for now remains highly unlikely, is the worst-case scenario for the Communist Party of China (CPC).
While President Xi Jinping was consolidating power and becoming more involved in every aspect of decision making, the National People’s Congress chief Zhang and PRC vice-president Li Yuanchao, who chair the CPC’s Leading Group on Hong Kong and Macau Affairs (Li is Zhang’s deputy in the group) didn’t see the crisis coming and now have to bear the consequences.
Second, the protests are bad news for the Hong Kong business community, most notably the billionaire families like Li Ka-shing’s (Forbes puts his family wealth at 31,6 billion dollars) and other local moguls with close ties to mainland China and the CPC. Last but not least, there are numerous international companies who use Hong Kong, with its competent governance and low taxes, as a base for operations in mainland China or the Asia-Pacific region, or are listed on the Hong Kong Stock Exchange (HKEx). Russian business interests fell into the third category of stakeholders hurt by the crisis.
Current Russian exposure to Hong Kong is growing, but is still very low. Bilateral trade reached about 3 billion dollars last year—nearly a 10 percent increase from 2012, but still just 0.4 percent of Russia’s foreign trade. Since Russia and Hong Kong abolished visas for journeys up to 14 days, the number of tourists has increased. Last year nearly 223664 Russians visited the SAR—still a small fraction of the 54 million foreigners (including 36 million mainland Chinese) who visited Hong Kong in 2013. Just two companies with significant operations in Russia are listed on HKEx—Rusal and Petropavlovsk. Several companies, including state-owned bank VTB, have issued bonds, others have used Hong Kong as operations hub for offshore transactions in yuan.
But since the outbreak of war in Ukraine and Western sanctions against Russia, the importance of Hong Kong for Russian companies has grown. Many businesspeople and government officials from Russia have visited the city this year; the last was Federation Council chairwoman Valentina Matvienko, who promised to help Russian companies raise capital in Hong Kong. Now, insiders confess that due to the political risks, many companies in Russia are wary of investing in Hong Kong. Lack of expertise on Asia in the Russian corporate sector reinforces this fear—corporate executives look at the protests on their TV screens and see another violent Maidan without understanding the nature of the events and risks generated by the demonstrations.
There is another element of the Hong Kong crisis’ influence on Russian companies’ attempts to diversify their sources of foreign capital. The HKEx administration and the Shanghai government have promised to establish a link between two largest stock exchanges in PRC by the middle of October. A pilot scheme would allow Hong Kong investors to buy shares and bonds of the 546 companies traded in Shanghai, with the volume of deals not exceeding 3.8 billion dollars a day. That first step could help to turn the now tightly regulated Shanghai Stock Exchange (SSE), where foreign companies aren’t allowed to list any instruments, into a more attractive capital platform. But the timely establishment of such a link is currently in question, and so are the hopes of Russian companies that Shanghai could soon turn into yet another replacement of London or New York for them.
Alexander Gabuev is deputy editor-in-chief of Kommersant Vlast.
Director, Carnegie Russia Eurasia Center
Alexander Gabuev is director of the Carnegie Russia Eurasia Center. Gabuev’s research is focused on Russian foreign policy with particular focus on the impact of the war in Ukraine and the Sino-Russia relationship. Since joining Carnegie in 2015, Gabuev has contributed commentary and analysis to a wide range of publications, including the Financial Times, the New York Times, the Wall Street Journal, and the Economist.
Recent Work
Alexander Gabuev
Alexander Gabuev
After the chill in ties between 2020 and 2024 that brought India–China relations to their lowest point in several decades, the two countries have engaged each other afresh. This paper argues that there are predominantly four imperatives guiding India’s approach to China, and they exist in an order of priority.
Saheb Singh Chadha

This piece argues that India’s central challenge is not managing a single flashpoint but resolving the underlying tension between expansion and institutional coherency of the BRICS grouping.
Vrinda Sahai
On March 10, 2026, India’s Union Cabinet approved amendments to Press Note 3, a regulation that mandated government approval on all foreign direct investment (FDI) from countries sharing a land border with India. This amendment raises questions primarily about whether its stated benefits will materialize and if the risks have been adequately weighed. This piece will address the same.
Konark Bhandari
This piece examines India’s response to U.S. sanctions and tariffs, specifically assessing the immediate market consequences, such as alterations in import costs, and the broader strategic implications for India’s energy security and foreign policy orientation.
Vrinda Sahai
This paper examines the evolution of India-China economic ties from 2005 to 2025. It explores the impact of global events, bilateral political ties, and domestic policies on distinct spheres of the economic relationship.
Santosh Pai