

Commentary
Uri Dadush
{
  "authors": [
    "Uri Dadush"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "Western Europe"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
Countries that can afford to continue to spend, including the United States, should not abandon fiscal stimulus until the private sector recovery is clearer.
Source: Council on Foreign Relations

Countries that can afford to should continue fiscal stimulus until the private sector recovery is clearer. Among the G7, this group clearly includes the United States, Germany, France, and Canada, and may include Britain and Japan, but not Italy. Further fiscal stimulus is essential in Germany, where domestic demand is stagnant and exports are booming, putting even more pressure on the European periphery. Germany has too much at stake in the euro to pursue mercantilist policies. Booming China's massive stimulus must be withdrawn but gradually and with care, given the international uncertainty.
Originally published by the Council on Foreign Relations, July 15, 2010
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Recent Work
Uri Dadush
Uri Dadush
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
As the U.S. stumbles in its war with Iran, we are likely to see an acceleration of its disengagement from the region.
Michael Young
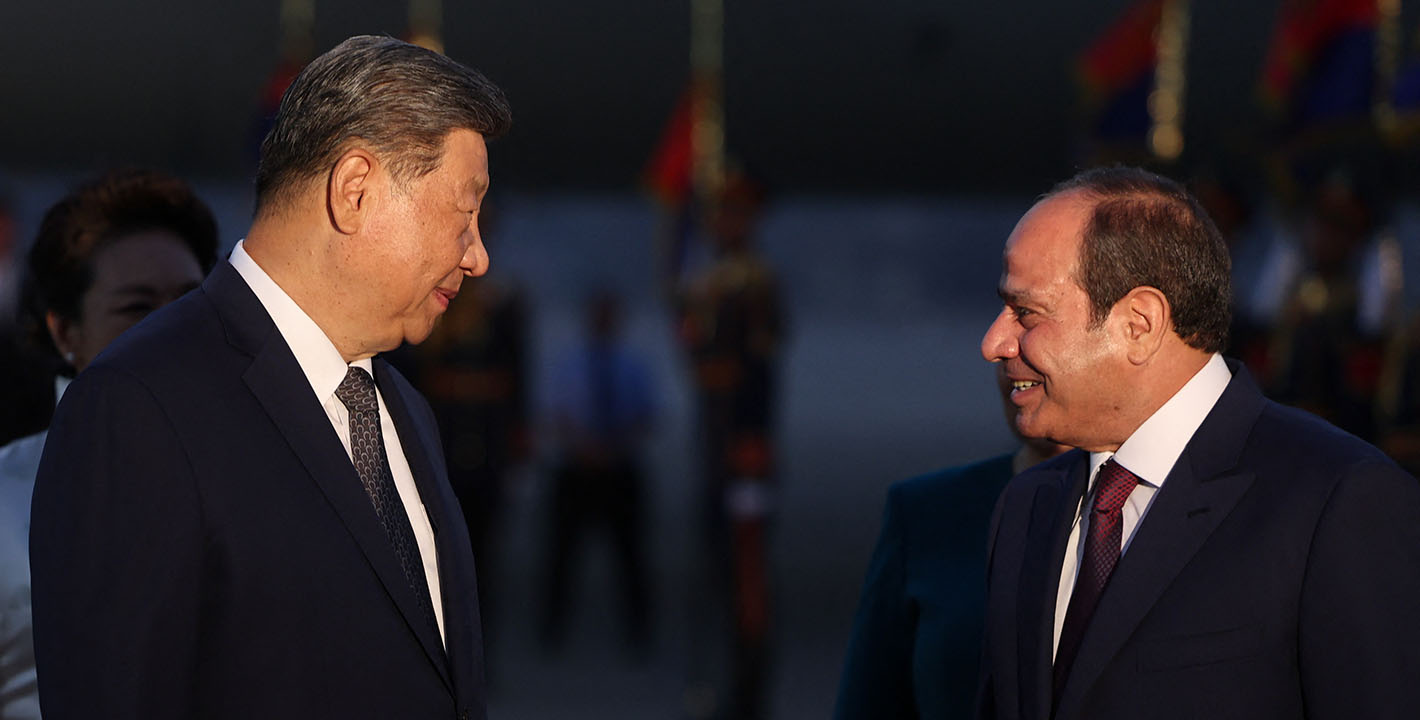
Huawei pushed hard to enter the Egyptian data centers market, until the Americans made a better offer.
Angie Omar
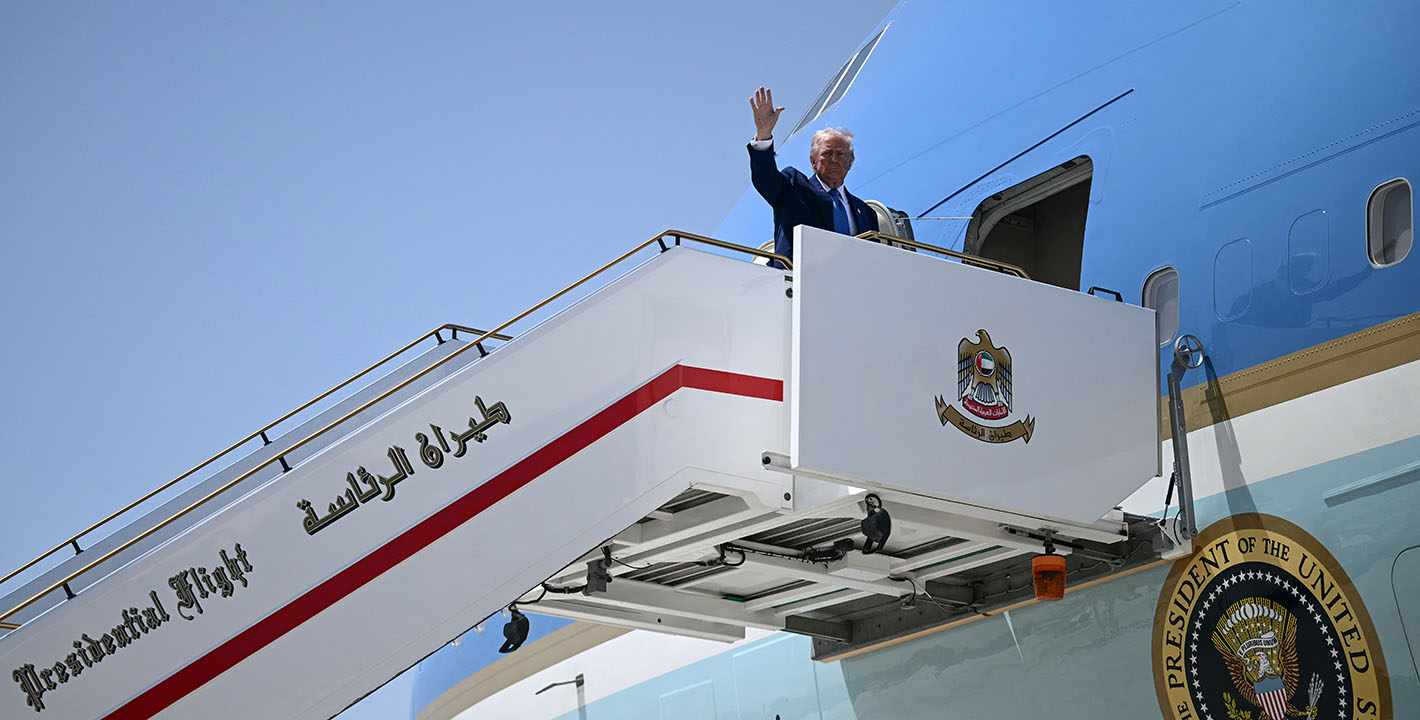
Middle Eastern states should welcome an accelerated U.S. disengagement from their region.
Michael Young
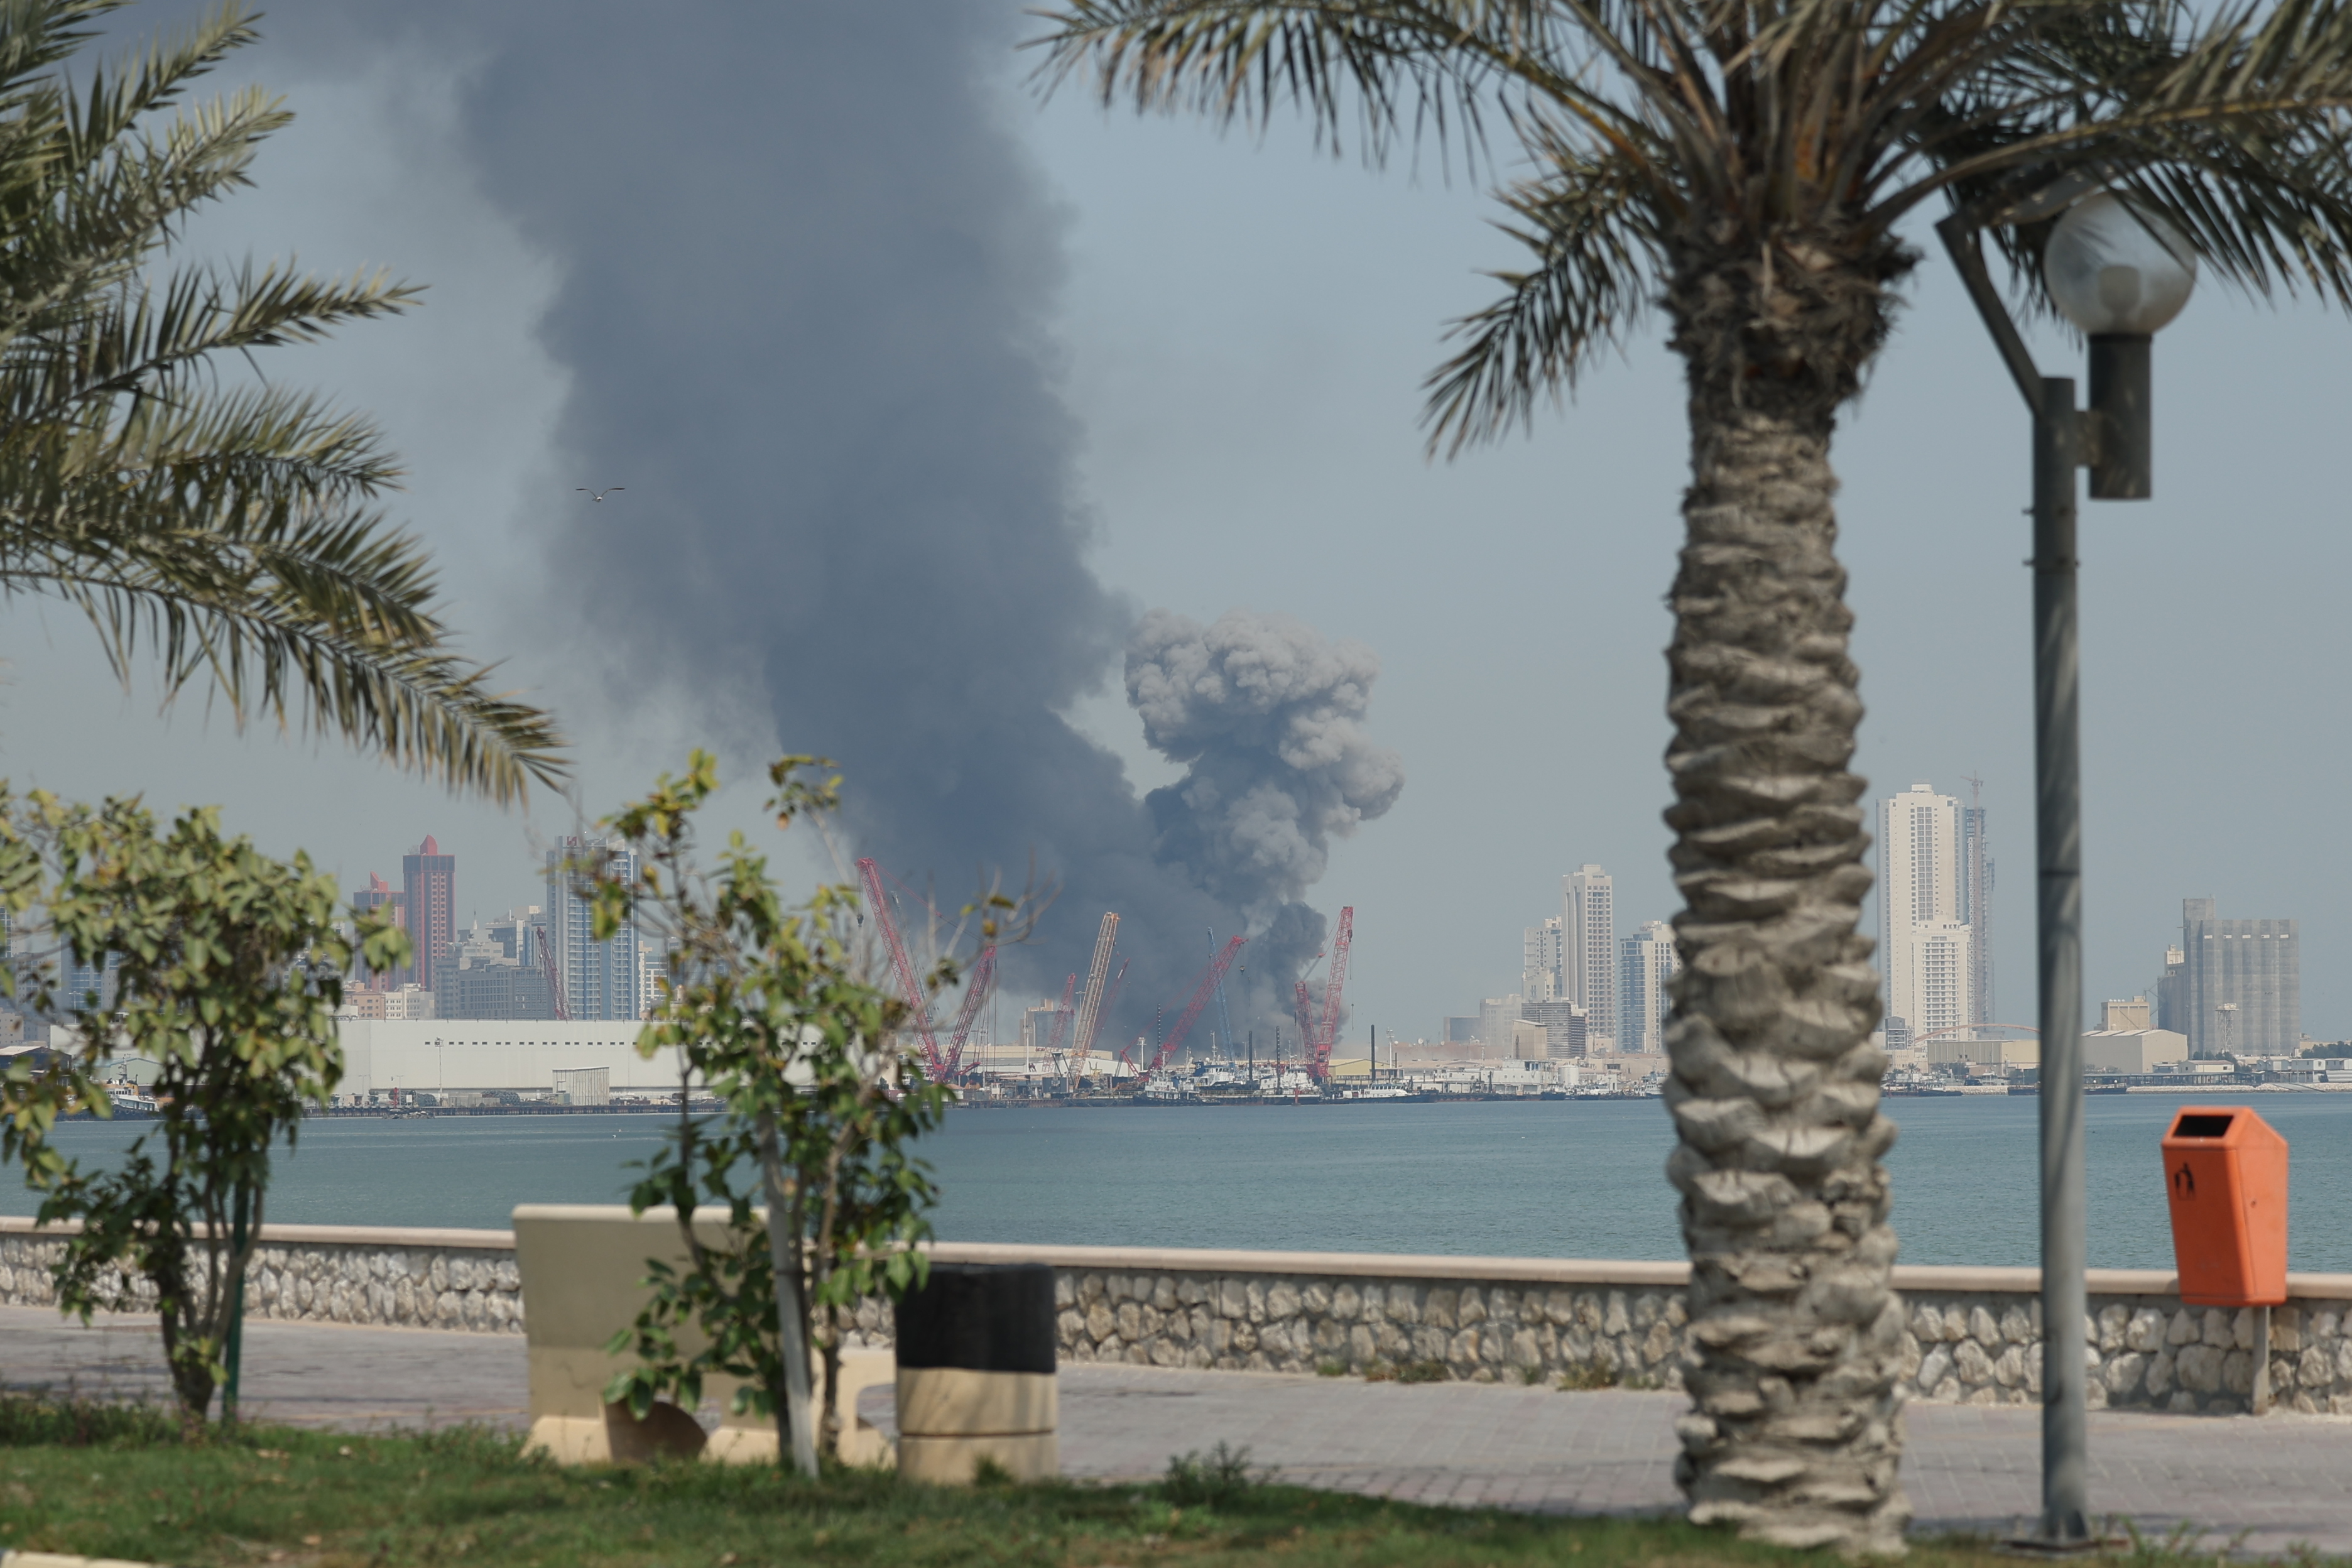
In an interview, former ambassador Charles Freeman assesses the Trump administration’s war against Iran.
Michael Young
By failing to address Palestinian representation, the current process is bound to lead to just another temporary arrangement.
Nathan J. Brown