

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "United States",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
With little chance that China will be able to increase its consumption rate to compensate for increased U.S. savings rates, the world may face a period of slower growth.
Source: The New York Times

These policies inevitably require households to foot the bill, primarily through sluggish wage growth, low interest rates on their bank deposits, an undervalued currency and a weak social safety net. Since total savings is just the difference between what is produced and what is consumed, subsidizing producers at the expense of household consumers necessarily causes savings to rise.
But Beijing’s massive stimulus will probably prevent the necessary adjustment toward faster consumption growth from taking place in the near future. Instead of reversing those policies that shift income from households to producers, which might have also caused a surge in unemployment, Beijing forced through a large increase in investment.
As in the past, households will be forced to foot the bill for any misallocated investment or non-performing loans, which could be considerable, making it difficult for households to power consumption growth.
This will be a problem for China and the world. As the U.S. rebalances its economy toward higher savings rates, China has no choice but to rebalance toward higher consumption rates. This can happen either because of a sharp pick-up in consumption growth or, more likely, a sharp slowdown in GDP growth. I worry that China will find it difficult to generate the kind of consumption growth that will take up some of the American slack, and we may be locked into a period during which the world adjusts by growing more slowly.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
China’s political future will be shaped between now and next October. As the Communist Party enters its intense “campaign season” to prepare for a major political transition in 2027, reading Beijing's actions and responses may become more difficult as domestic politics weigh on its behavior more than usual.
Damien Ma
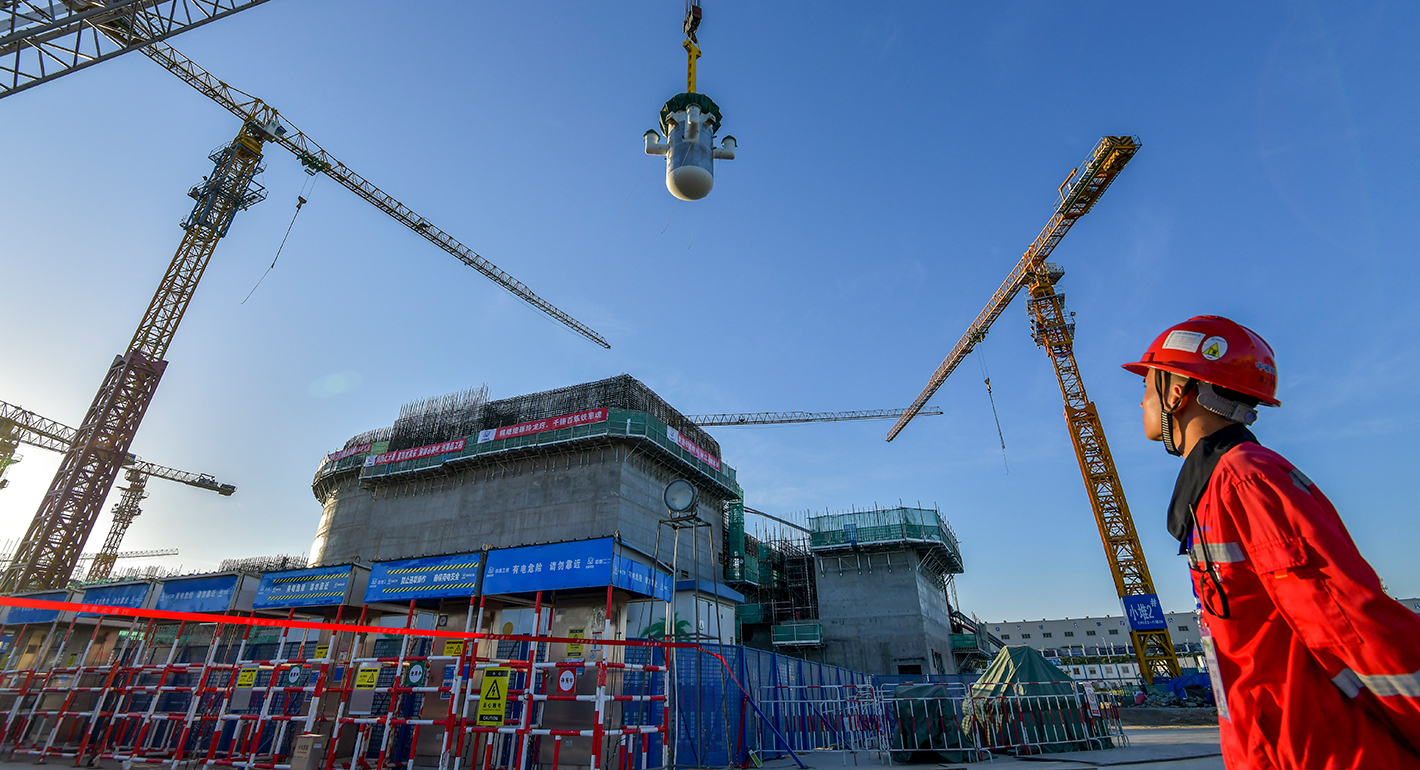
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
Tong Zhao
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
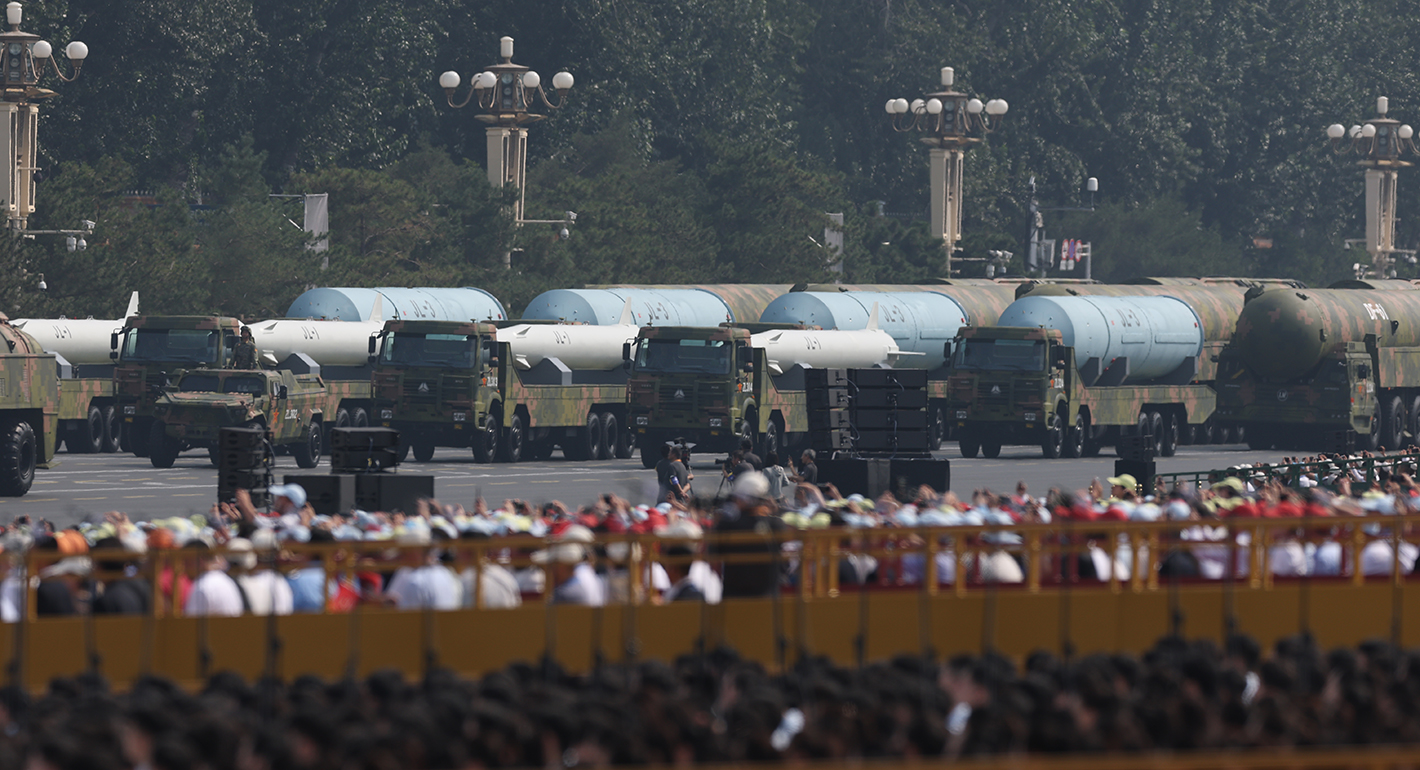
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis