• Commentary
  • Research
  • Experts
  • Events
Carnegie China logoCarnegie lettermark logo
{
  "authors": [
    "Uri Dadush"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "Western Europe"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty

In The Media

Is More Fiscal Stimulus Needed?

Countries that can afford to continue to spend, including the United States, should not abandon fiscal stimulus until the private sector recovery is clearer.

Link Copied
By Uri Dadush
Published on Jul 15, 2010

Source: Council on Foreign Relations

Is More Fiscal Stimulus Needed?Fiscal stimulus is neither as effective as its advocates claim nor as expensive as its opponents claim. According to the OECD and IMF, stimulus spending may only have prevented one-fifth of the 5 percentage point increase in unemployment during the crisis and accounted for one-fourth of the 7.5 percent drop in deficit-to-GDP ratios in advanced countries. Nevertheless, the decision of whether or not to continue fiscal stimulus should be based on three considerations:

  • The state of the global recovery. It is happening, but we are not out of the woods yet. The global economy has been growing for at least a year, but unemployment and excess capacity remain high, and private demand growth shows signs of slowing. Though emerging markets are still pulling world demand, Europe's debt crisis poses a big threat.

  • The capacity of monetary policy to keep the recovery going. With inflation still subdued, monetary policy can remain expansionary for the foreseeable future. Its effectiveness will be undercut, however, if risk-appetites falter and lenders hoard cash. Furthermore, exclusive reliance on monetary policy may create problems later, especially in the overheating, fast-growing emerging markets.

  • Confidence that countries can repay their debt. Markets continue to let large advanced countries borrow at record-low interest rates despite the 20-30 percent of GDP increase in their debt levels. However, Greece is probably bankrupt, and Spain and other troubled economies in Europe are paying a premium of 150-200 basis points over German rates. These countries have no choice but to reduce their deficits quickly.

Countries that can afford to should continue fiscal stimulus until the private sector recovery is clearer. Among the G7, this group clearly includes the United States, Germany, France, and Canada, and may include Britain and Japan, but not Italy. Further fiscal stimulus is essential in Germany, where domestic demand is stagnant and exports are booming, putting even more pressure on the European periphery. Germany has too much at stake in the euro to pursue mercantilist policies. Booming China's massive stimulus must be withdrawn but gradually and with care, given the international uncertainty.

Originally published by the Council on Foreign Relations, July 15, 2010
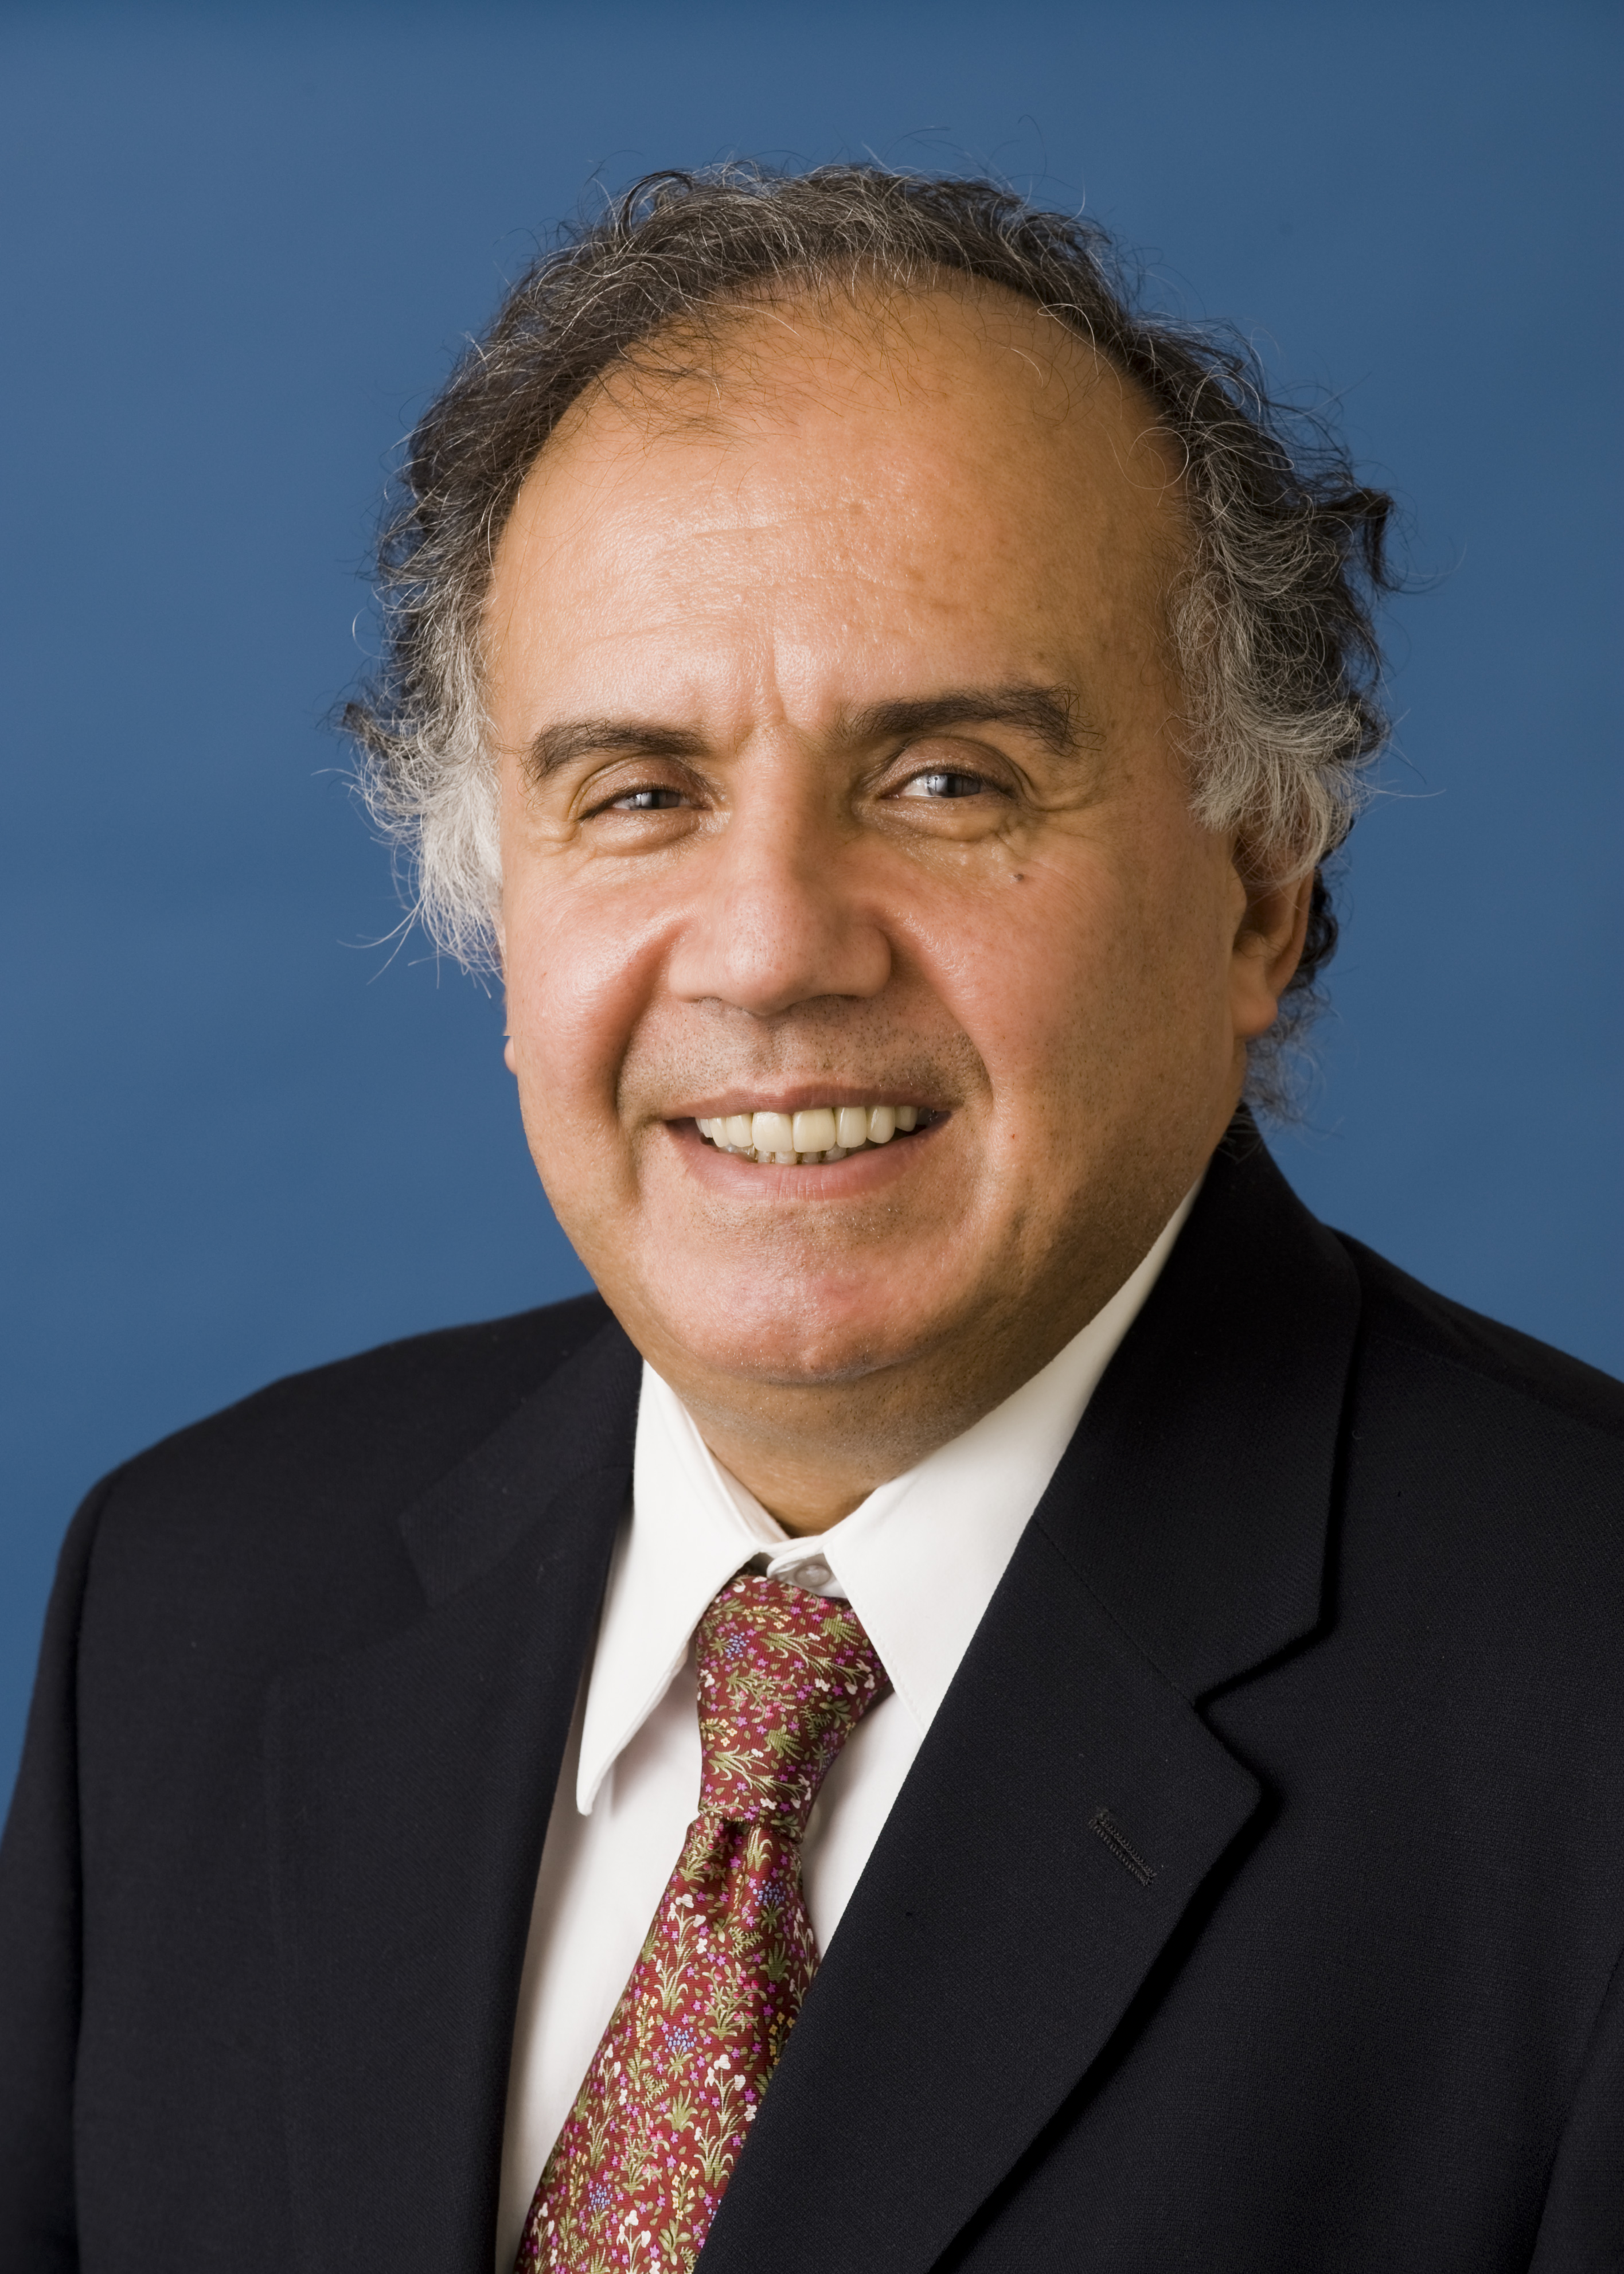
About the Author

Uri Dadush

Former Senior Associate, International Economics Program

Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.

    Recent Work

  • Commentary
    The Labors of Tsipras

      Uri Dadush

  • In The Media
    Greece, Complacency, and the Euro

      Uri Dadush

Uri Dadush
Former Senior Associate, International Economics Program
Uri Dadush
EconomyNorth AmericaUnited StatesWestern Europe

Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
More Work from Carnegie China

  • Commentary
    China Financial Markets
    The Plaza Accord and Its Relevance for China

    The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.

      Michael Pettis
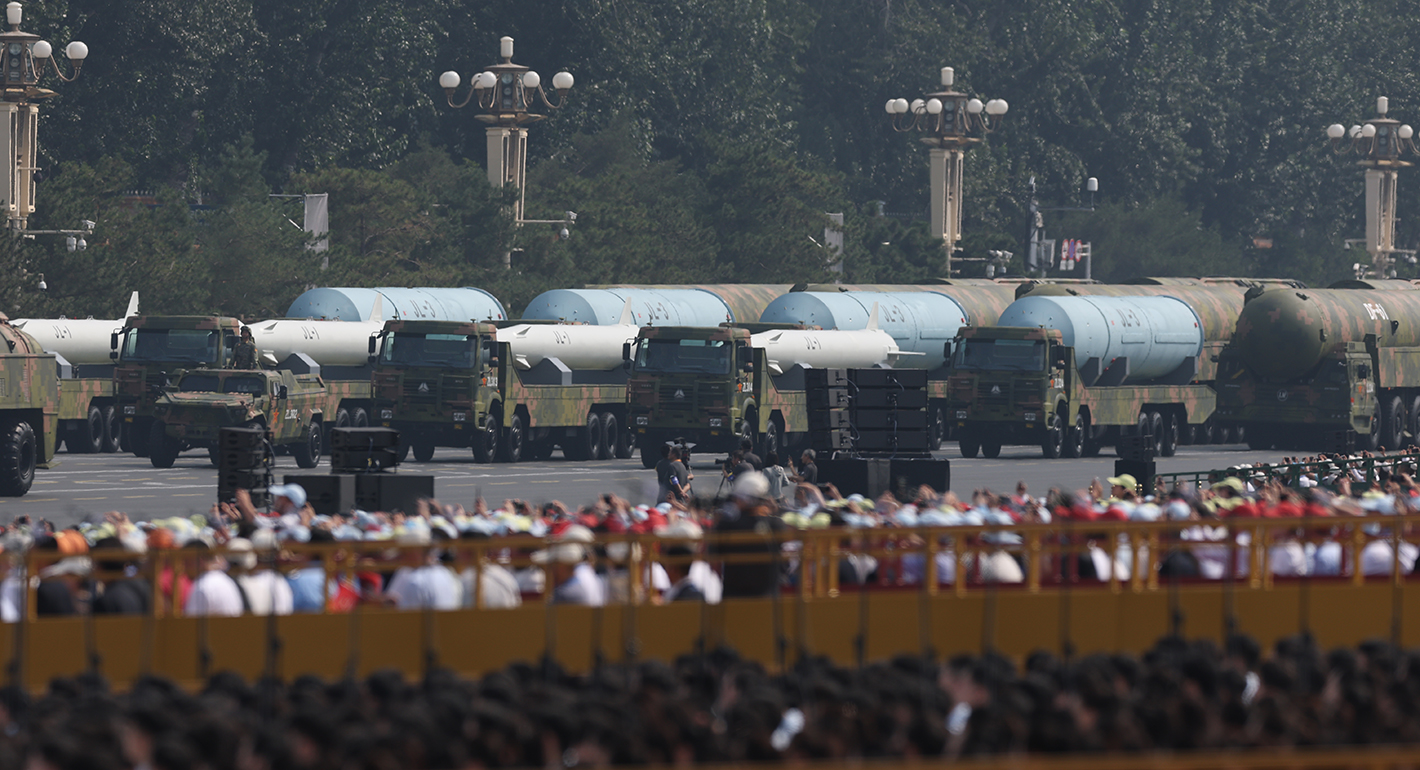
  • The nuclear missile formation passes through Tian'anmen Square during a military parade on September 3, 2025 in Beijing, China.
    Paper
    Untangling the Nuclear Knot: A Constructive Agenda for Managing China’s Nuclear Relations with the United States and Its Allies

    The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
      Tong Zhao

  • Commentary
    China Financial Markets
    Who Paid for China’s Last Debt Cleanup, and Who Will Pay for the Next?

    China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.

      Michael Pettis
  • Commentary
    Emissary
    Trump and Xi Are Angling for Three Years of Stability

    But their "principal to principal" model will only be as effective as the political strength of each leader back home.
      • Damien Ma

      Damien Ma

  • Commentary
    China Sells Stability Amid American Volatility

    U.S. unpredictability has allowed China to capitalize on its positioning as the “responsible great power”. Paradoxically, the more China wins the perception game, the more likely expectations will rise for Beijing to deliver not just words but to demonstrate with its deeds.
      Chong Ja Ian

Get more news and analysis from
Carnegie China
Carnegie China logo, white
Keck Seng Tower133 Cecil Street #10-01ASingapore, 069535Phone: +65 9650 7648
  • Research
  • About
  • Experts
  • Events
  • Contact
  • Careers
  • Privacy
  • For Media
Get more news and analysis from
Carnegie China
© 2026 Carnegie Endowment for International Peace. All rights reserved.