

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
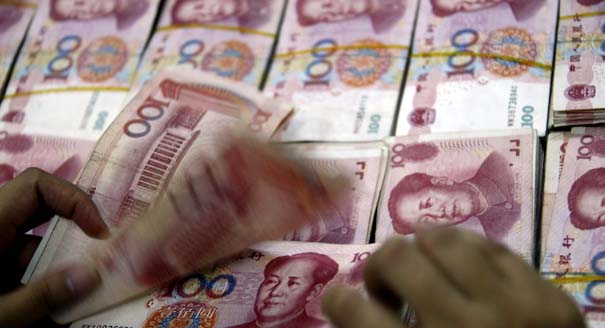
If China is pressured to reevaluate its currency too quickly, it will have to rely on overinvestment to head off rising unemployment, which would exacerbate the fundamental imbalances already present in the Chinese economy.
Source: The Financial Times

There are many ways for China to rebalance, although all involve transferring income from producers to households, so the latter can increase their share of consumption. Raising the value of the renminbi increases household income by reducing the cost of imports, although it also lowers the profitability of exports. The result, if done carefully, should nonetheless see the household share of China’s gross domestic product rise, and with it consumption. Since more of what China produces is then consumed domestically, China’s trade surplus should fall too.
But what would happen if China raised its currency too quickly, as most of its trading partners want and as Mr Wen warned against? In that case, the profitability of the export sector would decline so quickly that exporters would be forced either into bankruptcy or into lower-wage countries. They would fire workers, who would then consume less. So China faces a choice: rebalance speedily with high unemployment, or slowly with low unemployment.
That is why too much focus on the currency is dangerous. It is clear that the US and other countries have become impatient with China’s slow adjustment. Every large world economy, including China, is implicitly expecting US consumption to drive employment growth, as Mr Wen all but told President Barack Obama in New York in late September.
However, with soaring unemployment at home, the US is in no mood to divert more of its demand abroad. America wants to boost its own exports, and there is a good chance that it will now overreact to Chinese foot-dragging and use the threat of tariffs to force a faster appreciation than China can afford.
In that case, what will Beijing do? Most probably, as Japan did after the 1985 Plaza Accords and Beijing itself did after the renminbi began appreciating in 2005, it will lower real interest rates and force a surge in investment by expanding credit rapidly. This will unwind the unemployment rise caused by renminbi appreciation: as manufacturers in the tradable goods lose competitiveness others will enjoy lower financing costs. But there will be a high price to pay.
Revaluation will divert income from exporters to households, as it should, but the response will then shift income from households (who provide most of the country’s net savings) to large borrowers with access to bank credit. China won’t really rebalance, which requires a permanent increase in the household share of GDP. Instead the country’s overdependence on exports will be reduced, but its even greater overdependence on investment will increase. Textile producers and toy manufacturers will shed jobs, while shipbuilders and steel producers will expand.
This would be terrible for China. Lower interest rates and more credit will fuel a real estate boom, and boost both capital-intensive manufacturing and infrastructure overcapacity – all without rebalanced consumption. It will also increase pressure on the likes of Japan and South Korea, which rely on capital-intensive industries. China, and surplus countries such as Germany and Japan, must understand that their policies damage the rest of the world. But the world also needs to understand that these countries cannot adjust quickly without damaging internal consequences.
Any solution will therefore require statesman-like behaviour, in which the major economies agree to resolve their trade imbalances over several years. But periods of global economic contraction and rising unemployment do not usually welcome statesmen. Sadly, it is much more likely that trade relations will continue to deteriorate, and the longer surplus countries drag their heels the more attitudes will harden. In that case, China’s overinvestment problem is certain to become even worse.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis
Chinese biotech companies have been on the receiving end of U.S. economic coercion. Yet their responses have differed significantly because firm and state interests are not uniformly aligned. For Washington, treating all Chinese tech firms the same, irrespective of their actual interests, risks pushing them farther into Beijing’s corner.
Xue Gong
China’s latest energy plan explicitly calls for integrating data centers into the electricity system, particularly connecting them to green energy. It appears Beijing wants to use compute as a source of domestic demand to absorb renewables excess capacity.
Damien Ma