

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
Persistent imbalances in China's economy are likely to pose a serious threat to the country's growth unless Beijing significantly revalues its currency, raises real interest rates, and continues to increase wages.
Source: Bloomberg
Carnegie’s Michael Pettis spoke on Bloomberg Television’s On the Move Asia about China's economy, central bank monetary policy, and currency. China’s consumer prices rose 5.3 percent in April compared to a year earlier, exceeding the government’s full-year target for a fourth straight month.
Although China's April inflation figures were slightly lower than the previous month, Pettis noted that many experts had predicted inflation rates would peak in July or August of this year. Thus, it remains to be seen whether inflation has started a long-term declining trend. Pettis added that although it may seem counterintuitive, raising interest rates may not be an effective way for Beijing to stem inflation, since such an action will increase household income and consumption, thus adding to inflationary pressure.
In order to rebalance its economy, Pettis suggested that Beijing needs to adopt a comprehensive approach that includes revaluing its currency, raising interest rates, and raising wages. Although wages are rising in real terms, after adjusting for inflation and productivity growth differentials, "the currency is barely appreciating in real terms," Pettis said. Most importantly, although nominal interest rates have gone up, real interest rates have actually been negative. Thus, Pettis stated, "In the aggregate, it is very hard to say that China is rebalancing."
These continued imbalances were discussed in a recent IMF report which noted that consumption growth in China slowed last year, Pettis noted. Moreover, massive increases in investment in China are becoming increasingly misallocated and ineffective, which historically has always been associated with an unsustainable rise in debt. If such trends continue, this excessive investment will pose a serious threat to China's growth.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
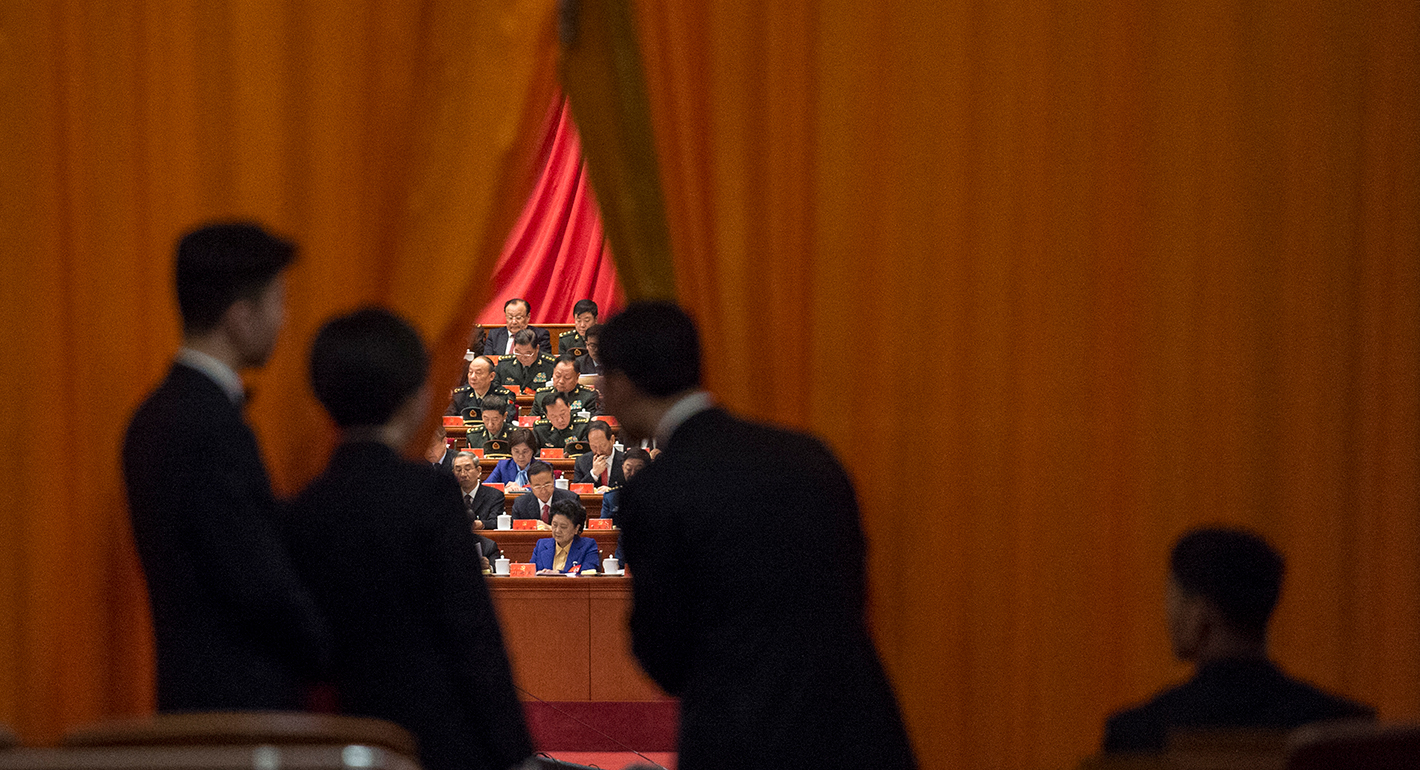
China’s political future will be shaped between now and next October. As the Communist Party enters its intense “campaign season” to prepare for a major political transition in 2027, reading Beijing's actions and responses may become more difficult as domestic politics weigh on its behavior more than usual.
Damien Ma
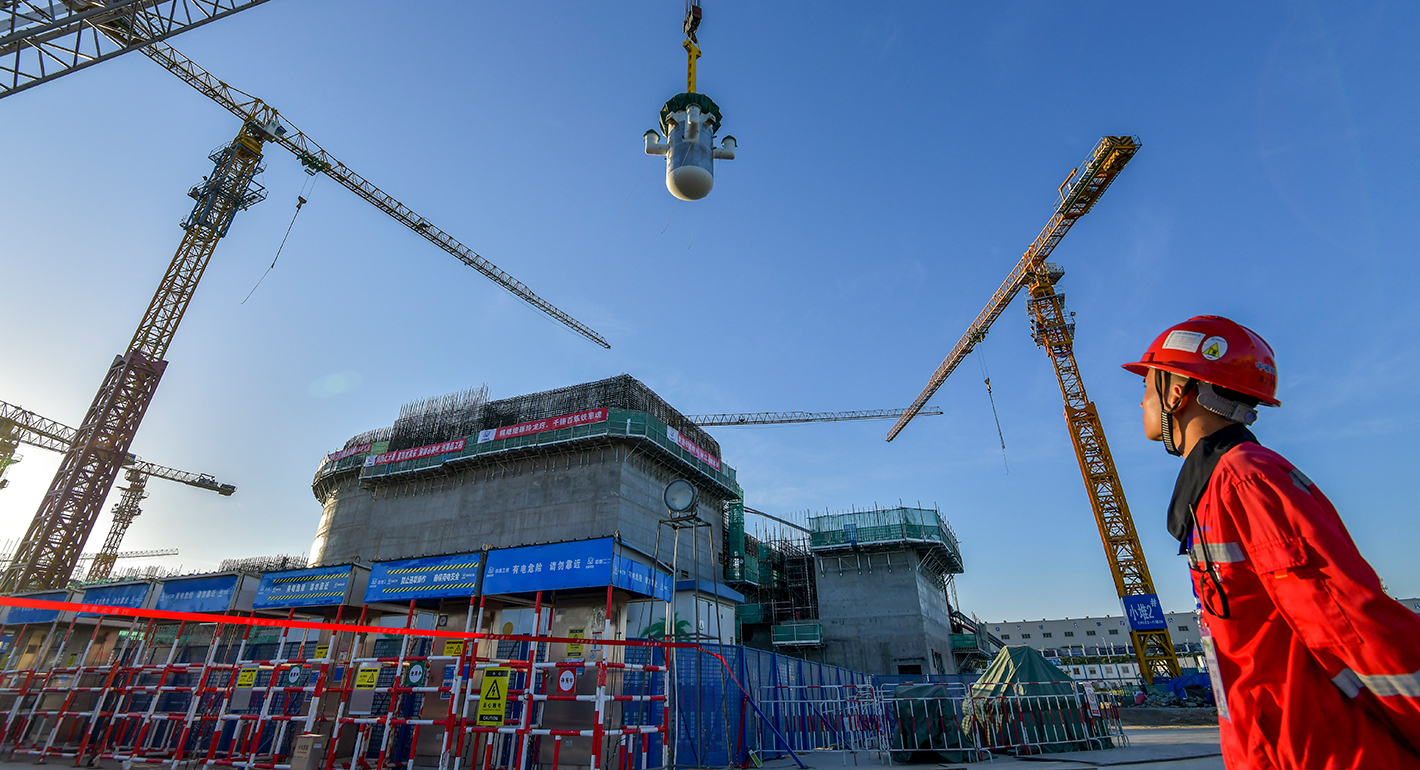
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
Tong Zhao
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
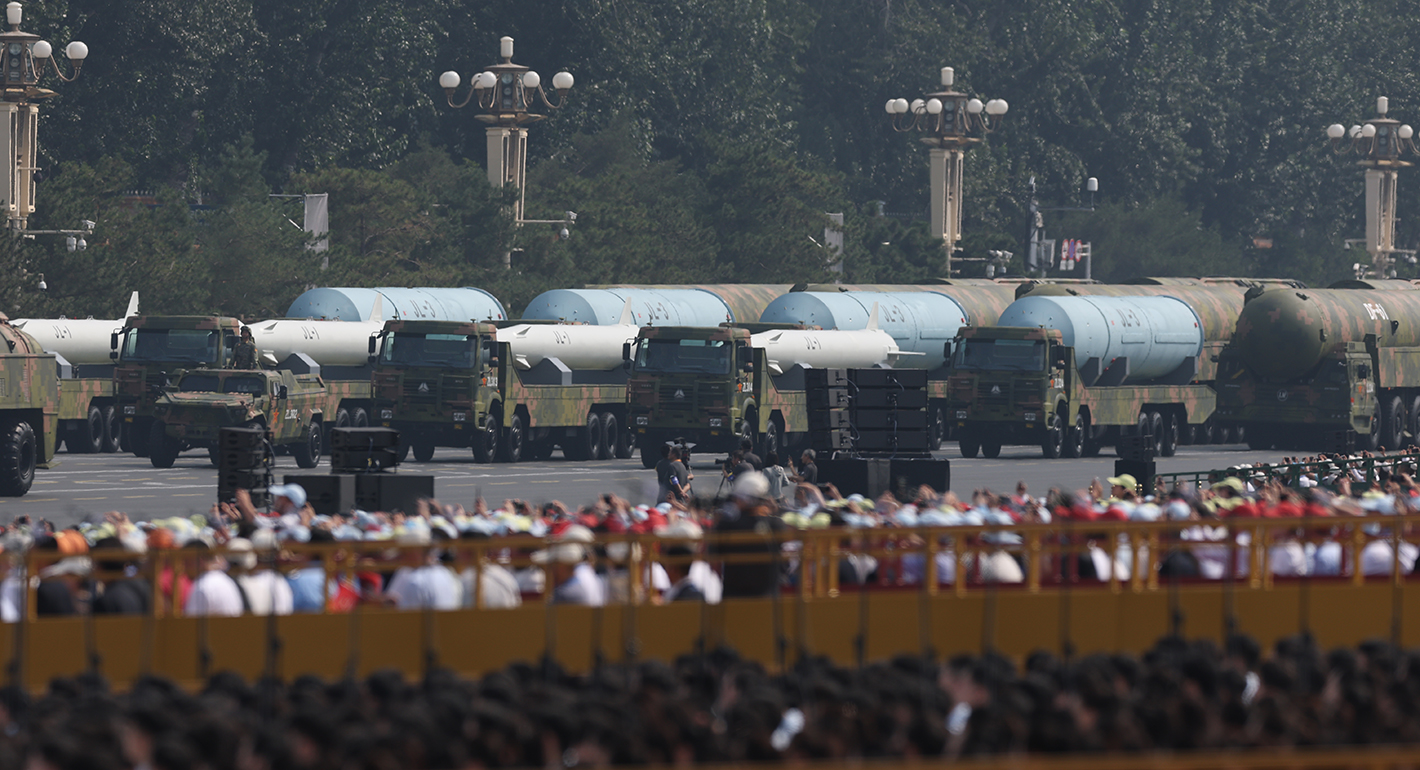
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis