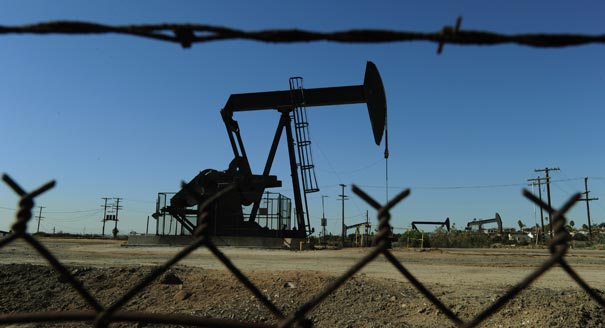
The United States needs an innovative transportation revenue mechanism that will help to stabilize gas prices, restore solvency to a broke and broken program, and help America rebuild its infrastructure and economy.
Link Copied
By Bill Bradley, Tom Ridge, David Walker
Published on Aug 2, 2011
Source: Bloomberg
Here's a Tax That Ends Pain at the PumpThe U.S.’s national transportation program is broke. We borrow about $12 billion from the Treasury annually for the Highway Trust Fund. But our real annual transportation deficit is more than $100 billion when you include interest, deferred maintenance and other spending.
At the same time, the 55-year-old Interstate Highway System is crumbling and needs to be rebuilt, at an estimated cost of $2.5 trillion to $3 trillion during the next 20 years.
We have no choice but to find new revenue. The way to do it is with a revamped federal gas tax. The gas tax, last raised to 18 cents a gallon in 1993, now has a buying power of 11 cents. In the same period, our real gross domestic product has grown 55 percent and our driving has increased 31 percent. The president’s fiscal commission -- widely cited as a bipartisan road map for tax reform-- recommended an immediate gas-levy increase of 15 cents.
But simply raising the gas tax won’t address a serious threat to our economic well-being -- wild swings in pump prices due to spikes and crashes in world oil prices. Europe, with gas taxes averaging more than $4 a gallon, faces this same risk. Gas taxes that increase with the price of oil can just make matters worse. Any plan for transportation solvency must include a price-stabilization mechanism so that rising oil costs don’t crush household budgets or the economy.
Security Fee
To accomplish this, we propose establishing a value-added oil-security fee at the refinery or point of importation. This fee would be a fixed percentage based on the price of a barrel of oil. In addition to the levy, there would be a varying retail tax on gas. When oil prices increase, the gas tax is reduced. When they decline, the gas tax would rise, thus offsetting diminished oil-security fees due to lower oil prices.
For example, if a 5 percent oil-security levy were assessed when oil costs $100 a barrel, the fee would be $5 a barrel and yield, at present levels of oil consumption, about $28.3 billion a year. At $115 a barrel the gas tax per gallon could be abated by 5 cents (assuming abatement at 1 cent for every $3 increase in oil price) but the oil fee would rise to $5.75 a barrel, offsetting the lost gas-tax revenue. If the price of oil fell to $90 a barrel, the oil fee would also drop 50 cents a barrel, but the gas tax would rise by 10 cents a gallon, more than offsetting the lost oil-fee revenue. Thus, oil companies pay more when their profits increase, and consumers would bear more cost when oil prices -- and prices at the pump -- fall.
Share the Burden
This share-the-burden strategy would raise the revenue needed to restore transportation solvency and the infrastructure investments that would help the economy grow. This plan would also assist consumers by encouraging gas-price stabilization. Conceptually, this shifts responsibility for transportation funding from a straight “user pays” approach (gasoline consumers) to a “beneficiaries pay” system (both producers and consumers). Because both oil companies and consumers benefit from transportation investments, this is fair.
We understand that this plan wouldn’t stop large price swings in energy markets. Oil and gasoline values will continue to fluctuate for many reasons, including some that have nothing to do with underlying oil supply and demand. But this countercyclical pricing plan would help trim price peaks and troughs while sending a signal that public policy would be used to fight price manipulation by the hedging or hoarding that exploit bottlenecks in oil markets.
It would also allow us to rebuild our infrastructure and our economy. We need to invest in new, intelligent and integrated transportation systems; build smart, low-carbon cities; revolutionize freight logistics; and develop systems that efficiently move products through our ports, rail yards and airport gateways. We have an opportunity to address our infrastructure problems. The longer we wait, the more future generations will pay for our neglect.
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
U.S. unpredictability has allowed China to capitalize on its positioning as the “responsible great power”. Paradoxically, the more China wins the perception game, the more likely expectations will rise for Beijing to deliver not just words but to demonstrate with its deeds.