

In The Media
Josh Kurlantzick
{
  "authors": [
    "Josh Kurlantzick"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
The biggest economic threat from China isn't its dominance of manufacturing or its artificially pegged currency. It's that the world's soon-to-be third-largest economy is being fueled by financial markets that remain essentially--and dangerously--lawless.
Source: The New Republic

Still, as the world is beginning to find out, the biggest economic threat from China isn't its dominance of manufacturing or its artificially pegged currency, both of which we've known about for some time. It's that the world's soon-to-be third-largest economy is being fueled by financial markets that remain essentially--and dangerously--lawless.
Since 1990, the Chinese government has put much effort into promoting its Shanghai Stock Exchange, positioning it as a potential competitor to the Hong Kong Exchange and Tokyo's Nikkei. (China also has a third stock exchange in the southern city of Shenzhen.) So far the effort has paid off. As average urban Chinese have gotten richer from the country's rapid economic growth, they have jumped onto the day-trading bandwagon with gusto. On a recent trip to China, nearly every urban professional I met in Shanghai and Hangzhou was day trading in his or her free time, and there are now as many as 100 million Chinese brokerage accounts
Problem is, most of these new traders on the Shanghai Stock Exchange know virtually nothing about investing, and believe that because the government wants the exchange to succeed--and will not tolerate a collapse before the Summer Olympics--the market simply cannot fail. The link between the Chinese government and the Shanghai Exchange is seen as inextricable, and so far, that has mostly been a boon. In recent years, Chinese investors' confidence has been repaid by dramatic run-ups in the Shanghai exchange, which in 2007 was the best-performing major index in the world, rising a staggering 97 percent in one year alone.
But now the flaws in the Chinese markets are starting to surface. China's major indexes have already dropped more than 15 percent off their highs last fall, and could fall far further. Because of China's weak enforcement, most companies on the Shanghai exchange reveal precious little about their structure or finances, which was fine with local investors when the market was booming, but tells them nothing about whether these firms are really viable now. As two of my colleagues at the Carnegie Endowment, Minxin Pei and Wayne Chen, note, state-owned brokerage companies, rather than international financial firms, dominate trading in the market--yet these Chinese companies have been linked to repeated scandals. Insider trading and other scams are endemic to the Chinese markets, and generally bring little real punishment.
Just like its stock markets, China's banking sector retains a distinct Wild West flavor. Still forced to lend to companies with prime political connections but little financial prospects, many of China's banks are swamped with non-performing loans. To take one example, in 2006 the Agricultural Bank of China, one of the Big Four banks in the country, revealed that 23 percent of its loans were non-performing, a staggeringly high rate that forces the bank to constantly use capital to write off these NPLs. In comparison, 0.26 percent of Bank of America's loans were non-performing at the time.
Fifteen years ago, none of this would have mattered to the world; China's economy was a blip, it was isolated. But now that it's growing precipitously--holding vast currency reserves and heavily investing across the globe--its financial problems are our financial problems. Last February, for example, the Dow dropped over 400 points after rumors of a government crackdown on illegal trading, not to mention worries about an over-inflated market, prompted a major sell-off in China.
What's more worrisome when you consider last week's financial tumble is that many Chinese investors have never experienced a downturn before and do not have their money managed by large, calm institutional investors. They are likely to pull out of their stocks rapidly, adding to the anxiety across global markets. Panic among urban Chinese will likely also cut into their consumption, which will impact big American companies like General Motors and KFC, which have both built their long-term growth strategies on selling in China.
Meanwhile, as the Chinese government rushes to shore up its banks and state-linked companies, it must spend down some of its vast currency reserves, possibly reducing its purchases of U.S. Treasuries. Such a move would prove disastrous for the American economy, which relies on those purchases to stay afloat. Given America's tiny savings rate, without Chinese purchase of U.S. T-Bonds, the American economy would likely go into a downturn so severe, well, it's best not to think about it right now. Simply put, the world cannot afford for that to happen. China matters too much to the global economy for its markets and banks to be run with all the opaqueness of a bookie's office.
Joshua Kurlantzick is a visiting scholar of Carnegie Endowment for International Peace, and a special correspondent for The New Republic.
Former Visiting Scholar, China Program
A special correspondent for The New Republic, a columnist for Time, and a senior correspondent for The American Prospect, Kurlantzick assesses China’s relationship with the developing world, including Southeast Asia, Africa, and Latin America.
Recent Work
Josh Kurlantzick
Carnegie India does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.

How is AI reshaping space security, creating governance challenges, and where does international diplomacy stand today?
Tejas Bharadwaj, Almudena Azcárate Ortega
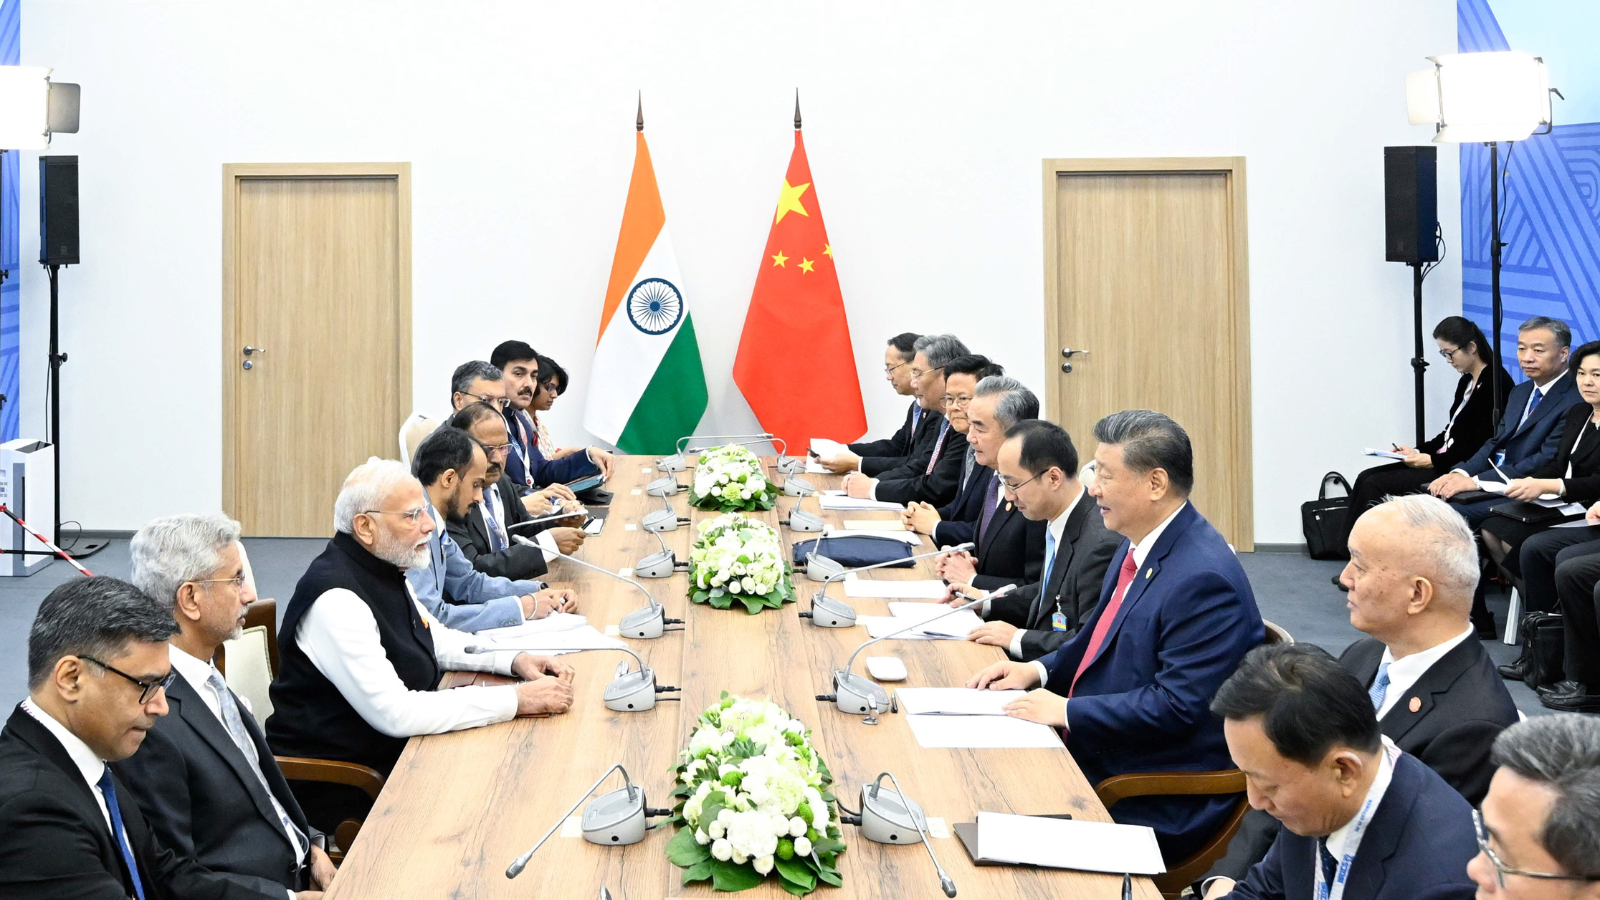
After the chill in ties between 2020 and 2024 that brought India–China relations to their lowest point in several decades, the two countries have engaged each other afresh. This paper argues that there are predominantly four imperatives guiding India’s approach to China, and they exist in an order of priority.
Saheb Singh Chadha

This piece argues that India’s central challenge is not managing a single flashpoint but resolving the underlying tension between expansion and institutional coherency of the BRICS grouping.
Vrinda Sahai
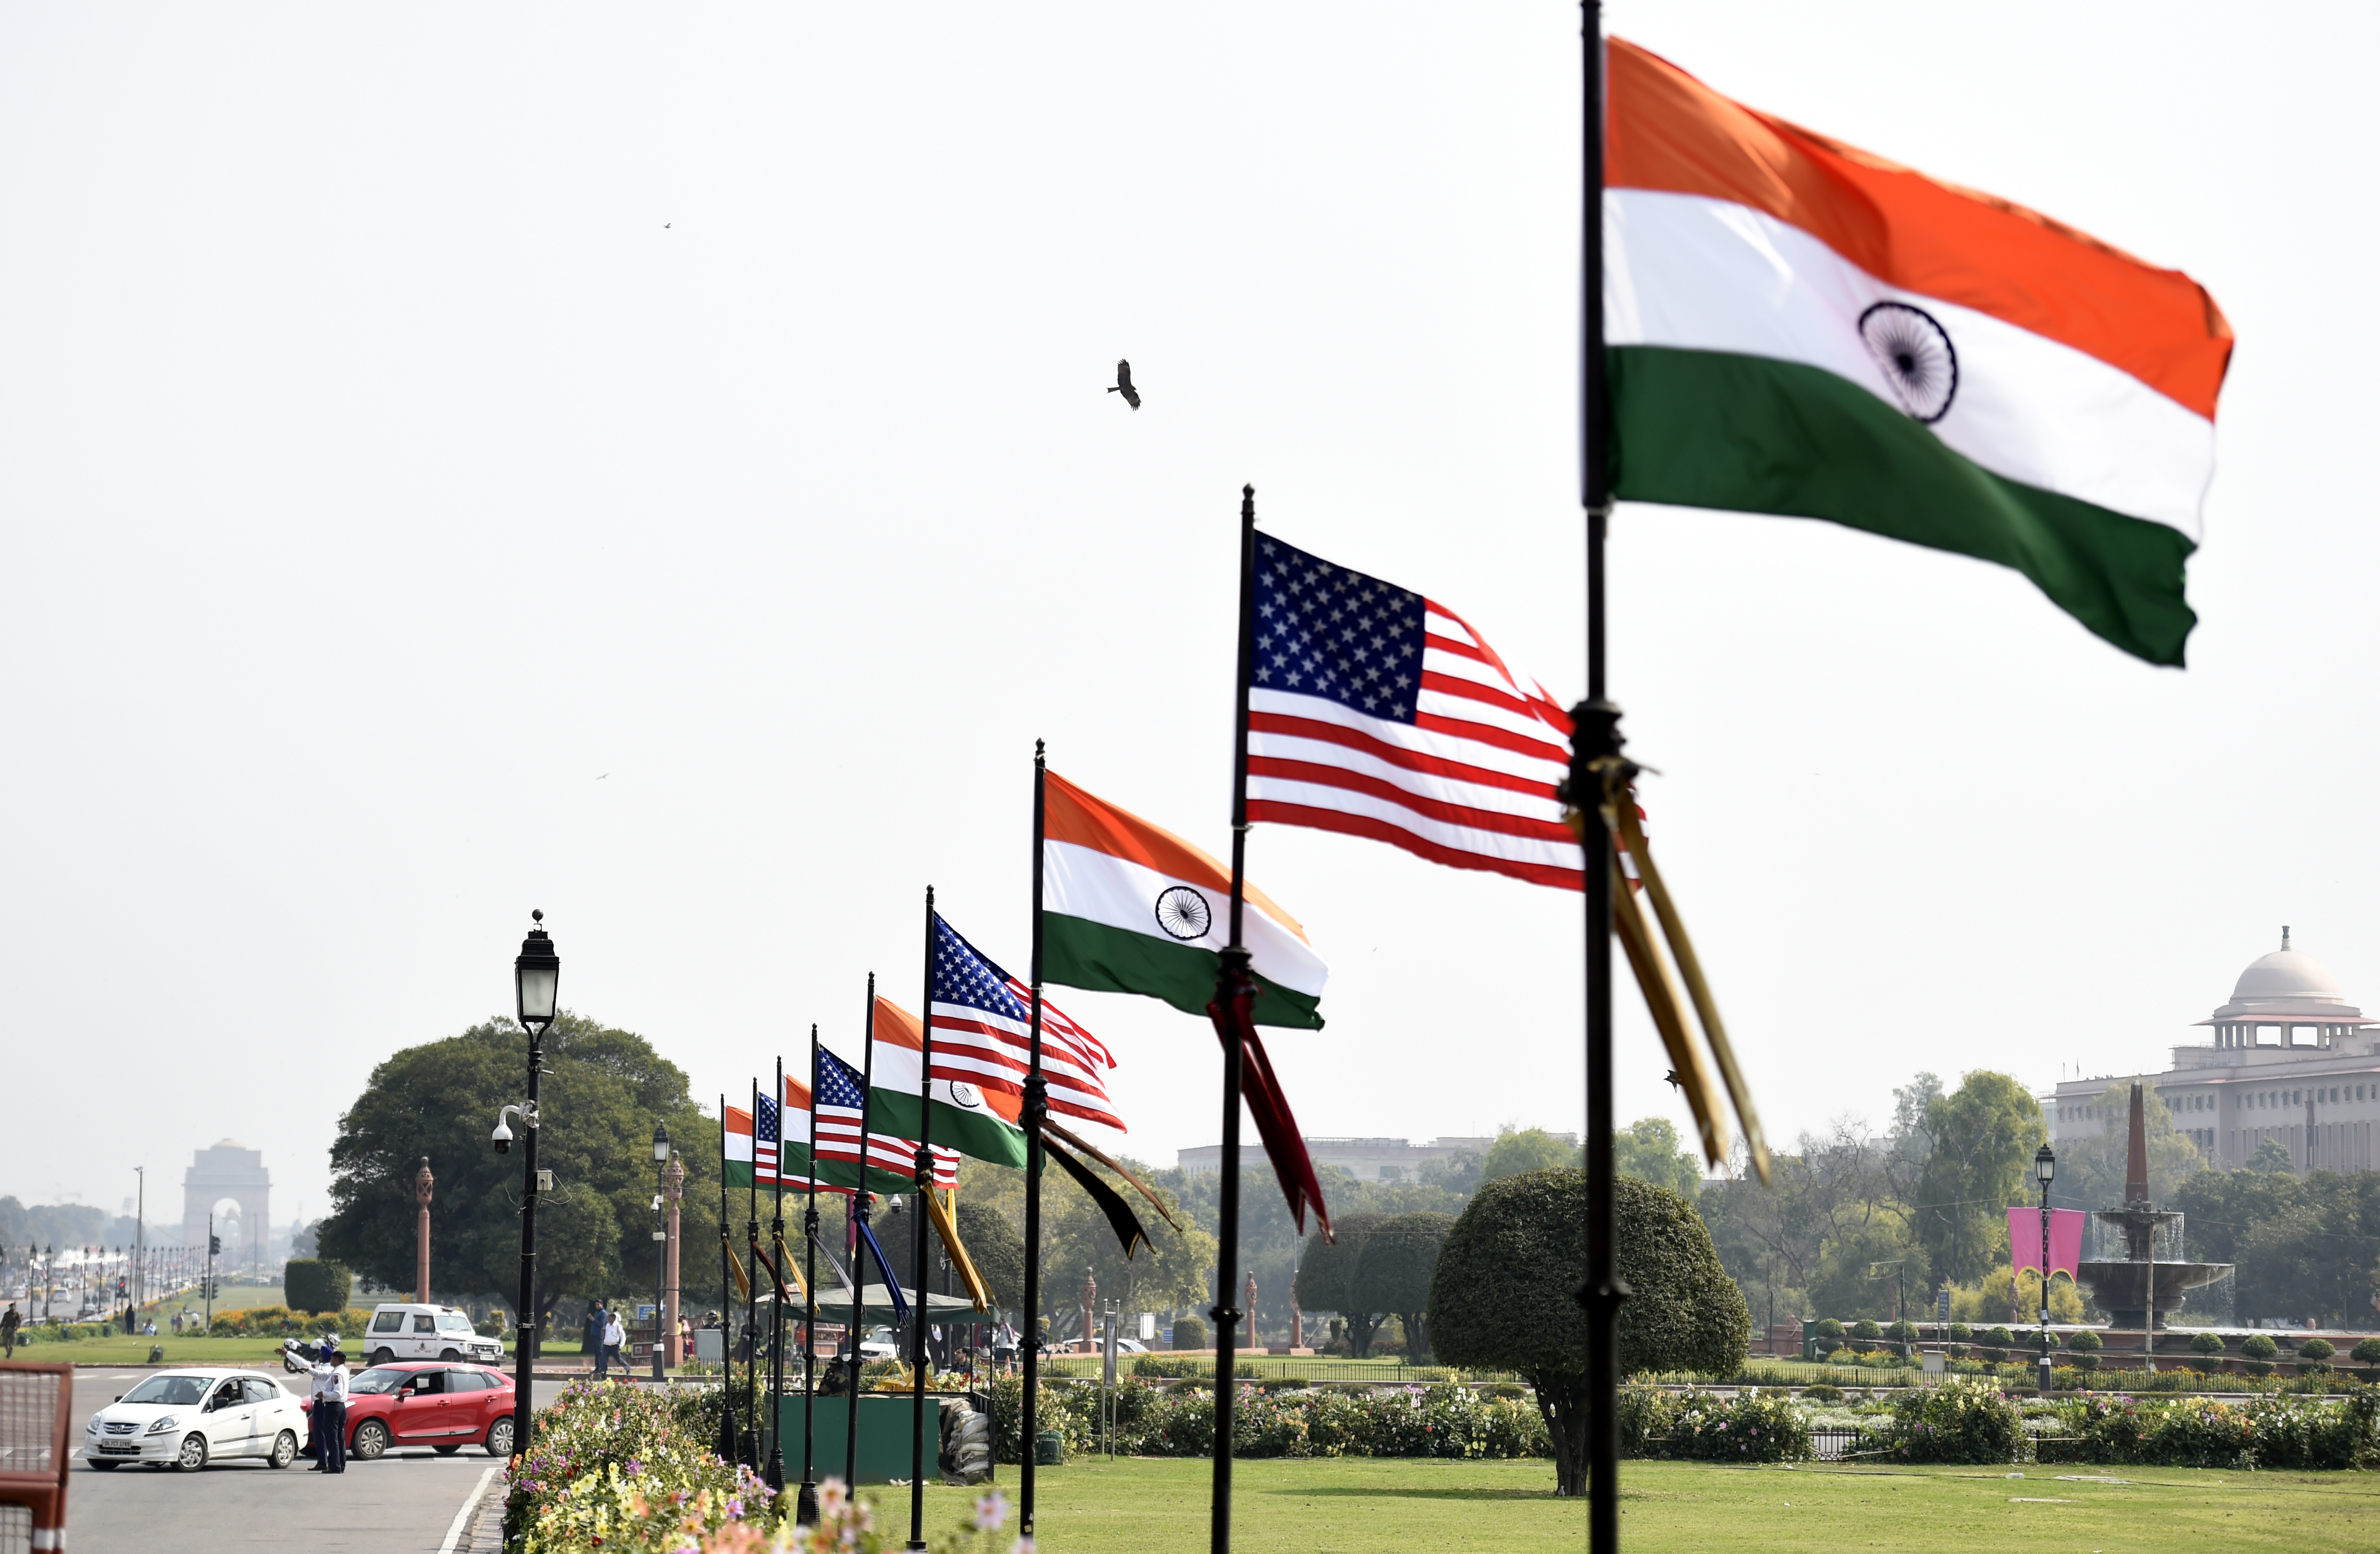
The U.S.–India semiconductor cooperation story is well-stocked with top-level strategic intent. What remains unresolved, however, are some underlying challenges that will determine whether the cooperation actually functions. Three such friction points stand out.
Shruti Mittal
On March 10, 2026, India’s Union Cabinet approved amendments to Press Note 3, a regulation that mandated government approval on all foreign direct investment (FDI) from countries sharing a land border with India. This amendment raises questions primarily about whether its stated benefits will materialize and if the risks have been adequately weighed. This piece will address the same.
Konark Bhandari