

Commentary
Yukon Huang, Isaac B. Kardon, Matt Sheehan
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [
    "Carnegie Oil Initiative"
  ],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}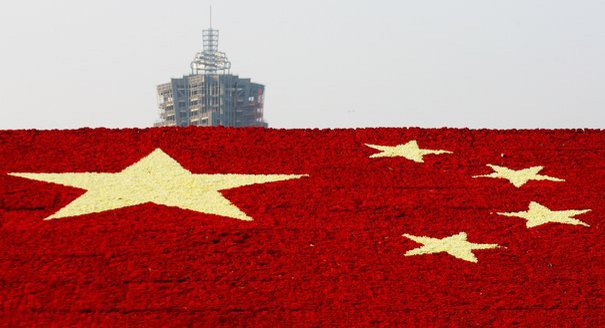
Source: Getty
China will become more "normal" in 2013, moving away from its unbalanced, unsustainable, and uncoordinated economic structure. However, this will make China more susceptible to business cycles and could undermine its current authoritarian model.
Source: Financial Times

China was an abnormal economy with its state-led capitalist approach that produced double-digit growth rates, no major financial crises and average wage increases of 12 per cent annually for decades. But the drivers of this impressive economic transformation will no longer be available to the new leadership. Beijing cannot simply open the monetary floodgates to stimulate the economy as was done in previous downturns.
Rates of growth in the 7-8 per cent range will become the norm and the key question is whether growth will be of higher quality – more balanced, sustainable and coordinated?China is in fact already rebalancing – internally, externally and spatially. Internally, if consumption continues to increase at 9 per cent annually and investment growth declines from over 15 per cent to 6-7 per cent, the consumption and investment shares of the economy will become more “normal”. Externally, the current account balance will also continue to moderate as domestic demand increases with urbanisation and investors diversify by shifting more of their funds abroad. China will also become spatially more balanced as the interior will grow much faster than the coast and urbanisation will accelerate.
China’s growth can also be more financially and environmentally sustainable with further reforms. Actions to strengthen the banking sector are already underway but its fiscal system needs to be transformed to take on more responsibility for channeling resources. And China’s Five Year Plan provides a platform to achieve environmental sustainability by sharply increasing energy efficiency and curbing pollution.
In a normal market-driven economy, coordination is less about the state managing all key activities but more about strengthening its regulatory role to give the private sector room to spur innovation and efficiency.
But as a normal economy, China also becomes more vulnerable to business cycles. It can no longer maintain stability by controlling key economic prices such as interest and exchange rates and limiting capital movements. Its vested interests will be grounded less in the links between the Communist party and the state-owned banks and enterprises but as in the west China will become more vulnerable to private interests and “crony capitalism”.
Without state-led investment taking the lead, the economy will be susceptible to Keynesian risks of lack of demand. Corporate profits will be squeezed by higher interest rates and rising wages. Efficiency will be more important than capacity in the future.
Normality will also undermine the authoritarian nature of the old model which served China well when the priority was simply to push out more infrastructure investment and ensure that the requisite resources were available. China will now need a less heavy-handed administrative system that will promote entrepreneurship All this will call into question the existing governance system and may well prove to be the catalyst for far-reaching political reforms.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Yukon Huang, Isaac B. Kardon, Matt Sheehan
Yukon Huang, Genevieve Slosberg
After the chill in ties between 2020 and 2024 that brought India–China relations to their lowest point in several decades, the two countries have engaged each other afresh. This paper argues that there are predominantly four imperatives guiding India’s approach to China, and they exist in an order of priority.
Saheb Singh Chadha

This piece argues that India’s central challenge is not managing a single flashpoint but resolving the underlying tension between expansion and institutional coherency of the BRICS grouping.
Vrinda Sahai
On March 10, 2026, India’s Union Cabinet approved amendments to Press Note 3, a regulation that mandated government approval on all foreign direct investment (FDI) from countries sharing a land border with India. This amendment raises questions primarily about whether its stated benefits will materialize and if the risks have been adequately weighed. This piece will address the same.
Konark Bhandari
This piece examines India’s response to U.S. sanctions and tariffs, specifically assessing the immediate market consequences, such as alterations in import costs, and the broader strategic implications for India’s energy security and foreign policy orientation.
Vrinda Sahai
This paper examines the evolution of India-China economic ties from 2005 to 2025. It explores the impact of global events, bilateral political ties, and domestic policies on distinct spheres of the economic relationship.
Santosh Pai