

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
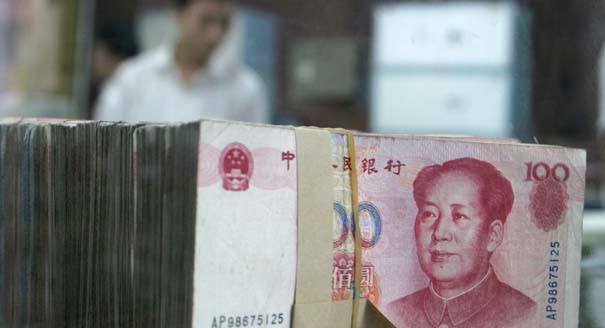
While China needs to revalue its currency to increase household income, it should do so gradually to avoid devastating its economy and hurting exporters and consumers alike.
Source: Bloomberg News

But the process was never going to be easy, and officials in Beijing were no more eager than other governments to make hard decisions when times were good. Now that times are bad, cooperation and forbearance are more necessary than ever. China simply can’t adjust fast enough to suit its trading partners.
Last week, Premier Wen Jiabao warned the world to stop pressuring China on the yuan. A rapid rise in the value of the currency, he said, was unacceptable because it could lead to massive unemployment and social instability.
“Europe shouldn’t join the choir to press China to allow more yuan appreciation,” Wen said in a speech at a meeting of business leaders in Brussels. “The euro had a big fluctuation recently. It’s not because of yuan but the dollars. We shouldn’t be blamed for it; if there’s someone to be questioned, it should be the U.S.”
Wen’s concern should have come as no surprise. Chinese economic growth is vulnerable to changes in the current-account surplus. A rapid strengthening of the yuan could easily cause a slowdown by throwing exporters into turmoil.
Some analysts dispute this claim, arguing that because the trade surplus has accounted for less than 15 percent of China’s growth in the past decade, China can’t be considered trade-dependent. Few policy makers in Beijing would agree.
Brutal Experience
And they are right not to agree. The rapid contraction in China’s trade surplus in 2008 was a brutal experience. Although official gross-domestic-product figures understate the impact, private-sector estimates suggest GDP growth dropped from more than 10 percent in the first quarter of 2008 to close to zero a year later, before rebounding to more than 10 percent again in the first quarter of 2010.
This is an extraordinary amount of volatility, even for a developing country. Clearly the collapse in international trade had a big impact on Chinese growth. What’s more, in order for growth to rebound so sharply, Beijing had to engineer one of the biggest investment sprees in history.
Credit in 2009 was forced to grow by almost one-third of China’s GDP, most of which went to fuel spending in real-estate development, manufacturing and infrastructure. An unprecedented surge in investment, in other words, was needed to counter the effect of a contraction in the trade surplus.
Low Consumption
Given that China entered the crisis with perhaps the highest investment level ever recorded, it’s not hard to see why Wen is concerned. With household consumption at an astonishingly low 36 percent of GDP, a rising trade surplus and expanding investment are the main sources of China’s growth. But China is so over-reliant on investment that many say, correctly, that it already invests far too much for its level of development.
The most sustainable way of rebalancing is to engineer an increase in household consumption. Rather than lag GDP growth by two or three percentage points, as it has for the past decade, household consumption must grow faster than GDP by at least three to four percentage points for the next several years for China to achieve any meaningful rebalancing of its economy.
But raising consumption has proven difficult. China depends on constraining consumption to boost manufacturing, and it will prove impossible to increase consumption at anywhere near an acceptable rate without restraining growth dramatically or restructuring its economy. It would require that China reverse a series of transfers from households toward investment and manufacturing, whose growth would slow without such a move.
Slow and Steady
So China is in a tough position. It must revalue the currency to increase the real value of household income relative to GDP (by reducing the price of imports). This would boost household consumption at the expense of exports. If it revalues slowly, the rebalancing can occur smoothly -- Chinese manufacturers would gain domestic clients as quickly as they lose foreign ones -- and unemployment would be limited.
But if China revalues too quickly, the rebalancing will be more brutal. Exporters would be forced into bankruptcy or into moving abroad, and as Chinese workers lose their jobs, aggregate household income, and with it consumption, would decline.
In that case, Chinese manufacturers would lose customers both abroad, because of the rising yuan, and at home, because of fired workers. China’s rebalancing would then occur in the form of weak consumption matched by even slower growth in production.
There’s the rub. If a too-rapid rise in the yuan causes a rapid contraction in China’s trade surplus, China must either permit a big decline in GDP growth, or it must boost investment even further, running the risk that a larger share than ever is misallocated and wasted.
Ideally, China should spend the next eight to 10 years slowly raising the value of the yuan while boosting wages and interest rates, and limiting credit growth. It can’t do any of these things too quickly without undermining growth and causing unemployment to surge.
The rest of the world just has to be patient.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
China’s political future will be shaped between now and next October. As the Communist Party enters its intense “campaign season” to prepare for a major political transition in 2027, reading Beijing's actions and responses may become more difficult as domestic politics weigh on its behavior more than usual.
Damien Ma
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
Tong Zhao
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis