

Q&A
- +1
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
There is an increasingly conducive environment for China to develop a more flexible exchange rate system, where the prospect of a decline in the value of the renminbi is the same as of an increase.
Source: Financial Times

While attention is focused on the value of the renminbi, more important for China is to promote greater flexibility, as I have previously argued. The challenge has always been finding the right opportunity. A pre-ordained nominal appreciation of three to six per cent annually only encourages speculative capital inflows. Thus the recent build-up in the country’s reserves has come as much from money pouring in as from trade surpluses. China must find a way out of this dilemma.
Although the global economy has deteriorated, paradoxically, conditions are better than a year ago for moving to a more flexible exchange rate system. A prolonged and volatile slowdown in global economic activity from the eurozone crisis, coupled with a sluggish US recovery, is now likely. With China’s key export markets under stress, its trade surplus will decline to about 1.5 per cent of gross domestic product this year from around five or six per cent several years ago. Coupled with recent efforts to liberalise imports, China’s trade surplus may soon evaporate. If so, fluctuations in China’s $3,200bn of reserves will be shaped largely by capital movements and currency valuations since most of its holdings are denominated in US dollars and the euro.
Recent moves to discourage property speculation, declining domestic economic growth, and signs that Chinese firms and individuals are investing more abroad, net capital inflows are likely to shrink, thereby reducing pressures for the renminbi to appreciate.
These dynamics are already showing up in the offshore renminbi markets where the trading premium points toward further depreciation. Similarly, the central bank has had to prop up the renminbi in the official market over the past week lest it decline even more than it has. Other east Asian currencies have become more volatile in recent months and on balance have depreciated significantly. Given the strong interlinkages in regional currency movements due to their shared production network, China will also be pulled into greater flexibility. And since inflation in China will remain relatively higher than its key western trading partners, its real exchange rate may appreciate marginally even if nominal rates decline.
All this will create a conducive environment for China to develop a more flexible exchange rate system where the prospect of a decline is the same as of an increase – as it should be.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Yukon Huang, Isaac B. Kardon, Matt Sheehan
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
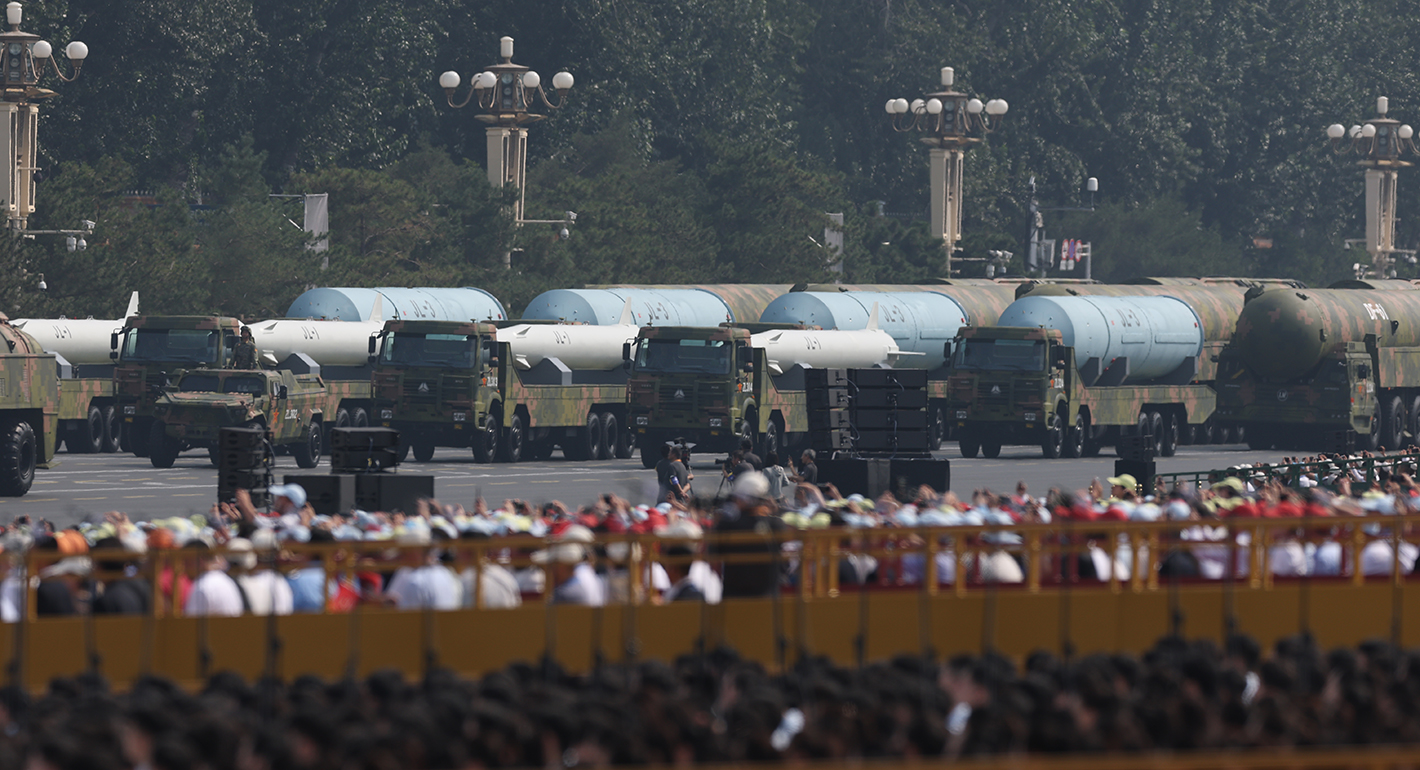
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis
Chinese biotech companies have been on the receiving end of U.S. economic coercion. Yet their responses have differed significantly because firm and state interests are not uniformly aligned. For Washington, treating all Chinese tech firms the same, irrespective of their actual interests, risks pushing them farther into Beijing’s corner.
Xue Gong
China’s latest energy plan explicitly calls for integrating data centers into the electricity system, particularly connecting them to green energy. It appears Beijing wants to use compute as a source of domestic demand to absorb renewables excess capacity.
Damien Ma