

Commentary
Uri Dadush
{
  "authors": [
    "Uri Dadush"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "South America",
    "South Asia",
    "East Asia",
    "North America"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
Over the past 20 years, emerging economies have not only grown faster than advanced countries, but outperformed market expectations--leading to significant returns on investment. Whether this will be the case in the future remains to be seen.
Source: Il Espresso

On the face of it, the reason for the extraordinary outperformance of emerging market equities is clear: growth. Over the last 20 years, emerging market GDP grew by 5.1 percent a year while advanced countries grew by only 2.2 percent a year, and this was broadly reflected in corporate earnings.
But wait, it is not so simple. After all, financial markets are supposed to be forward-looking, and the fact that emerging markets would grow faster was no secret even in 1992 (when, by the way, I first took on the task of forecasting emerging markets at the World Bank). Why didn’t markets reflect widely-held expectations that companies in emerging markets would grow faster in the price of their equities? A possible answer is that markets could not be sure that growth would be so rapid (in fact emerging economies and stock markets are more volatile than in advanced countries), so they priced the emerging equities at a discount. Moreover, in recent years they have kept getting surprised by the strong economic performance of emerging markets; in fact, at around 6.3 percent a year over the last five and ten years, emerging market growth outstripped most forecasts.So, will emerging markets outperform advanced countries again in coming years? They are certainly expected to continue to grow faster. The World Bank’s latest forecast, for example, projects 5.7 percent GDP growth through 2013 for emerging and developing economies, compared to 1.7 percent in advanced economies, an even wider difference than in the past.
But are markets already pricing in these expectations? In fact, markets continue to discount emerging markets, though less than they used to. They should be pricing a dollar of earnings in emerging markets higher than in advanced countries because the latter are expected to grow less rapidly, but they are doing the opposite, valuing advanced country stocks at 12.6 times earnings and emerging market stocks at 10.4 times earnings. This means that if the growth projections by the World Bank are realized, and this is reflected in profits, you will do much better investing in emerging markets than in advanced countries (about 6% a year higher return, in fact). But that also assumes that the relative valuation of emerging market and advanced country earnings will not change, which leads to the second question: will markets be surprised again by rapid growth in emerging markets in coming years?
If I knew the answer to that question, I would be very, very rich. There is little doubt that emerging markets, which have young and rapidly growing populations and are absorbing advanced technologies, will grow rapidly over the very long run. But here are four reasons the next five or ten years could bring some disappointment. First, growth expectations have never been higher, raising the bar. Moreover, many emerging markets (Russia, Indonesia, Argentina for example) have done well from commodity exports, and history teaches that record high prices of commodities will, sooner or later, lead to a big expansion in supply and new technologies that will reduce any shortage. Third, record low interest rates and lack of confidence in advanced countries, which have encouraged investment to emerging markets and caused their currencies to appreciate, will not persist forever. Finally, several emerging markets are already showing signs of macroeconomic imbalances and misallocated investment (Brazil, Turkey, China) or loss of reform momentum (India).
Still, the long-term growth prospects of emerging markets are so strong and current valuations are attractive enough that if you are 40 years old and investing for your old-age, you will still likely do very well by putting a good share of it in emerging markets rather than in slow-growing and fiscally-challenged advanced countries.
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Recent Work
Uri Dadush
Uri Dadush
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
China’s political future will be shaped between now and next October. As the Communist Party enters its intense “campaign season” to prepare for a major political transition in 2027, reading Beijing's actions and responses may become more difficult as domestic politics weigh on its behavior more than usual.
Damien Ma
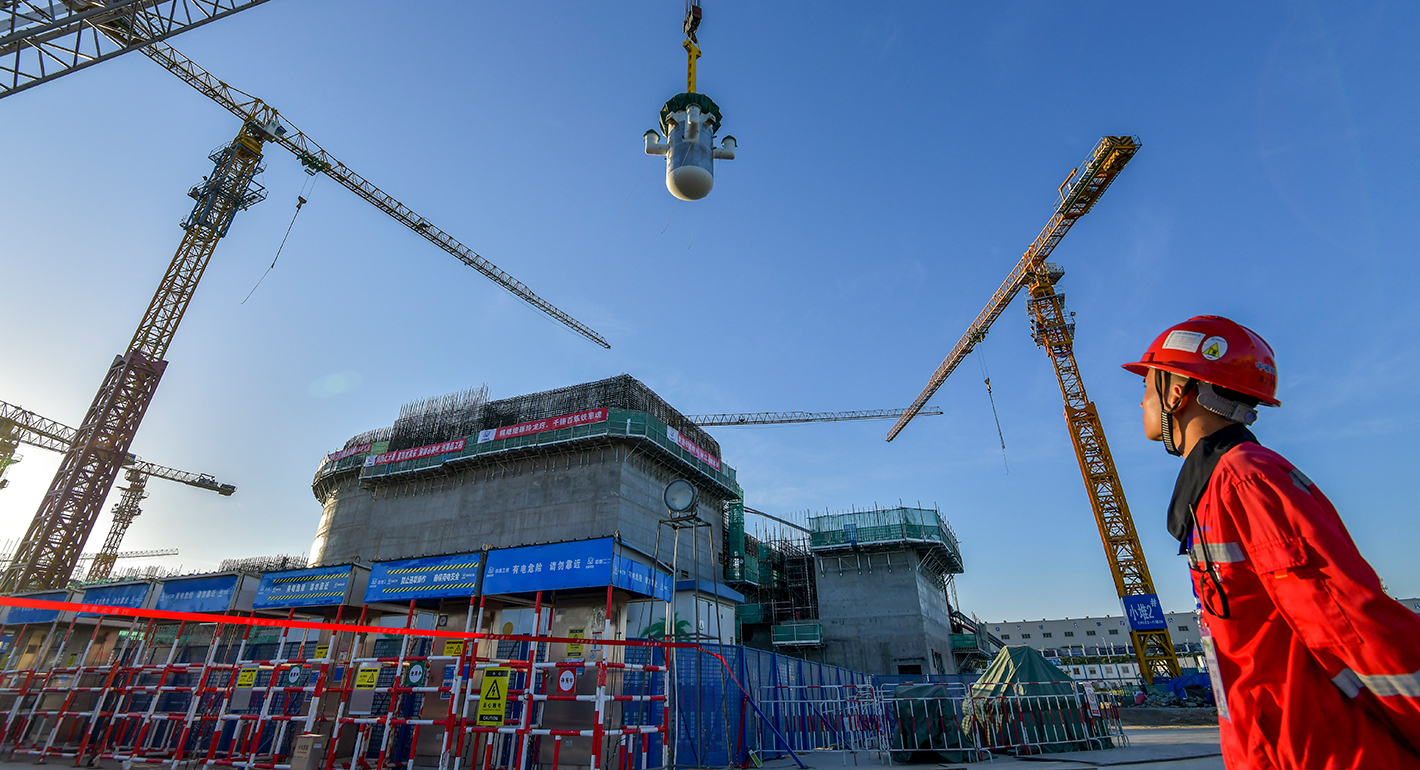
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
Tong Zhao
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis