

Q&A
- +1
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}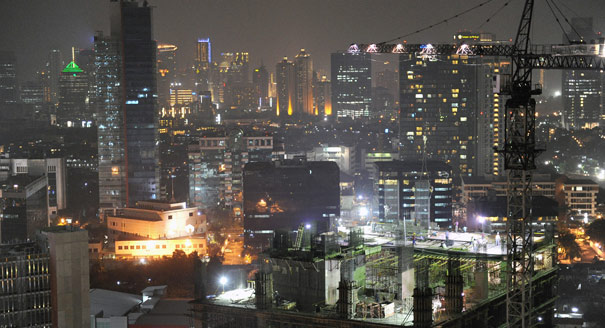
Source: Getty
If China hopes to maintain growth of 7.5 percent, it must improve the efficiency of its urbanization process and allow the private sector to play a more prominent role
Source: Wall Street Journal
Markets are so fixated on China's growth rate that President Xi Jinping recently had to provide assurances that it would not fall below the target of 7.5% this year. But the real worry is that China is gravitating toward an underlying "structural" growth rate closer to 6%. The country's sustainable growth trajectory is now so much lower because of a confluence of forces that can only be reversed by ratcheting up productivity.
China's run of more than 10% annual growth since 2003 was driven by three factors, two of which are no longer in force.
The first factor was rapid expansion in employment, which contributed about one to two percentage points to annual growth. The Chinese labor force is already shrinking as a result of demographic trends, so employment will play an increasingly marginal role in the future.The second factor was an investment boom that led to more capital being available per worker. This contributed slightly more than four percentage points to annual growth. However, as a result of the 2009 stimulus's considerable waste, China can no longer rely on rising investment to increase productivity. Between a shrinking labor force and the declining efficiency of investment, China's underlying growth rate is now three to four percentage points below its historic average.
The final factor, by contrast, is more promising as a driver of future development: The remaining four to five percentage points of China's growth were due to what economists refer to as growth in total factor productivity, or gains that come from the more efficient use of labor and other resources.
Increases in China's total factor productivity have been well above the international norm, coming mostly from the transfer of workers from agriculture to more productive industrial jobs. However, these gains have also fallen in recent years. So the challenge for Beijing is restarting TFP increases so that the economy can grow at a sustainable rate of 7% to 8% over the coming decade.
Two areas of reform could generate the needed gains: improving the efficiency of the urbanization process and allowing the private sector to play a more prominent role.
TFP increases that came from urbanization have been declining in recent years due to waste from the excessive conversion of agricultural land for urban use by local authorities. This has prevented China from fully reaping the so-called "agglomeration economies" or productivity benefits that come from concentrating workers and activities. The consequence instead has been urban sprawl, property bubbles and "ghost cities."
The gains from migration have also declined because China's unique residency restrictions inhibit workers from relocating to the most productive jobs. Without formal residency status, they are marginalized and ineligible for many social services. Smaller cities are more inclined to grant them such status but the larger cities, where productivity gains are greater, are less receptive.
A more efficient urbanization process would promote denser settlement patterns and allow market forces to shape growth in China's mega-cities rather than artificially spreading out development. But the process cannot succeed without allowing farmers to cash in their land-use rights, which would provide the nest egg needed to resettle in more dynamic but costlier urban centers.
Such reforms would help capture the large differences between the productivity of workers in rural areas and their urban counterparts. Although China has been urbanizing rapidly, 52% of Chinese currently live in cities, which suggests that potential productivity gains are still substantial.
Allowing the private sector to play a more prominent role has been a recurring theme for decades, but the case for doing so has never been as strong as now. Productivity differences between private and state firms did not matter as much when returns on assets began to increase steadily and converge a decade ago from rates around 2% for state firms and 4% for private. But they have now begun to diverge again.
On the eve of the financial crisis in 2007, the rates of return for state and private firms had risen to around 7% and 8% respectively, with the gap narrowing to only 1%. While both cohorts took a hit during the crisis, rates for private firms have since rebounded sharply and are now around 11%. For state firms, rates have fallen to 4%-5%.
This divergence is also mirrored in the buildup of debt following the global crisis, which severely affected state firms. A recent study by GK Dragonomics shows that the debt-to-profit ratio of listed private firms is 5% lower now than in 2008, whereas for listed state-owned firms it is 33% higher.
Reforms that call for leveling the playing field between state and private firms will not solve this problem. Nor will help come from the recent decision to eliminate the floor for lending rates, since this will only benefit state enterprises that have preferential access to financing. Bolder policy actions—such as getting the state out of a range of commercial activities and opening up other areas for private entry—must be part of the productivity-boosting agenda.
Many of the reforms undertaken so far, including simplifying investment procedures and liberalizing capital movements, will help. But unless Beijing shows a willingness to tackle major structural distortions that warp incentives, the economy cannot realize the efficiency increases it needs for sustained rapid growth.
This article was originally published by the Wall Street Journal
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Yukon Huang, Isaac B. Kardon, Matt Sheehan
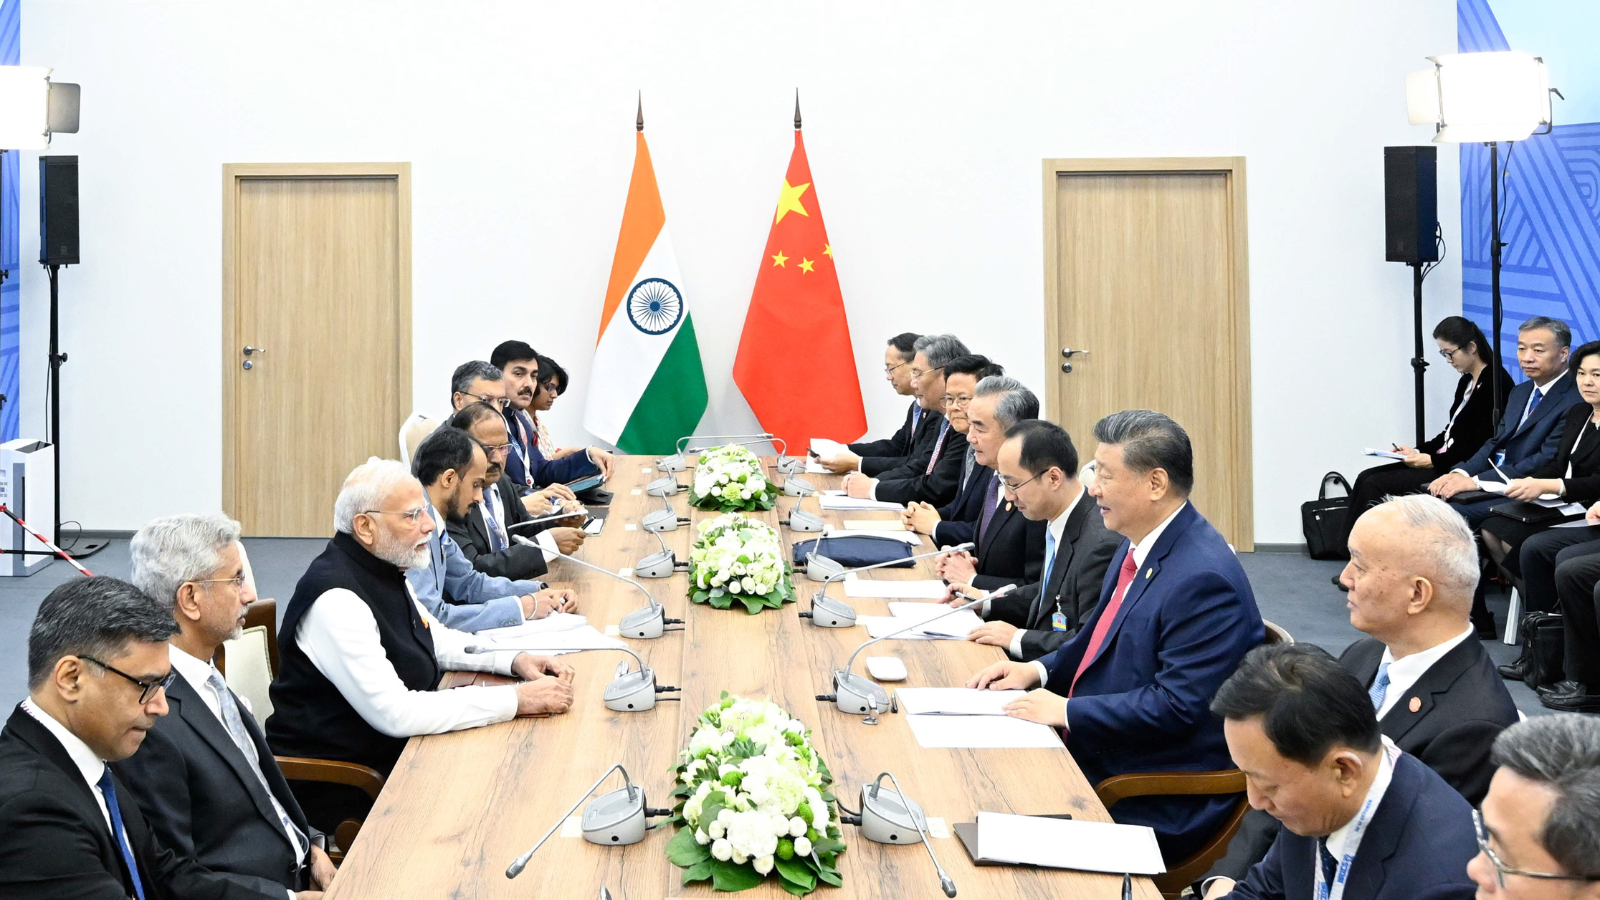
After the chill in ties between 2020 and 2024 that brought India–China relations to their lowest point in several decades, the two countries have engaged each other afresh. This paper argues that there are predominantly four imperatives guiding India’s approach to China, and they exist in an order of priority.
Saheb Singh Chadha

This piece argues that India’s central challenge is not managing a single flashpoint but resolving the underlying tension between expansion and institutional coherency of the BRICS grouping.
Vrinda Sahai
On March 10, 2026, India’s Union Cabinet approved amendments to Press Note 3, a regulation that mandated government approval on all foreign direct investment (FDI) from countries sharing a land border with India. This amendment raises questions primarily about whether its stated benefits will materialize and if the risks have been adequately weighed. This piece will address the same.
Konark Bhandari
This piece examines India’s response to U.S. sanctions and tariffs, specifically assessing the immediate market consequences, such as alterations in import costs, and the broader strategic implications for India’s energy security and foreign policy orientation.
Vrinda Sahai
This paper examines the evolution of India-China economic ties from 2005 to 2025. It explores the impact of global events, bilateral political ties, and domestic policies on distinct spheres of the economic relationship.
Santosh Pai