

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
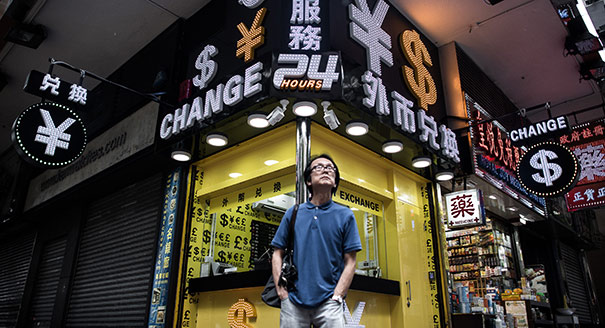
Devaluing the yuan may help Beijing achieve some policy goals, but the move won’t be so welcome in the global economy.
Source: Wall Street Journal
The People’s Bank of China shocked global markets Tuesday by devaluing the yuan 1.9% against the U.S. dollar. It also announced a potentially important change in the way it sets the daily reference rate, which determines trading levels in the onshore yuan market. This will now be set every day at a rate equal to “the closing rate of the inter-bank foreign exchange market on the previous day,” rather than wholly at the discretion of the central bank.
This devaluation tells us more about Beijing’s policy intentions than about any immediate boost to the economy. And it’s worth noting that the latter may be less than many expect.
There have been many calls over the past two years for devaluation. The People’s Bank, however, has been resistant, preferring a stronger currency as a means to increasing the purchasing power of household incomes and thus to help rebalance the Chinese economy. Observers have taken this as a sign of Beijing’s commitment to reform, a display of President Xi Jinping’s ability to overcome opposition by groups allied to state-owned enterprises, local governments and other “vested interests”—as they are called in China—who have long benefitted from China’s once-muscular growth policies.Yet there are at least two important justifications for a change in the currency regime.
First, because rebalancing the economy to make it more sustainable and less dependent on credit will cause growth to slow significantly, a strong export sector boosted by a weaker yuan might minimize any negative impact on Chinese unemployment. The most recent trade numbers, which showed that both exports and imports declined by more than 8% over the past year, were probably worrying enough to have finally tipped the scales in favor of devaluation.
Second, Beijing’s decision may have been affected by its eagerness for the International Monetary Fund to add the yuan to its basket of four reserve currencies. By reducing the discretionary role of the central bank in setting the reference rate, Beijing hopes to make the currency more market-driven, in line with IMF expectations. Were the yuan to join the IMF reserve basket without changes to its currency policy, the U.S. dollar’s already-excessive weight in the basket would increase—which is the opposite of what the IMF wants.
Against these potential benefits, Beijing also faces substantial risks. Rather than reverse net investment outflows, a credible change in the currency regime could accelerate them. Wealthy Chinese are behind a massive outflow of capital, and if they believe there is now a higher risk of depreciation, they may convert even more of their wealth into foreign assets.
But while many analysts believe a weaker currency will strengthen the Chinese economy by boosting exports, there are reasons to doubt that the external sector will provide much relief. For one, Beijing’s announcement could backfire if instead of boosting exports it sets off another round of currency wars.
More importantly, while global trade grew three times faster than global economic output between 1950 and 2010, it has since slowed dramatically and this year even turned negative. This has been made all the worse as Europe has attempted to resolve domestic imbalances by imposing austerity and boosting competitiveness.
Both measures work mainly by reducing household income (directly or indirectly), which reduces consumption and the private-sector investment that serves consumers. In other words, rather than resolve the problems of weak demand, European policy makers have simply forced them abroad.
Japan, too, is unlikely to provide much relief as it struggles to increase growth rapidly enough to bring its debt under control. It may already be too late. With such high Japanese debt levels imposing rigid spending constraints, perhaps only a surge in external demand could possibly help Japan grow.
For the past two years the impact of surging trade surpluses in Europe and (to a lesser extent) in China has been disguised by the collapse in global commodity prices. As a counterbalance to the rising surpluses, countries like Australia, Brazil, Chile, Venezuela and other commodity producers have seen their own surpluses collapse or their deficits surge. This cannot continue much longer without causing major dislocations.
In many cases, commodity prices have dropped by more than 50%, and many commodity-producing countries are already struggling with external debt. This means it is impossible for them to continue paying for high trade surpluses elsewhere.
But if they cannot do so, the surpluses must be absorbed elsewhere or they themselves will collapse. The only alternative is the United States, and if foreign investors increasingly pile into U.S. assets, the U.S. current-account deficit must rise in step with net capital inflows. If such deficits derail a U.S. recovery, or if the U.S. moves to protect domestic markets, then surplus countries will run out of places against which to run surpluses, and their surpluses will contract, either because of a debt-fuelled surge in investment or consumption, which is unsustainable, or because of a surge in unemployment.
Ultimately what matters most is how China’s surprise announcement affects Beijing’s credibility. Even if the yuan were to depreciate a lot further, China will find it increasingly difficult to wring growth out of stronger exports. With an election in the U.S. looming, and with commodity producers no longer counterbalancing weak demand in the rest of the world, the global environment is set to become a lot more acrimonious.
This article was originally published in the Wall Street Journal.

Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
After the chill in ties between 2020 and 2024 that brought India–China relations to their lowest point in several decades, the two countries have engaged each other afresh. This paper argues that there are predominantly four imperatives guiding India’s approach to China, and they exist in an order of priority.
Saheb Singh Chadha

This piece argues that India’s central challenge is not managing a single flashpoint but resolving the underlying tension between expansion and institutional coherency of the BRICS grouping.
Vrinda Sahai
On March 10, 2026, India’s Union Cabinet approved amendments to Press Note 3, a regulation that mandated government approval on all foreign direct investment (FDI) from countries sharing a land border with India. This amendment raises questions primarily about whether its stated benefits will materialize and if the risks have been adequately weighed. This piece will address the same.
Konark Bhandari
This piece examines India’s response to U.S. sanctions and tariffs, specifically assessing the immediate market consequences, such as alterations in import costs, and the broader strategic implications for India’s energy security and foreign policy orientation.
Vrinda Sahai
This paper examines the evolution of India-China economic ties from 2005 to 2025. It explores the impact of global events, bilateral political ties, and domestic policies on distinct spheres of the economic relationship.
Santosh Pai