

Commentary
Michael Pettis
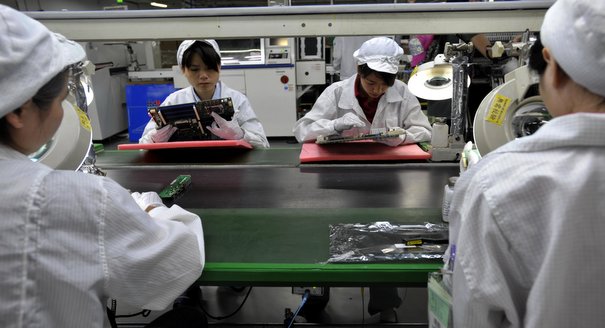
Source: Getty
In order to avoid deep economic imbalances, China will have to abandon its current development model and raise wages, interest rates, and the value of its currency.
The Chinese growth model is a muscular version of the Asian development model and shares fundamental features with other development strategies that generated periods of “miracle” growth, including Brazil in the 1960s and 1970s. While it can generate tremendous growth, it also leads inexorably to deep imbalances. China seems to have long passed the inflection point and may be on the verge of a very difficult transition into a different growth model.
At the heart of this model are subsidies for manufacturing and investment paid for by households. In some cases, as with Brazil in the 1960s and 1970s, the household costs are explicit—Brazil taxed household income heavily and invested the proceeds in manufacturing and infrastructure. The Asian variety relies on less explicit mechanisms to accomplish the same purpose.
The Asia model uses three primary mechanisms to ensure households pay for investment. First, wage growth is constrained to a level well below the growth in worker productivity, forcing workers to subsidize employers. Second, the exchange rate is undervalued. This reduces the real value of wages by raising import costs, while subsidizing manufacturers in the tradable goods sector.
Third—and most powerfully—is financial repression. Most savings in these countries are in the form of bank deposits, and the banks are controlled by the monetary authorities who determine the direction of credit, socialize the risks, and set lending and deposit rates.
Very low lending and deposit rates create a powerful mechanism for using household savings to boost growth by heavily subsidizing the cost of capital. In the case of China, every year an astonishing 5–10 percent of GDP is transferred from household savers to banks and borrowers in the form of repressed interest rates. And the low cost of capital explains the seeming paradox of China’s capital-intensive, rather than labor-intensive, growth—labor may be cheap, but capital is almost free.
The result of this enormously successful model is so much investment-driven and employment-generating growth that even with massive transfers from households, household income surges nonetheless. As China was clocking in growth rates of 10–12 percent annually for the past decade, household income, and with it household consumption, grew 8–9 percent annually.
But there are at least two constraints to this model. In early stages, when investment is low, the diversion of household wealth to invest in capacity and infrastructure will probably be economically productive. But the longer heavily-subsidized investment continues the more likely cheap capital and socialized credit risk funding economically wasteful projects. At some point, capital users begin to destroy wealth rather than create it, but nonetheless show profits by passing more than 100 percent of the losses onto households.
Second, policies that force households to subsidize growth are likely to generate much faster growth in production than consumption—increases in household consumption are largely a function of increases in household income. In that case, large and growing trade surpluses are needed to absorb the balance.
This is what happened in China over the past decade. And as long as the rest of the world—primarily the United States and the trade deficit countries in Europe—have been able to absorb rising trade surplus, the declining share of Chinese production absorbed by domestic households didn’t matter much.
But by 2007 China’s trade surplus as a share of global GDP had become the highest recorded in 100 years—perhaps ever—and the rest of the world found it increasing difficult to absorb the surplus. To make matters worse, the global financial crisis sharply reduced the ability and willingness of other countries to even maintain its current trade deficits.
China has hit both constraints—capital is wasted, perhaps on an unprecedented scale, and the world is finding it increasingly difficult to absorb excess Chinese capacity. For all its past success, China now needs to urgently abandon the development model.
The earlier China makes the change, the less painful the adjustment will be—but it will be difficult regardless. China must raise wages, interest rates, and the value of its currency, but if it does so quickly it could cause severe financial distress to businesses and projects heavily dependent on subsidized costs. And the resulting surge in unemployment could actually cause consumption to decline just as Chinese competitiveness abroad deteriorates. If it adjusts slowly, China will need other countries to accommodate the sluggish pace, but it is not at all clear that the rest of the world, and most importantly the United States and Europe, will allow their trade deficits to shrink so gradually.
The historical precedents for this kind of adjustment are not encouraging, and the steps China needs to take dwarfs those of its predecessors. Like it or not, China must change its growth model. And the speed with which it does so will affect global growth for many years.

Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
After the chill in ties between 2020 and 2024 that brought India–China relations to their lowest point in several decades, the two countries have engaged each other afresh. This paper argues that there are predominantly four imperatives guiding India’s approach to China, and they exist in an order of priority.
Saheb Singh Chadha

This piece argues that India’s central challenge is not managing a single flashpoint but resolving the underlying tension between expansion and institutional coherency of the BRICS grouping.
Vrinda Sahai
On March 10, 2026, India’s Union Cabinet approved amendments to Press Note 3, a regulation that mandated government approval on all foreign direct investment (FDI) from countries sharing a land border with India. This amendment raises questions primarily about whether its stated benefits will materialize and if the risks have been adequately weighed. This piece will address the same.
Konark Bhandari
This piece examines India’s response to U.S. sanctions and tariffs, specifically assessing the immediate market consequences, such as alterations in import costs, and the broader strategic implications for India’s energy security and foreign policy orientation.
Vrinda Sahai
This paper examines the evolution of India-China economic ties from 2005 to 2025. It explores the impact of global events, bilateral political ties, and domestic policies on distinct spheres of the economic relationship.
Santosh Pai