

Commentary
Uri Dadush
{
  "authors": [
    "Uri Dadush"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "Western Europe",
    "Europe"
  ],
  "topics": [
    "Economy",
    "Foreign Policy",
    "EU"
  ]
}
Source: Getty
Although the United States weathered the global recession relatively better than its European counterparts, it is not as strong as it looks and Europe’s long-term prospects are better than its current dismal performance suggests.
Source: L'Espresso
Now it’s official. According to the International Monetary Fund in coming years we will live in a three speed world: emerging markets surging, the United States recovering, and Europe languishing.
How come the United States, the home of Lehman brothers, is emerging from the gigantic financial crisis it originated while Europe still struggles with its after-shocks? The answer is that the US was able to count on smart policies, strong institutions, and good luck, and all three have regrettably been in short supply in Europe. But the US is not as strong as it looks, and Europe’s long-term prospects are better than its current dismal performance suggests.
The US, unlike Europe, was able to impart a large fiscal stimulus during the worst of the crisis and its monetary expansion was also very aggressive. American Federal Institutions, which don't exist in Europe, stepped in to save the banks without relying on the support of individual states, whereas countries such as Ireland and Spain had to foot their own enormous banking rescue bills and markets lost faith in their sovereign. In the US, highly flexible labor and housing markets adjusted very quickly to the collapse of demand through wage moderation and declining house prices, while banks quickly recognized their bad loans, restructured their balance sheet and are now lending again. In Europe all these adjustments are taking much longer.
Whereas the European periphery became very uncompetitive in the wake of the post-Euro boom, American unit labor costs fell steadily compared to trading partners over the last two decades at least, a result of fairly rapid productivity growth, falling real wages, and a relatively weak US dollar. So export expansion and import compression have helped reignite American growth, but have been a far less visible force in most of Europe (Germany being a notable exception). Luck helps the strong, as the saying goes, and the US is now also enjoying a boom in production of unconventional oil and gas. New “fracking” technologies are expected to add several points of GDP to the US economy, further improve manufacturing competitiveness, and make the US self-sufficient in energy.
These strengths are being translated in improved confidence of US consumers and investors. After many years of postponement the demand for houses, cars, and many consumer durables, is surging again. House prices are rising, household debt levels are falling and people feel they can start spending again. The recent big and chaotic government budget cuts (the reversing of fiscal stimulus) do not seem to have dampened the optimism.
Does this mean that we can stop worrying about the US and lose hope in Europe? No and no. The massive American monetary expansion will not be easy to reverse when the time comes to do so. And very little has been done to address the US economy’s structural weaknesses. The extraordinarily costly and inefficient health care system, which absorbs about 8% more of US GDP than in Europe for worse health outcomes (the life expectancy of Americans is 3.4 years less than in Italy, for example) is the most important weakness by far. The savings rates of US households are among the lowest in the world, an important reason the US has a relatively low rate of investment and runs a chronic current account deficit. And the US has the highest rate of income inequality in the advanced countries, as well as a 15% poverty rate, big reasons behind the profound political divisions that are making its governance border on the dysfunctional.
Europe’s structural weaknesses also run deep, of course, mainly related to its half-built currency union and the rigidity of its labor and services markets. But the institutions needed at the centre of Europe are slowly being built, competitiveness is improving in much of the periphery (not in Italy, alas), and important reforms are happening in areas ranging from pension systems to labor markets.
Europe needs to move faster. If it does, one day we may find that the IMF’s three speed world was just a temporary phase, a bat of the eye lashes of economic history.
This article was originally published in L'Espresso.
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Recent Work
Uri Dadush
Uri Dadush
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
Japan’s long-term security policy is driven by concerns about China, and there is little appetite for (or interest in) pursuing a confrontation with Moscow.
James D.J. Brown
The truth of the strategic situation is that Europe and Russia are extremely unlikely to be able to “turn the page” on their confrontation within the next two decades.
Arkady Moshes
Without a ceasefire with Ukraine on attacking each other’s energy infrastructure—to which the Kremlin is unlikely to agree—the diesel agreement between Putin and Trump is largely for show, rather than representing a genuine increase in the volumes of Russian diesel on the global market.
Sergey Vakulenko
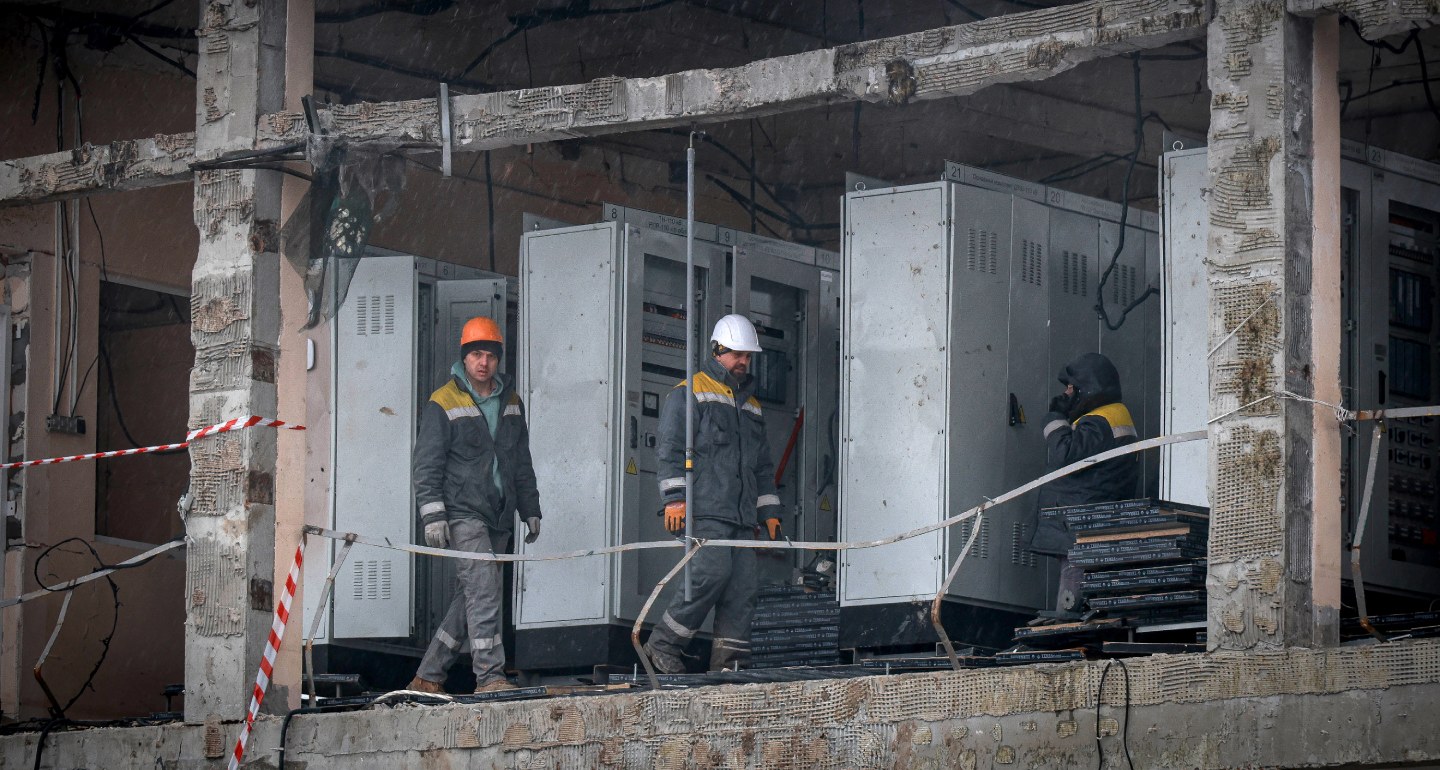
Russian strikes are weakening the economy sustaining Ukraine’s war effort. Closing the growing funding gap will require more European support and politically contentious reforms in Kyiv.
Balázs Jarábik
Despite a new textbook, an influx of Russian teachers and managers, and an end to the teaching of Ukrainian, the Kremlin is unlikely to have “reprogrammed” locals.
Konstantin Skorkin