

Q&A
- +1
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
China’s economic growth model, which relies on low interest rates to stimulate investment, resembles that of a large development bank. However, China's weak fiscal system threatens the sustainability of this model.
Source: China Daily

Which of the two is closer to the truth? Neither. But there is a way to interpret China's development that sheds some light on its economic approach. That model is the one used by multilateral development agencies, including the World Bank and the Asian Development Bank.
The World Bank aims to accelerate growth in developing countries, motivated by the conviction that the huge income disparities between high-income and emerging market countries are untenable. Not only do these disparities foster economic and trade tensions, but also political frictions emanate from civil strife and migration driven by despair as much as opportunity.
Developing sustainable solutions to these problems demands that developing countries grow more rapidly and in ways that preserve the global commons, from protecting the environment to making social services broadly available. Moreover, the actions of development banks encouraging growth is justified by market imperfections - which lie at the heart of underdevelopment - including limited information on risks and weak economic institutions that are unable to secure and allocate resources effectively.
The World Bank provides subsidized loans to developing countries that in turn lend the funds to local authorities and enterprises. Such assistance enables developing countries - whose fragile fiscal and banking systems do not give them access to commercial lending - to support investments with high social returns but whose risk-adjusted return is perceived by markets to be unacceptably low, such as social infrastructure.
The subsidies on the loans come from budget transfers or government guarantees that allow the World Bank to borrow in international capital markets on favorable terms because repayment of their loans is guaranteed - first, by the recipient governments and, second, by the bank's shareholding governments. Thus, despite skepticism of the viability of loans to countries as diverse as Sudan and Afghanistan, its financial soundness has rarely been questioned.
China's growth model resembles that of the World Bank: it relies on implicitly subsidized loans to catalyze growth and makes the low rates possible by reducing the incentives to consume and by providing sovereign guarantees. By keeping interest rates relatively low, China can tap the savings of households to subsidize lending. This represents a transfer from current consumption of households in favor of investment.
If these investments generate high returns, the economy grows faster than it would have otherwise, enabling China to maximize household consumption over time. In reality, personal consumption has been increasing at an impressive rate of 8-9 percent a year. Thus, because its subsidized investment has been so successful and may not have occurred otherwise, China represents a model that has arguably led to sustainably higher, not lower, consumption levels - contrary to the common perception.
This approach is not new. The Commission on Growth and Development, which assessed the experiences of a group of successful developing countries (including China), noted the importance of high investment and outward-oriented strategies in accelerating growth.
But the World Bank and China business models share certain risks. Because lending is subsidized and benefits are difficult to evaluate, the potential for waste is significant. For China, this means that curbing current consumption in favor of higher investment is sustainable only if it generates rapid growth.
Currently, China's fiscal system is inadequate to meet its needs. So the government relies on State-owned banks to channel additional resources to local authorities, agencies and enterprises for infrastructure and production purposes. Over time, however, China's fiscal system must develop, so that loans driven by government priorities and not purely commercial objectives can be transacted through budgetary channels instead of banks. Major reforms will be needed to raise and allocate the necessary revenue to turn "quasi-fiscal deficits" into line items in the budget to improve transparency and reduce risks.
Because China's major banks are State-owned, the soundness of China's financial system depends on the creditworthiness of the State (much like the World Bank's viability rests on the solidity of its sovereign guarantees). But the country's high savings rate, huge foreign reserves and low external debt ratios imply that a significant surge in bad loans is likely to lead to a controlled scaling back of lending rather than a financial collapse.
The key question is whether the quality of government-sponsored expenditures continues to justify the transfers from ordinary consumers - and, if so, for how long. For China, the pattern of above-norm increase in productivity, surging FDI inflows motivated by double-digit returns, and consistently high GDP growth has until now suggested that investments have been efficient in the aggregate. But recent claims about waste - as exemplified by China's high-speed railways program - suggest that leaders need to pay more attention to the efficiency of particular programs.
The World Bank, for example, has also experienced periods when excessive lending to countries with poor economic policies did not generate adequate returns, contributing to debt-servicing problems later. Its response was to tighten lending standards.
And, just as the World Bank and other development banks face scrutiny on the broader impact of their lending activities including its poverty and governance implications, China needs to consider the sustainability of its growth process. This includes its effect on the environment and internal equity, which senior leaders have recognized as key challenges facing the country.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Yukon Huang, Isaac B. Kardon, Matt Sheehan
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
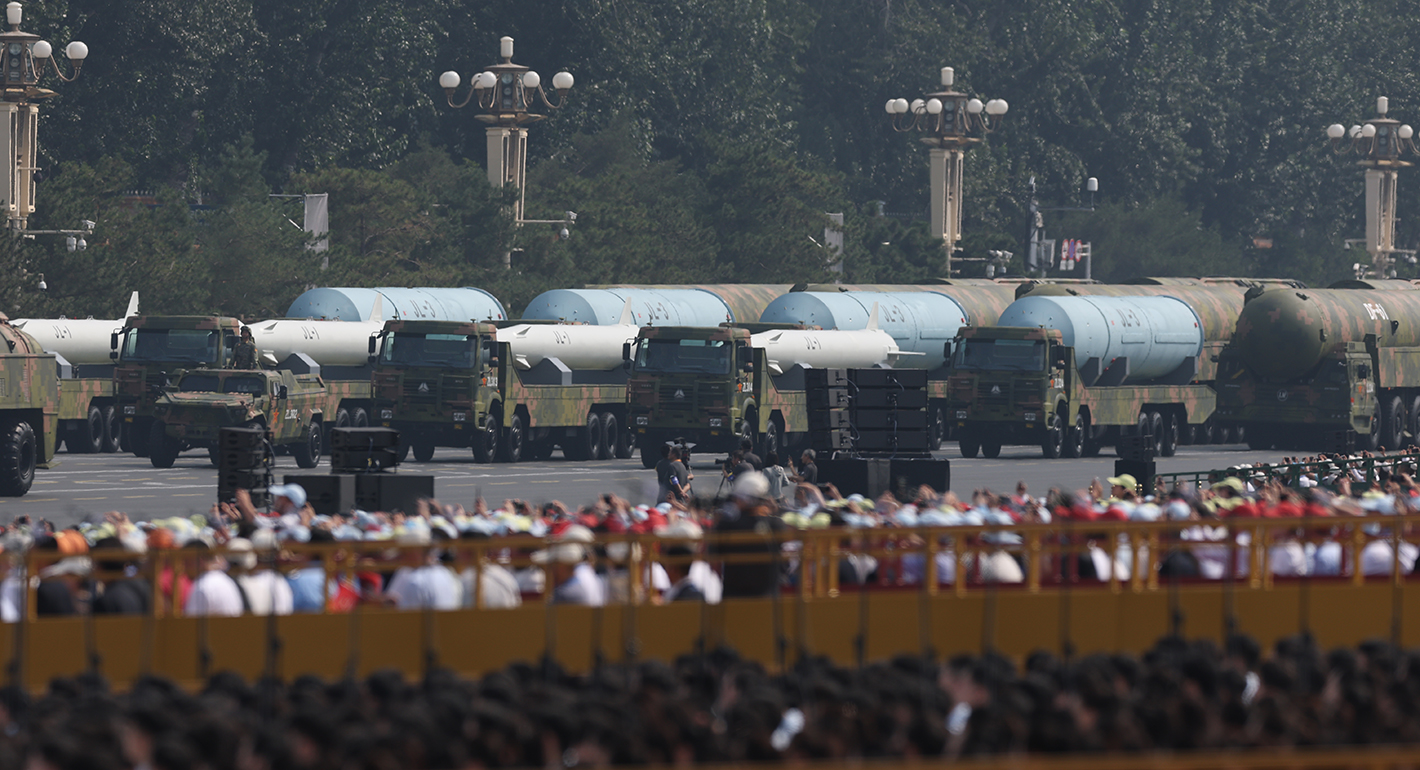
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis
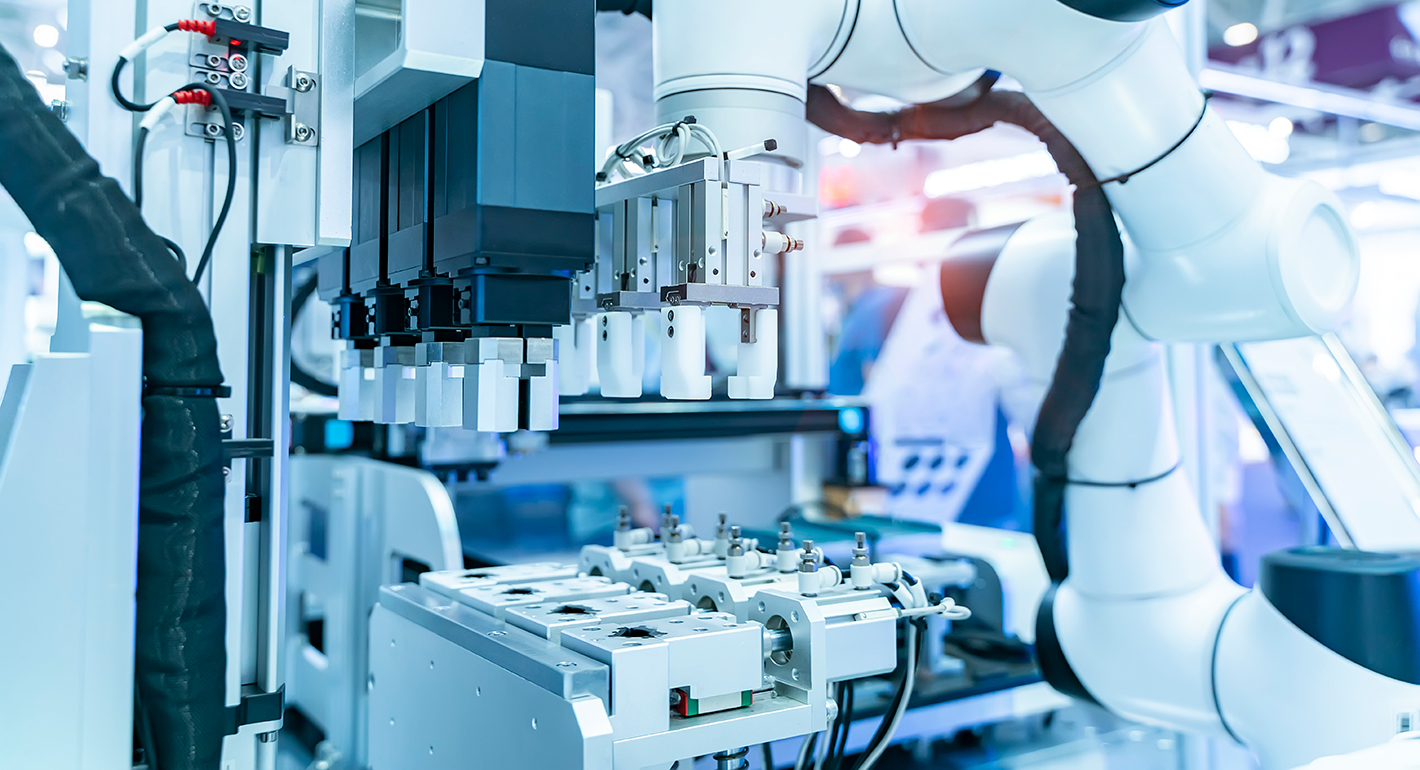
Chinese biotech companies have been on the receiving end of U.S. economic coercion. Yet their responses have differed significantly because firm and state interests are not uniformly aligned. For Washington, treating all Chinese tech firms the same, irrespective of their actual interests, risks pushing them farther into Beijing’s corner.
Xue Gong
China’s latest energy plan explicitly calls for integrating data centers into the electricity system, particularly connecting them to green energy. It appears Beijing wants to use compute as a source of domestic demand to absorb renewables excess capacity.
Damien Ma