• Commentary
  • Research
  • Experts
  • Events
Carnegie China logoCarnegie lettermark logo
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
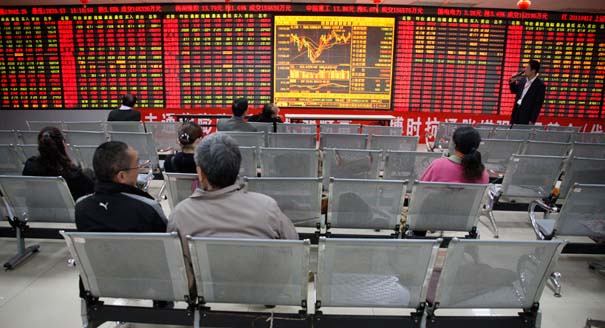
Source: Getty

In The Media
Carnegie China

The Real Risks to China's Financial System

Beijing has been using the financial system to fund public expenditure needs, many of which are not commercial in nature and would normally be undertaken through the budget.

Link Copied
By Yukon Huang
Published on Nov 17, 2011

Source: Financial Times

The Real Risks to China's Financial SystemThe recent assessment of China’s financial stability by the International Monetary Fund highlights increasing vulnerabilities stemming from the government’s role in the lending process, and an inflexible interest rate policy. Those who regard weaknesses in the banking sector as a likely trigger for a financial collapse have railed against China’s negative real interest rates and the speculative activity this has spawned. They see the heavy reliance on credit expansion to stimulate the economy during the global financial crises as eventually leading to a surge in non-performing loans. All this is viewed as part of a strategy of financial repression that postpones the day when China’s big four state banks can operate as real commercial banks.

But focusing on emerging financial risks is a case of treating the symptoms of the problem, rather than understanding and dealing with its origins. When Deng Xiaoping launched his efforts decades ago to boost economic growth, he needed to secure the resources to ramp up investments along the coast. But the Communist party leader faced the reality that government revenues had fallen to only 11 per cent of gross domestic product by the mid-1990s and the only alternative was to tap household savings in the banking system. Although revenues have been increasing steadily, China’s national budget still amounts to only 25 per cent of GDP, compared with an average of 35 per cent for other middle income countries and over 40 per cent for OECD economies.
With its responsibilities for providing a broad range of services for a mixed socialist economy, it is surprising how small China’s budgetary footprint actually is. Thus, Beijing has been using the financial system to fund public expenditure needs – many of which are not commercial in nature and would normally be undertaken through the budget. While this was unavoidable in the earlier years, it has turned out to be a politically attractive and effective option in dealing with the volatility of the global economy over the past decade. As such, these hidden banking losses are actually quasi-fiscal deficits, rather than traditional non-performing loans. While on paper China does not run major budgetary deficits, these quasi-fiscal deficits in the banking system have been accumulating over the years, awaiting the time (as in the past) when the non-performing loans are formally recognised and written off – with China’s substantial reserves and relatively low public debt ratios providing the cushion.
 
One cannot dispute that China needs to act on financial reforms, but the real challenge is for Beijing to recognise the importance of strengthening its fiscal system to undertake expenditure requirements in a more transparent and potentially less destabilising fashion. Unless the leadership takes this decision, admonitions for more flexible monetary policies and improved governance of key financial institutions will continue to fall on deaf ears.
 
Unfortunately the budgetary problems that have paralysed both the eurozone and US do not help the case. Beijing is watching with amazement as political leaders across both continents struggle to forge the consensus needed to strengthen their countrys’ fiscal positions. This only reinforces China’s view that budgetary processes are too politically cumbersome to deal with the unpredictable nature of the global economy. It makes it all the more likely that Beijing will continue to use the banking system for purposes that textbooks never saw as appropriate.

About the Author

Yukon Huang

Senior Fellow, Asia Program

Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.

    Recent Work
  • Q&A
    What to Watch When Trump and Xi Meet in Washington
      • Sheena Chestnut Greitens
      • Oriana Skylar Mastro's headshot
      • +1

      Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
  • Commentary
    Three Takeaways From the Biden-Xi Meeting

      Yukon Huang, Isaac B. Kardon, Matt Sheehan
Yukon Huang
Senior Fellow, Asia Program
Yukon Huang
EconomyEast AsiaChina

Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.

More Work from Carnegie China

  • Commentary
    The Spring and Autumn of Chinese Politics

    China’s political future will be shaped between now and next October. As the Communist Party enters its intense “campaign season” to prepare for a major political transition in 2027, reading Beijing's actions and responses may become more difficult as domestic politics weigh on its behavior more than usual.
      • Damien Ma

      Damien Ma

  • Article
    Can China Turn Its Small Modular Reactor Ambitions into Commercial Reality?

    China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
      Tong Zhao
  • Commentary
    China Financial Markets
    The Plaza Accord and Its Relevance for China

    The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
      Michael Pettis
  • The nuclear missile formation passes through Tian'anmen Square during a military parade on September 3, 2025 in Beijing, China.
    Paper
    Untangling the Nuclear Knot: A Constructive Agenda for Managing China’s Nuclear Relations with the United States and Its Allies

    The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.

      Tong Zhao

  • Commentary
    China Financial Markets
    Who Paid for China’s Last Debt Cleanup, and Who Will Pay for the Next?

    China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.

      Michael Pettis

Get more news and analysis from
Carnegie China
Carnegie China logo, white
Keck Seng Tower133 Cecil Street #10-01ASingapore, 069535Phone: +65 9650 7648
  • Research
  • About
  • Experts
  • Events
  • Contact
  • Careers
  • Privacy
  • For Media
Get more news and analysis from
Carnegie China
© 2026 Carnegie Endowment for International Peace. All rights reserved.