

Q&A
- +1
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Source: Getty
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
This article is part of “China's Nuclear Renaissance,” a Carnegie China series examining the opportunities and challenges China faces as it seeks to lead a new wave of nuclear energy innovation and development.
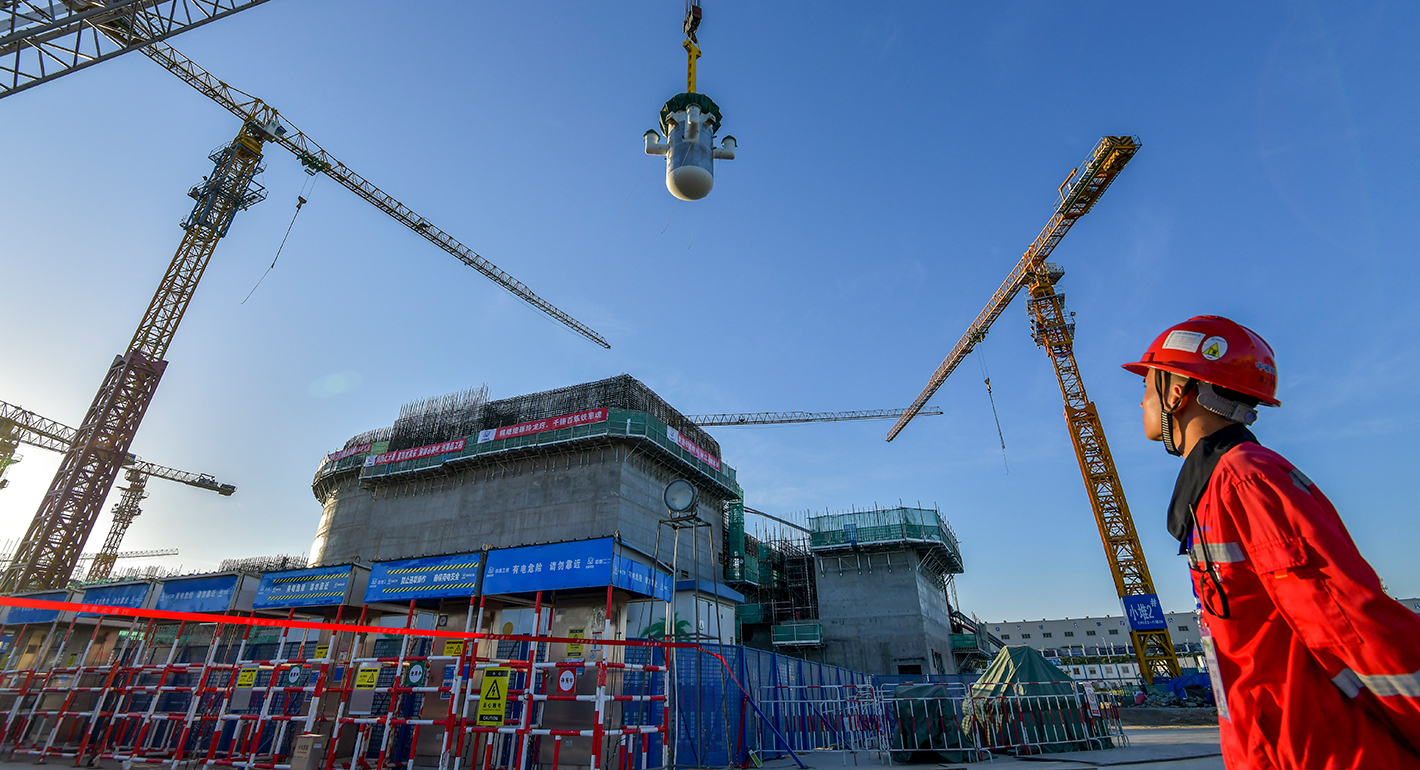
If it begins operation as expected by the end of 2026, the Linglong One reactor would become the world’s first commercial land-based small modular pressurized water reactor. Built in just over five years in Hainan province, the 125-megawatt electric (MWe) reactor is considered a feat of Chinese nuclear engineering and construction prowess.1 But is Linglong One merely a showpiece, a technology experiment, or does it foreshadow a broader shift in Chinese nuclear energy strategy?
With roughly half of the world’s reactors under construction in China, the country is on course to becoming the world’s largest nuclear power producer. China expects to surpass the United States in installed nuclear generating capacity by 2030. Given the scale and speed of nuclear deployment in China, Beijing may also drive nuclear power innovation with new reactor designs and applications.
Small modular reactors (SMRs) are one such innovation. These reactors range from 50–350 MWe in output, compared to modern standard nuclear power plants that produce 1,000+ MWe. In theory, SMRs can be manufactured assembly-line style to drive down unit cost. In other words, the hope is that nuclear power will become more compact and cheap with SMRs, making such systems readily deployable in different environments and markets.
As a potential SMR builder and exporter, China has important advantages, chiefly because it has achieved a high degree of indigenization in manufacturing major components of commercial reactors, including key reactor and primary-system equipment, and has become substantially more self-reliant in specialty materials, precision instruments, and software. Bottlenecks remain, however, notably in developing the specialized fuels required by some advanced SMR designs and in managing spent fuel.
Even as China has demonstrated that it can build first-of-a-kind (FOAK) SMRs, the outlook for commercialization remains far less certain. If China cannot turn the demonstration projects into standardized, repeatable, and economically competitive fleets, then the case for scaling up domestic SMR deployment will wear thin.
In the first of a series that examines the realities of the nuclear renaissance, this analysis focuses on China’s challenges in realizing SMRs’ potential. It evaluates Chinese SMRs’ economic competitiveness, market potential, regulatory maturity, supply chain completeness, and social acceptance. For the foreseeable future, the overseas market for Chinese SMRs will remain limited, and therefore unlikely to significantly alter their overall commercialization prospects. A subsequent analysis in this series, focused on China’s nuclear exports, will examine the international market in greater detail.
The United States remains technologically formidable, with one of the world’s most diverse and innovative portfolios of SMR concepts in various stages of development. China, by contrast, has prioritized consolidation and construction of large, grid-connected plants to power its growing industrial and consumer economy. While focusing in recent decades on improving and scaling up these gigawatt-scale systems, Beijing has also more recently adopted a careful and calibrated approach to SMR development, starting with demonstration projects like Linglong One.
For China, as for others, the cost of SMRs is likely to be a significant factor in their commercial and export viability. Chinese analysts expect the first wave of SMR deployment globally to begin around 2030.2 But that is contingent on whether manufacturing capacity will be in place and whether SMR’s cost curve can be bent downward, as China has done successfully with solar, electric vehicles, and batteries.
Due to their smaller size, SMRs will produce electricity that is estimated to roughly be 20 percent more expensive—usually measured in terms of the levelized cost of electricity—than conventional large reactors, according to Chinese experts.3 Linglong One, currently China’s most prominent SMR project, is reportedly up to twice as expensive to build per kilowatt of capacity as an average large pressurized-water reactor, and the electricity it produces is 50 percent more expensive.4 The project has also run into delays, which could push costs higher still. The high-temperature gas-cooled reactor project in Shandong Province experienced similar construction overruns and a reduction in nominal capacity for unspecified reasons. That project’s construction cost per kilowatt has been assessed at more than twice that produced by a Hualong One large reactor.5
It is tempting to dismiss these challenges as par for the course for FOAK projects. But the limited progress to date leaves much to be desired. Chinese experts recognize that to make SMRs genuinely modular for nth-of-a-kind (NOAK) deployment requires further simplification of systems and components, greater design standardization and factory fabrication, easier transportation, and faster on-site assembly.6 Reducing construction time and unit cost that will lead to repeat orders is the only viable path forward in developing a real market for SMRs, but significant progress remains elusive.
To improve the economic viability, government policy support in the form of financing and regulatory changes could give SMRs a boost. The absence of substantial targeted support so far suggests, however, that Beijing has yet to make the SMR industry a policy priority. In the meantime, state-backed financing is already subsidizing large reactors, making them cheaper and squeezing out potential cost advantages for SMRs. Unless a sizable market emerges in which SMRs offer distinct advantages, Beijing may remain reluctant to subsidize SMR deployment on a large scale. For now, policy support appears to remain limited to SMR technology development and demonstration.7
On the energy regulatory side, Beijing could reclassify nuclear power as renewables to include it in the Green Electricity Certificate system or make SMR projects eligible for the China Certified Emission Reduction (CCER) system. Either measure could raise project revenue, but both options face obstacles. For CCER in particular, no methodology exists for calculating emission reductions from SMR projects.
Instead, Beijing has been gradually reducing preferential tax treatment for nuclear power projects in general as the broader nuclear industry matures. A late 2025 policy, for example, eliminated refunding the value-added tax for newly approved reactors while phasing it out for projects already approved.8 Unless the government introduces new SMR-specific incentives, this trend could further weaken the inherent potential of the economies of scale for SMRs.
Setting aside cost challenges, the actual market for SMRs in China is uncertain. Unlike the United States, where the AI-energy thesis has prompted big technology companies to invest in SMRs as a long-term, clean option to power data centers,9 in China there does not appear to be similar interest or a perceived need for SMRs. Even as aggregate electricity demand continues to grow, China has been adding generation capacity in the form of coal, renewables, and conventional nuclear at an even faster clip. This has led to regional electricity surpluses and even production curtailment at some coal plants along with solar and wind farms.10
China’s highly developed and interconnected power grid further weakens one of the standard use cases for SMRs: bringing power to rural, remote areas that aren’t connected to main grids. But China’s extensive transmission network, including long-distance and ultra-high-voltage lines, allows electricity from various energy sources to be moved across regions relatively efficiently, including to remote areas. As a result, China’s grid often favors large generating facilities, including large nuclear reactors, whose output can be absorbed over broad areas while capturing greater economies of scale.
Herein lies a key paradox for SMRs: The indigenized technology and supply chains of China’s conventional nuclear fleet have allowed it to quickly develop SMRs, yet the tremendous success of China’s large nuclear plant build-out has crowded out potential use cases for SMRs. Seemingly what is left for SMRs are China’s hinterlands, but in these regions, nuclear will compete with the massive deployment of renewables that are already cheap. The renewables surplus is already driving Beijing to site more data centers in those regions under the “Eastern Data, Western Compute” (东数西算) initiative and the “green direct connection” (绿电直连) strategy.11
The most promising domestic market for Chinese SMRs may be industrial applications and residential uses, given their smaller size, potential to be sited closer to demand centers, and possible safety advantages. For instance, SMRs can combine the generation of electricity with the production of heat, steam, hydrogen, or desalinated water. With outputs typically in the range of a few hundred megawatts or less, SMRs may be better matched to the thermal needs of an industrial park than a gigawatt-scale large reactor. This could give SMRs a genuine “sweet spot” in the industrial energy market.
If SMRs can be sited close to chemical complexes or industrial parks, they could reduce the losses associated with transporting heat or steam over long distances from large reactors that generally require larger safety zones. Certain SMR technologies may be particularly well suited to such applications. The high-temperature gas-cooled reactor demonstration in Shandong, for example, can produce hotter steam than conventional large pressurized-water reactors, making it more suitable for some industrial processes. Similar logic could support combined district heating and electricity supply if SMRs can be located sufficiently close to residential areas.
That market proposition, however, depends not only on cost factors but also on whether SMRs can actually be deployed close to industrial users or population centers. This issue may be more political than technical in nature, depending on how Chinese nuclear regulators evaluate the safety credentials of these various designs.
China has begun adapting its nuclear safety rules to be more conducive to SMR deployment. New environmental radiation rules issued in 2025 removed the previous blanket requirement that nuclear power reactors be located at least 10 kilometers from towns or cities with populations of 100,000 or more, while also reducing the minimum planning-restricted-area boundary for SMRs from 5 kilometers to 1 kilometer.12
Actual restriction perimeters remain site-specific, but the differentiated and potentially much smaller siting envelope allows, in theory, for deployment closer to industrial users and population centers. What’s more, the smaller radioactive inventory and the passive safety features incorporated into many Generation III and Generation IV SMR designs can reduce the likelihood of severe accidents relative to older large-reactor designs.
Regulatory guidance, however, still lags. One challenge is the overlap between safety regimes in different industrial sectors. When an SMR is co-located with a chemical plant, for example, regulators must consider both how a chemical accident could threaten the reactor and how a reactor accident could affect the chemical facility. Nuclear sites and chemical plants are currently governed by different rules, including different safety-zone and security requirements, overseen by separate authorities.13 Joint risk assessments and integrated safety rules, while underdeveloped, are necessary for such coupled projects.
Even within the nuclear sector, the lack of clear, detailed, and executable rules covering the full process of planning, evaluating, approving, and managing SMRs remains a major obstacle to large-scale investment and deployment. This is largely a result of a regulatory dilemma common to new technologies: Regulatory uncertainty discourages investment and development; but because SMR technologies are not yet mature, regulators face limits on how far they can move ahead without more empirical evidence from their construction and deployment. This is observable with the National Nuclear Safety Administration issuing a limited set of “Technical Opinions” on SMR nuclear safety in August 2026.14 The document establishes useful high-level principles but stops short of the detailed licensing standards tailored to different reactor types.
Beyond economics and regulations, China still has critical gaps in parts of the SMR supply chain, particularly the industry-wide challenge of scaling up the production of specialized fuels and managing diverse forms of spent fuel as the industry converges on advanced technology choices for both large and small reactors.
Although China has limited domestic uranium resources, upstream access to uranium supplies isn’t likely to be a major challenge. China remains heavily dependent on imported uranium, but a portfolio combining expanded domestic production, stockpiling, Chinese control of overseas mines, and market purchases should keep supply for the nuclear sector broadly manageable through the 2040s and likely beyond.15
The challenge will be to meet fuel needs for advanced non-light-water reactor designs, which have been championed by the industry writ large. Some of these advanced designs, including a significant share of SMRs, require high-assay low-enriched uranium (HALEU) enriched to between 5 and 20 percent, whereas light-water reactors traditionally used low-enriched uranium containing less than 5 percent U-235. Although China already produces HALEU fuel for its high-temperature gas-cooled reactors, it still faces significant hurdles in scaling other HALEU fuel forms.
China will similarly face challenges in managing used fuels from a diverse range of SMRs. Many non-light-water reactors will require new technologies in order to reprocess their spent fuel. While China’s Atomic Energy Law, adopted in 2025, reaffirmed the country’s long-standing policy of developing a closed nuclear fuel cycle through reprocessing of spent fuel, its capabilities to deal with fuel from several advanced non-traditional reactor types remain technologically immature.
Physical security and public acceptance present additional challenges to SMR deployment. If SMRs are co-located with existing large nuclear plants, they can benefit from the relatively high-standard security systems already in place. But that defeats the purpose of SMRs, which are supposed to be standalone and geographically dispersed. Depending on the volume of SMRs, replicating existing security arrangements at every SMR site could be economically unviable. On the other hand, proximity to end users, especially residential districts, could also make public acceptance of SMRs more difficult than for large reactors located farther away from population centers.
In fact, China has experienced organized public opposition to nuclear power plants, which has delayed several proposed nuclear power projects across the country. In some cases, public opposition contributed to project cancellations.16 China’s political system may be better optimized than others to overcome NIMBYism, but that does not eliminate the problem of local distrust of nuclear facilities. Given Chinese authorities’ high sensitivity to any potential sources of social unrest, public opposition could still become a meaningful constraint on where SMRs can be built.
China’s SMR program has crossed the threshold from concept to demonstration, but it remains far from commercial viability. Over the next decade, China will need to prove it can transform FOAKs into NOAKs to realize SMRs’ potential. That means standardizing designs, identifying sufficiently large markets, scaling factory fabrication, driving down costs, and winning public trust along the way. At the same time, regulators must establish workable proximity-siting rules while fuel-cycle research and capabilities catch up with advanced reactor designs.
Here lies the paradox: Realizing cost reductions from modularization and scale requires volume, and volume requires a large addressable market. That market may be difficult to find domestically, where the commercial case for SMRs will likely remain selective and niche, focused on powering industrial heat and steam, district heating, desalination, and off-grid electricity.
For now, the potential of China’s SMR industry doesn’t match the reality. The road to commercialization will likely be an incremental process of, as the Chinese saying goes, “crossing the river by feeling the stones,” an approach that centers on experimentation and ad hoc deployment before leap to scale.
The author acknowledges LLM tools were used for preliminary proofreading. The writing, argument, and analysis are entirely the author’s own.
Senior Fellow with the Nuclear Policy Program and Carnegie China
Tong Zhao is a senior fellow with the Nuclear Policy Program and Carnegie China, Carnegie’s East Asia-based research center on contemporary China. Formerly based in Beijing, he now conducts research in Washington on strategic security issues.
Recent Work
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
The armed forces champion a form of capitalism that is generating revenue, but its reliance on rent faces diminishing returns, leaving the country with massive sunk costs and deferred returns, deepening dependency on external borrowing.
Yezid Sayigh
In an interview, Marc Lynch discusses his new book decrying the post-1990 U.S.-dominated order in the Middle East.
Michael Young
In an interview, Ishac Diwan looks at the merits and flaws in the draft legislation distributing losses from the financial collapse.
Michael Young
The GCC states’ use of Artificial Intelligence will generate much leverage over the global digital infrastructure and climate talks.
Camille Ammoun
Mustaqbal Misr has expanded its portfolio with remarkable speed, but a lack of transparency remains.
Yezid Sayigh