

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "East Asia",
    "China",
    "Japan",
    "Western Europe",
    "United Kingdom"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
Despite the raging criticism of the "Anglo-Saxon" financial model during the financial crisis, the funding of risk-taking entrepreneurs is crucial for wealth creation.
Source: Financial Times
Conventional wisdom has it that the financial crisis originating in the US proves that the “Anglo-Saxon” financial model is too dangerous and too deeply flawed to have much to teach the rest of the world. If it were any good, after all, how could we have suffered the spectacular near-collapse of the US and UK banking systems?
But the prestige of the Anglo-Saxon financial system soared in the 1990s at least in part because the “other” main banking model seemed to have failed so spectacularly in the country that was long considered its greatest exponent.
In the 1980s Japanese banks funded one of the biggest stock and real estate bubbles of all time. Their reckless malinvestment is perhaps matched only by recent spending in China (whose banks, incidentally, share some characteristics with those of Japan).So must all financial systems fail? Hyman Minsky, one of the 20th century’s most brilliant – if underrated – economists, argued that it is not possible to design a crisis-proof financial system. Banks, after all, act as middlemen between savers, who value stability above all, and borrowers, who usually want to take risks with their loans. History suggests he was right. No growing economy has sustained a stable financial system. In fact, long-term wealth creation accrues most to societies in which the financial system most willingly funds risk-taking entrepreneurs. But the more a financial system is willing to finance risky new ventures, the greater the likelihood of banking instability.
That, perhaps, is why the system that delivered the subprime crisis also funded the computing and internet revolutions. The Belgian historian Raymond de Roover once explained that, in the 19th century, “reckless banking, while causing many losses to creditors, speeded up the economic development of the United States, while sound banking may have retarded the economic development of Canada”.
Too much financial stability, in other words, may actually reduce growth by limiting the transfer of resources to producers of wealth. This is not to say that all reckless banking is good. Certainly it is hard to see the value in the property boom and derivatives abuses of the American financial system in the past decade. Japan’s banks in the 1980s turned out to be reckless, too, in a way that is hard to justify economically over the long term.
In any case, we should not waste our time, Minsky would argue, trying to design a stable financial system that never runs into trouble. Any financial system, well designed or not, seems to respond to excess liquidity and low interest rates through malinvestment. Minsky had no faith in the ability of regulators to eliminate risk. All they could do was lessen the damage to the real economy through automatic countercyclical policies.
He argued, in fact, that the stability imposed by regulators is destabilising. Socialising losses when they become too large – which is ultimately the only way to stabilise a banking system – encourages ever-riskier behaviour. Banks respond to this type of stability by stepping up their risk-taking activity until, at some point, as in 2007-08, the distortions in the banks’ balance sheets are too big to prevent a crisis, and its economic impact cannot be easily counterbalanced.
Instead, we should design a financial system that, in “normal” times, intelligently allocates capital to wealth-creating businesses and government projects, even if it means periodic crises. We should allow localised – manageable – banking crises to occur more often.
So the American financial system post-crisis is, unfortunately, not what Minsky would have proposed. The US has a few large, universal institutions that control ever-greater shares of financial assets. He would, instead, have opted for a much more fragmented system with more moving parts that failed and were replaced as a matter of routine. Large banks prefer stability to rapid growth, and US banks are now so large that they can impose their preferences on to the US economy.
What might in fact be best for the US and the world may be more and smaller banks, tougher and even ruinous competition, more bankruptcies, more kinds of financial institutions and a regulator whose main function is to enforce transparency and to manage periodic crises with countercyclical measures. Perhaps then we might even prefer a little more 19th-century-style “reckless banking”.
This article was originally published in the Financial Times.

Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis
Chinese biotech companies have been on the receiving end of U.S. economic coercion. Yet their responses have differed significantly because firm and state interests are not uniformly aligned. For Washington, treating all Chinese tech firms the same, irrespective of their actual interests, risks pushing them farther into Beijing’s corner.
Xue Gong
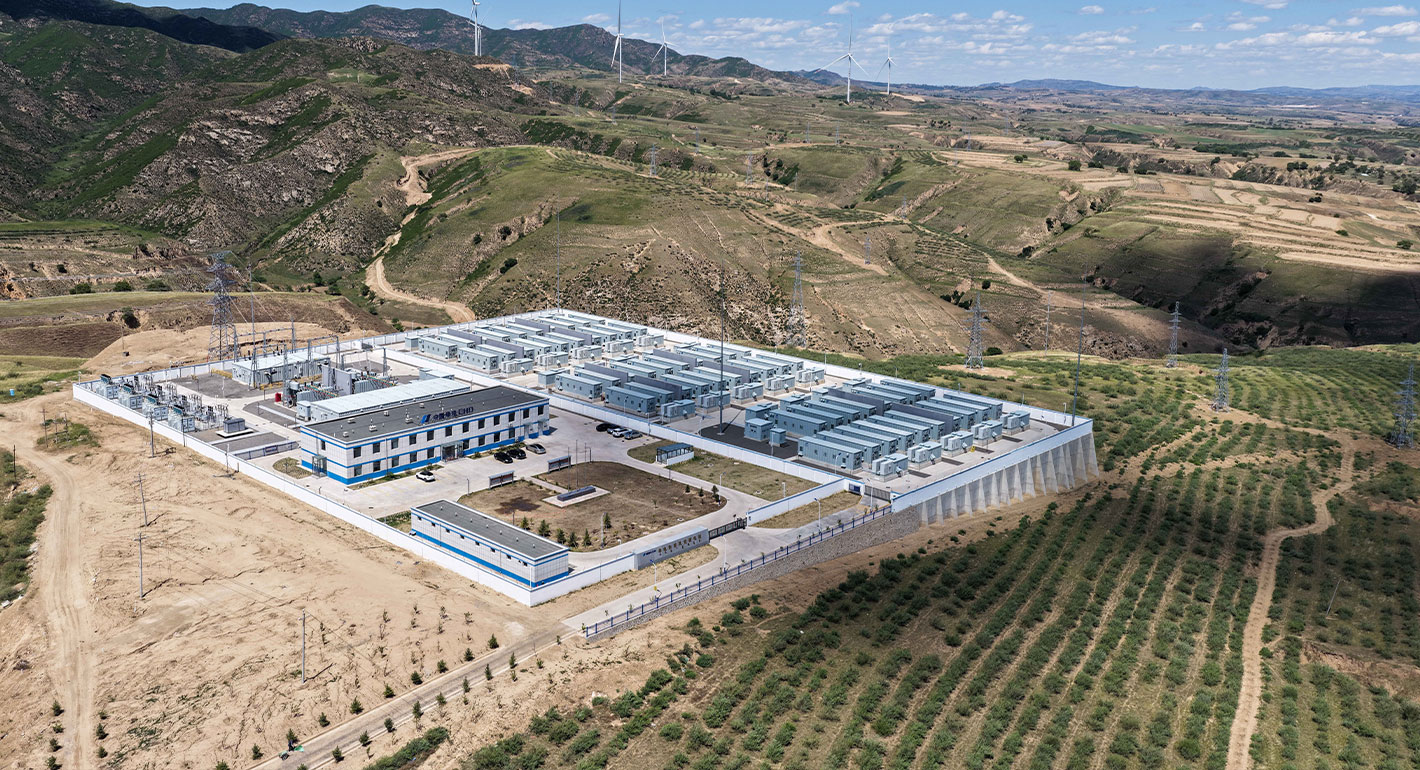
China’s latest energy plan explicitly calls for integrating data centers into the electricity system, particularly connecting them to green energy. It appears Beijing wants to use compute as a source of domestic demand to absorb renewables excess capacity.
Damien Ma
But their "principal to principal" model will only be as effective as the political strength of each leader back home.
Damien Ma
U.S. unpredictability has allowed China to capitalize on its positioning as the “responsible great power”. Paradoxically, the more China wins the perception game, the more likely expectations will rise for Beijing to deliver not just words but to demonstrate with its deeds.
Chong Ja Ian