

Research
- +10
Rosa Balfour, Frances Z. Brown, Yasmine Farouk, …
{
  "authors": [
    "Moisés Naím"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "North America",
    "South America",
    "Southern, Eastern, and Western Africa",
    "India",
    "China",
    "Russia"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}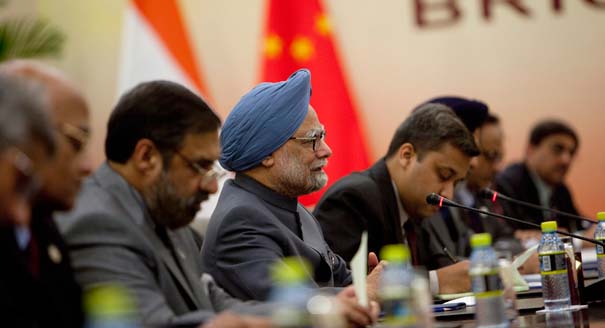
Source: Getty
It has become clear that, other than large territories and populations, the BRICs have little in common.
Source: Washington Post
People blame Goldman Sachs for many things. I blame the investment bank mainly for popularizing the acronym BRIC — Brazil, Russia, India and China — in a 2001 report by economist Jim O’Neill arguing that long-term growth in these emerging markets would surpass that of the world’s richer nations.
Investing in the BRICs sounded like a good idea when these countries were growing quickly and when the most-developed economies were sputtering. But the grouping quickly outlived its usefulness. It has become clear that, other than large territories and populations, the BRICs have little in common. Brazil and India have different domestic political challenges, China and Russia are pursuing disparate development strategies, and China’s geopolitical role is far more complicated than that of its BRIC comrades.Now that the BRICs have entered a rough patch, the allure of these fast-growing economies has faded. Yet the bankers and consultants who dream up such monikers have simply created new ones. They include CIVETS (Colombia, Indonesia, Vietnam, Egypt, Turkey and South Africa), from the Economist Intelligence Unit; CARBS (Canada, Australia, Russia, Brazil and South Africa), identified by Citigroup; and MINT (Mexico, Indonesia, Nigeria and Turkey), coined by Fidelity Investments. Even O’Neill came back with the “Next Eleven” or N-11 (Bangladesh, Egypt, Indonesia, Iran, Mexico, Nigeria, Pakistan, the Philippines, Turkey, South Korea and Vietnam).
The rhetoric is familiar. The CIVETS countries are blessed with “diverse and dynamic” economies; the MINT nations enjoy “favorable demographics for at least the next 20 years”; and the N-11 “could potentially rival the G7 in terms of economic growth over time.”
But these categories reflect smart marketing and packaging of financial products rather than analytical originality or investment acumen. The main trait these countries share is that their economies are as volatile as their politics.
According to all indicators, the best acronym to invest in is still USA.
Distinguished Fellow
Moisés Naím is a distinguished fellow at the Carnegie Endowment for International Peace, a best-selling author, and an internationally syndicated columnist.
Recent Work
Rosa Balfour, Frances Z. Brown, Yasmine Farouk, …
Moisés Naím
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
China’s political future will be shaped between now and next October. As the Communist Party enters its intense “campaign season” to prepare for a major political transition in 2027, reading Beijing's actions and responses may become more difficult as domestic politics weigh on its behavior more than usual.
Damien Ma
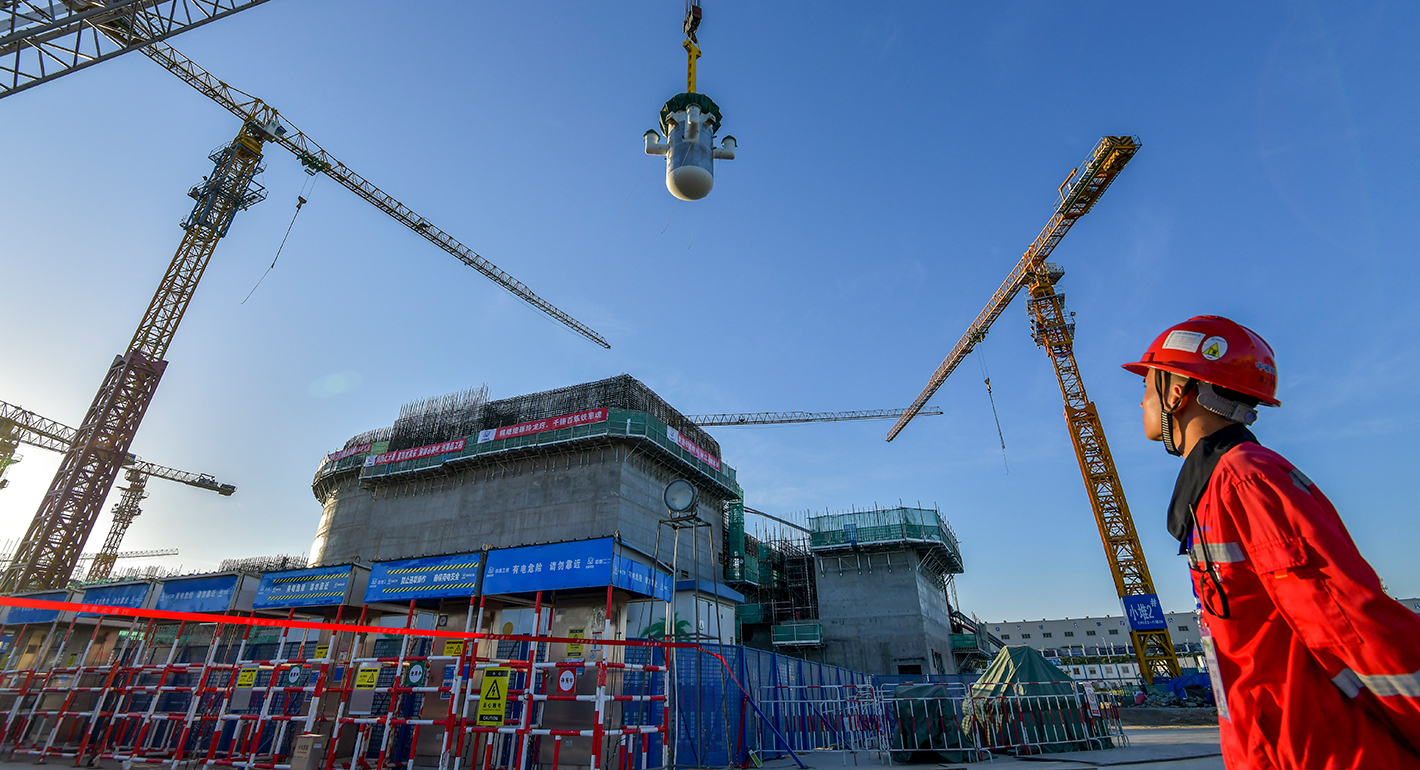
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
Tong Zhao
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis