

Research
- +10
Rosa Balfour, Frances Z. Brown, Yasmine Farouk, …
{
  "authors": [
    "Moisés Naím"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "North America"
  ],
  "topics": [
    "Economy",
    "Global Governance"
  ]
}
Source: Getty
Financial circles are finally taking note of how economic inequity and social exclusion can no longer be tolerated or covered up.
Source: Atlantic
It’s that time of year again. Northern birds flock south for the winter, and the world’s bankers assemble in Washington for the annual meetings of the World Bank and the IMF. Finance secretaries and central bank governors from countless nations descend upon Washington to mingle with their colleagues, leaders of the World Bank, the IMF and the titans of global finance.
For those who believe that the world is shaped by back-door conspiracies and maneuverings of the rich and powerful, these gatherings offer endless possibilities for speculation. The very same bankers who triggered the world economic crisis—those who suffered nary a consequence and in some cases walked away richer than before—come together to toast to their victories, devise new get-rich schemes and coopt even more public servants into serving their never-ending interests.
This is the way conspiracy-theorists imagine gatherings like these, and not for nothing. Just like all conspiracy theories, there is fantasy and exaggeration alongside undisputed truth. After all, nobody can deny that bankers enjoy a disproportionate influence, that their recklessness contributed to the worst economic crash since the Great Depression, and that the consequences of their excesses and errors have been felt more by the unwitting public than by them. This is all true.But it is also true that the crisis did not leave all bankers unscathed. Governments have imposed new restrictions on banks, society is far less trustful, and fierce competition abounds. It will cost JPMorgan over $11 billion to settle fines imposed by the U.S. government. Today, banks face a risky global environment where one miscalculation can bring huge loss. For example: according to the IMF, if in coming years long-term interest rates rise by just 1 percent, bondholders would suffer a loss of $2.3 trillion.
In fact, the annual pilgrimage to Washington is a way for bankers to gather information that helps them gauge the risks they face. And every year, there are new and different worries keeping bankers up at night. In recent years, their greatest fear was the prospect of European economic implosion; now it’s American political dysfunction. The immediate worry, of course, is if Congress doesn’t raise the debt ceiling, the impact will spread far beyond American borders, and world financial instability will ensue. Still, even if political dysfunction is temporarily halted and somehow a deal is struck, nobody will forget how the most important and interconnected economy now seems to be prone to governance accidents that weaken it and disrupt the normal functioning of global financial markets.
In years past, the slowed economic growth in developed countries was at the top of the bankers' worries. Now, it is the looming slow-down of emerging markets. From 2000 to today, the likes of China, India, Brazil, Indonesia or Turkey grew an average of 6 percent a year while the U.S. expanded at a meager 1.8 percent. Not any more. Now, 80 percent of emerging market economies are growing at a slower pace. Lean times are ahead.
This inevitable slowdown will have enormous social and political consequences. We may see the massive street protests that have shaken governments and toppled politicians in some countries spill into nations that have remained relatively calm thus far. This worries bankers. And so in this year's IMF meetings almost every conversation seemed to include the need to make sense of the riots, their causes, consequences, and the best government responses. It is another novelty to hear conversations driven by a desire to find good economic and political reforms for an angst-filled public.
Finally, we’re hearing more about inequality. Financial circles are taking note of how economic inequity, social exclusion and other injustices can no longer be tolerated or covered up as in the past. While bankers don’t have solutions for this, it is telling that in meetings where the principal concern is how to make more money, the worry about inequality becoming a significant source of instability now appears with much more urgency than in any of the meetings in preceding years.
It doesn’t matter if this is because bankers are becoming more socially conscious or if they fear social turmoil is bad for business. What’s interesting is that a topic that has rarely been a part of these conversations is now as frequently mentioned by the world's financiers as the possible default of the U.S. government.
Distinguished Fellow
Moisés Naím is a distinguished fellow at the Carnegie Endowment for International Peace, a best-selling author, and an internationally syndicated columnist.
Recent Work
Rosa Balfour, Frances Z. Brown, Yasmine Farouk, …
Moisés Naím
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
The new Serbian leadership may have promised to keep on cooperating with Russia, but soon they will have to make a choice between fighting corruption and sealing lucrative deals with Moscow. The two are mutually exclusive, even if the new leaders in Belgrade haven’t yet realized it.
Maksim Samorukov
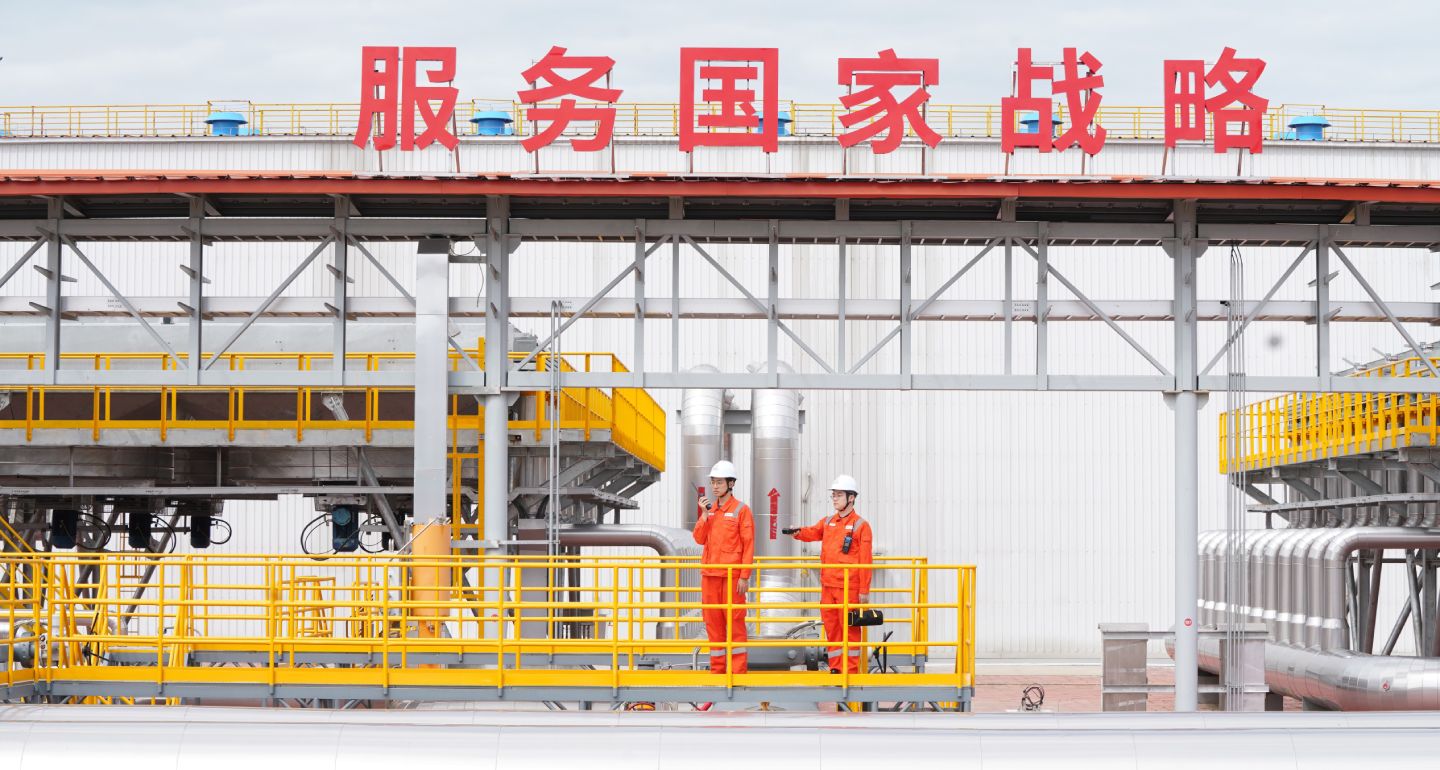
A leak of Russian gas price data helps establish that China is paying Russia far less than Central Asian countries and Gazprom’s former European customers.
Sergey Vakulenko
Japan’s long-term security policy is driven by concerns about China, and there is little appetite for (or interest in) pursuing a confrontation with Moscow.
James D.J. Brown
Russia’s AI-driven propaganda campaigns operate in a fragmented, chaotic, and often illogical manner. That’s not necessarily a problem for the Kremlin, though: It’s much easier to mimic genuine public debate that way.
Ilya Klishin
Russian strikes are weakening the economy sustaining Ukraine’s war effort. Closing the growing funding gap will require more European support and politically contentious reforms in Kyiv.
Balázs Jarábik