

Article
Suyash Rai, Anirudh Burman
{
  "authors": [
    "Suyash Rai"
  ],
  "type": "other",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie India"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie India",
  "programAffiliation": "",
  "programs": [],
  "projects": [
    "Political Economy"
  ],
  "regions": [
    "India"
  ],
  "topics": [
    "Domestic Politics",
    "Economy"
  ]
}
Source: Getty
The financial system plays an important role in mobilizing savings, allocating capital in the economy, monitoring corporations, providing liquidity, helping individuals and firms manage risks, facilitating payments, and other economic functions.
Source: Hart Publishing
Banking is not only basically 19th-century technology, but it is disaster-prone technology.1
—Merton Miller
The financial system plays an important role in mobilising savings, allocating capital in the economy, monitoring corporations, providing liquidity, helping individuals and firms manage risks, facilitating payments and other economic functions. There is significant evidence of the positive impact of financial development on the economy.2 Financial systems of different countries differ in terms of their institutional structure, with some being largely market-based and others more bank-based.3
India’s financial system is largely bank-based. As of 31 March 2016, about 45.5 per cent of borrowing of non-financial firms was from banks (see Figure 6.1). For private non-financial firms, the share of bank loans was 51.6 per cent, while bonds and foreign borrowing added up to less than a quarter of borrowing. As of 31 March 2016, the ratio of scheduled commercial banks’ deposits to gross domestic product (GDP) was 67.8 per cent, up from 41.4 per cent at 31 March 1996. The total deposits with banks were Rs 103.6 trillion, while the total assets under management with mutual funds and the pension system were only Rs 13.5 trillion. Given the salience of banks in the economy, regulation of banking is a crucial function of the Indian state.
This book chapter was originally published by Hart Publishing.
1 Merton Miller, ‘Financial Markets and Economic Growth’ (2003)11(3) Journal of Applied Corporate Finance 8, 15.
2 See generally Raghuram G Rajan and Luigi Zingales, ‘Financial Dependence and Growth’ (1998)88(3) American Economic Review 559, 586.
3 Asli Demirgüç-Kunt and Ross Levine, ‘Bank-Based and Market-Based Financial Systems: Cross-country Comparisons’, World Bank, 1999, available at http://documents.worldbank.org/curated/en/259341468739463577/pdf/multi-page.pdf.
Former Fellow, Carnegie India
Suyash Rai was a fellow at Carnegie India. His research focuses on the political economy of economic reforms, and the performance of public institutions in India.
Recent Work
Suyash Rai, Anirudh Burman
Shruti Sharma, Suyash Rai, Konark Bhandari, …
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
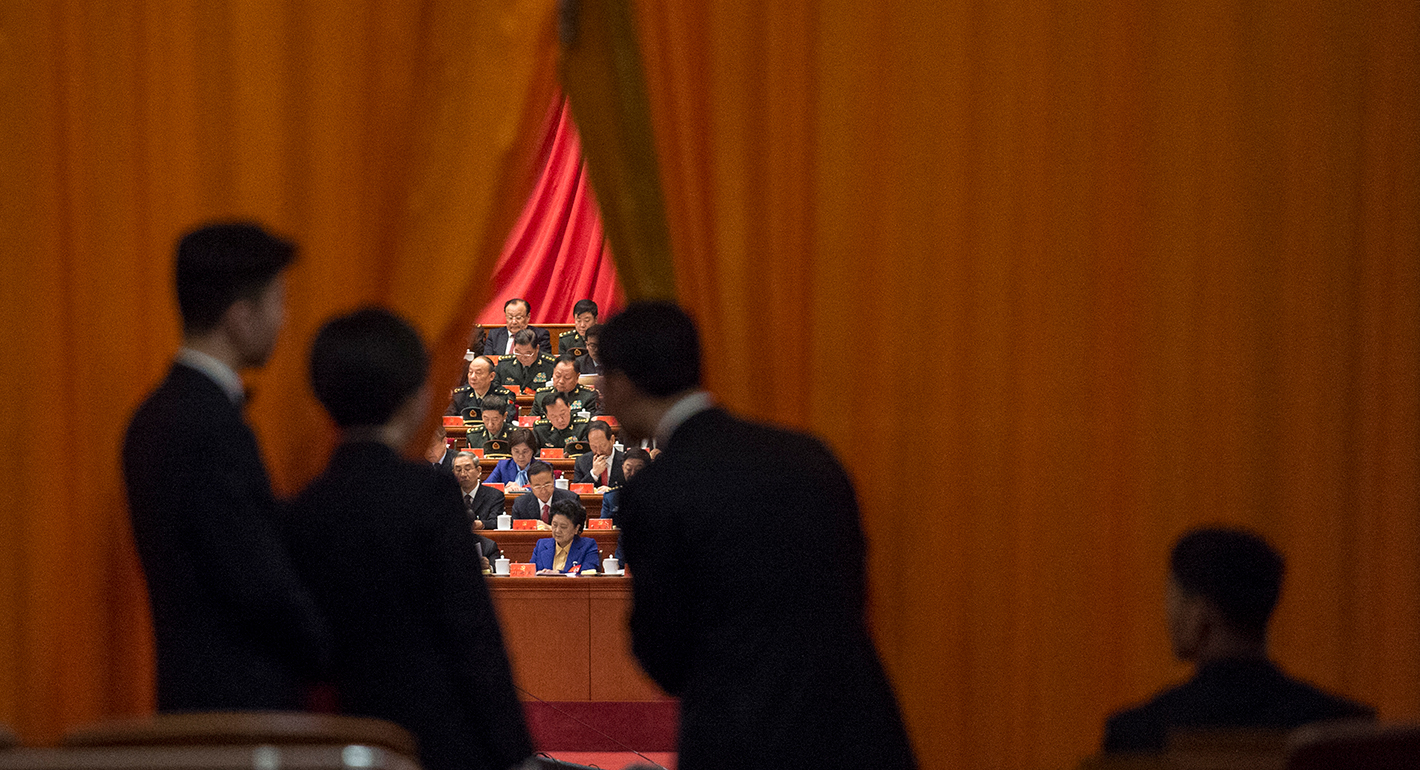
China’s political future will be shaped between now and next October. As the Communist Party enters its intense “campaign season” to prepare for a major political transition in 2027, reading Beijing's actions and responses may become more difficult as domestic politics weigh on its behavior more than usual.
Damien Ma
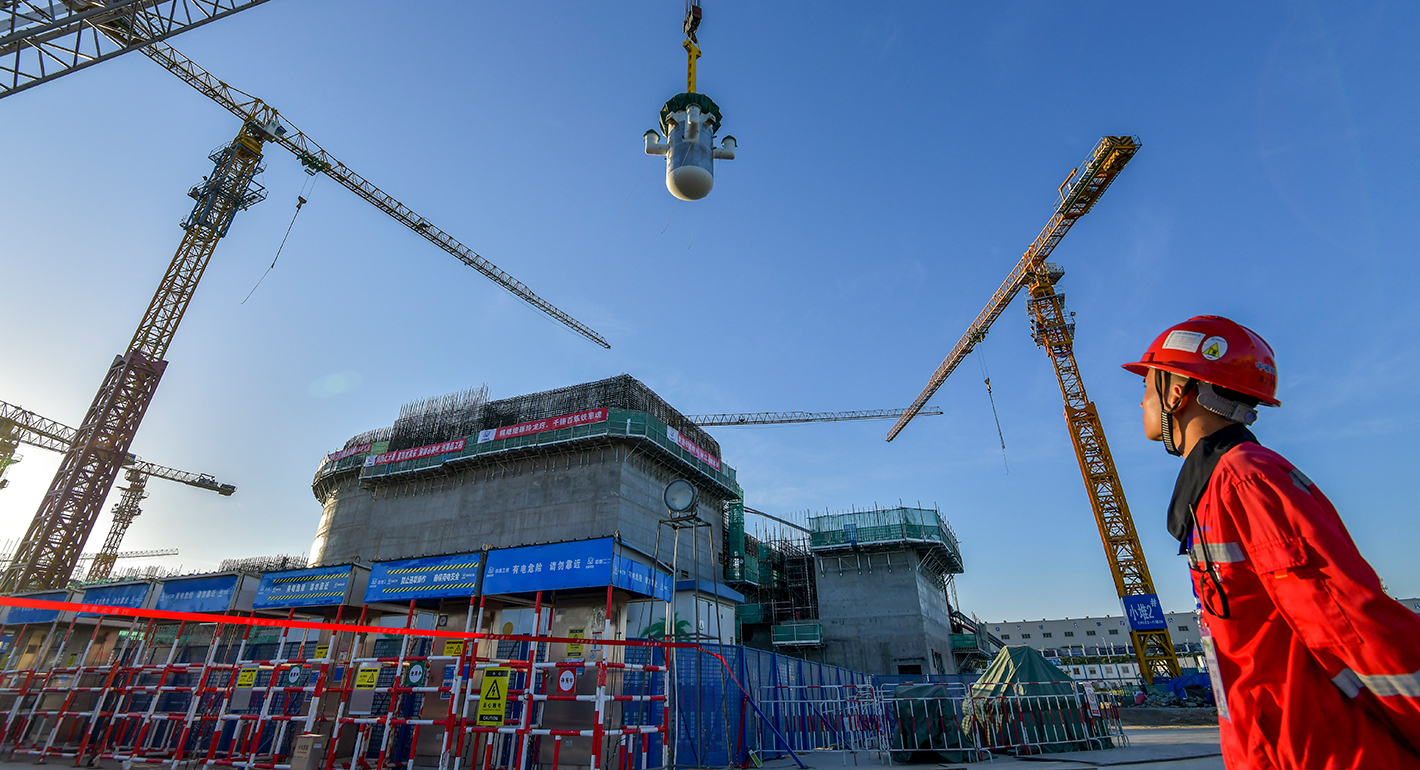
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
Tong Zhao
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis
In the latest Five-Year Plan, the Chinese president cements the shift to an innovation-driven economy over a consumption-driven one.
Damien Ma