

Commentary
With its public finances in shambles, the far right polling at 35 percent ahead of the 2027 presidential election, and a growing protest movement, is France’s crisis a threat to the EU’s geopolitical awakening?
Rym Momtaz, ed.
{
  "authors": [
    "Yukon Huang",
    "Canyon Bosler"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}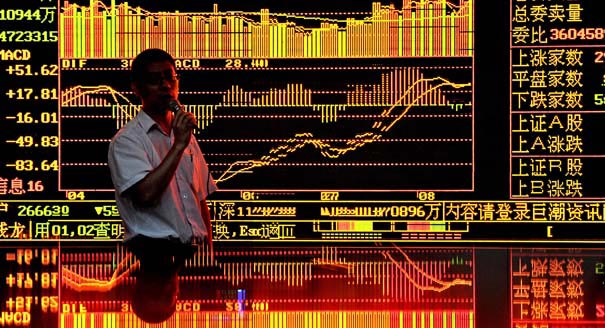
Source: Getty
China will see a rise in banks’ nonperforming loans and increasingly frequent defaults in the bond and shadow banking markets. This process will be very messy but is unlikely to derail the economy.
Source: Wall Street Journal
China watchers are debating whether China's economic slowdown has finally hit bottom or its financial system is headed for a crash. Those who foresee an imminent crisis point to the alarming speed of booming credit and rising debt as a share of GDP. That case, however, is hardly airtight.
A more likely scenario is that China's economy will continue to hemorrhage slowly over the next few years but will be propped up by periodic mini-stimulus injections. If Beijing deals with its vulnerabilities effectively, and that is still a big if, the end game should not be a crisis but a more risk-conscious financial system and sustainable annual growth of 7% to the end of this decade.
The doomsday scenario is concerned with the total debt of Chinese households, firms and the government. This has grown sharply since 2008 to around 210% of GDP in 2013. The rate of increase is much higher than the 40-50 percentage point booms that occurred in the U.S. and United Kingdom before the global financial crisis, Korea before the Asian financial crisis, or Japan before its lost decade.The more pessimistic analysts also expect China's debt to GDP ratio to continue rising, driving the interest burden of the debt to around 20% of GDP in 2017 from its current 12%. They believe that while the day of reckoning may not be tomorrow, it will likely arrive in a few years.
More optimistic observers point out that China's debt of around 210% of GDP is not abnormally high. Its ratio is close to that of regional peers Taiwan, Korea, Malaysia and Thailand and much lower than advanced economies, whose debt has averaged over 300% of GDP in recent years. But while the level of debt may not be a problem, the speed and extent of the rise are seen to create vulnerabilities.
Even if that's correct, China differs from its predecessors. Its initial rise in debt was the result of a deliberate state-driven stimulus program in response to the global financial crisis, which successfully prevented a sharp downturn.
In other crisis countries, a credit surge was due to the culmination of a long-term deterioration in financial indicators. This was brought on by excessive external borrowings, rising current account deficits and overvalued exchange rates or excessively leveraged housing markets exacerbated by chronic fiscal deficits.
China's rise in debt after the stimulus was fed by a construction boom which many see as a property bubble. A more likely explanation for the sharp rise in housing prices is that the market is trying to establish appropriate values for assets previously hidden in a socialist system.
Until housing was privatized a decade ago, there had been no property market. In this view, credit expansion can be seen as financial deepening rather than creating a serious debt problem.
Credit booms are also not inherently problematic. While almost all financial crises are preceded by credit booms, a recent IMF report shows that only a third of credit booms result in a financial crisis. On average, countries that had credit booms between 1970 and 2010 saw 50% more growth in per capita incomes than countries that did not have credit booms.
Moreover, China bears need not be so pessimistic about whether the economy can wean itself off credit. Structural shifts in the type of investment that is valued (growth-enhancing projects rather than buying up land), improving business conditions (particularly rising global demand), and more stable property prices give reason to believe that credit buildup will level off.
Pessimists can also rest assured that aside from the surge in debt, China has few of the common risk factors for financial crises. Its current account surplus is 2% of GDP, external debt only 10% of GDP, foreign exchange reserves at 40% of GDP, and a fairly valued if not undervalued currency.
Similarly, with below-normal loan-to-deposit ratios of 70% and minimal dependence on flighty wholesale funding, China's banks are highly liquid. They are not particularly vulnerable to a U.S.-style freeze of the interbank lending market.
The economy also continues to be buffered by the highest national savings rate of any major economy. And even after accounting for the recent surge in local government liabilities, the government has a relatively healthy government balance.
Rather than a financial crisis we should expect a slow hemorrhaging of financial resources with a rise in banks' nonperforming loans. Increasingly frequent defaults in the bond and shadow banking markets are also to come. This process will be very messy but is unlikely to derail the economy.
The real question is whether the government will be able to implement the productivity-enhancing reforms enshrined in the Third Plenum package to stem the hemorrhaging or if it will allow the financial system and economy to slowly bleed out.
This article originally appeared in the Wall Street Journal.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Canyon Bosler
Former Junior Fellow, Asia Program
With its public finances in shambles, the far right polling at 35 percent ahead of the 2027 presidential election, and a growing protest movement, is France’s crisis a threat to the EU’s geopolitical awakening?
Rym Momtaz, ed.
While the EU and European governments are embracing the much-lauded middle-power moment, this entails three difficult conundrums.
Richard Youngs
Europe is facing rising populism internally as well as external pressures from Russia, China, Turkey, and the United States.
Dimitar Bechev
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.
The domestic impacts of how long it is taking to end the war in Ukraine have pushed the French electorate to the political extremes and compromised the country’s diplomatic capacity.
Rym Momtaz