

Commentary
With its public finances in shambles, the far right polling at 35 percent ahead of the 2027 presidential election, and a growing protest movement, is France’s crisis a threat to the EU’s geopolitical awakening?
Rym Momtaz, ed.
{
  "authors": [
    "Caroline de Gruyter"
  ],
  "type": "commentary",
  "blog": "Strategic Europe",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe"
  ],
  "collections": [
    "EU Integration and Enlargement"
  ],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Europe",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "Europe",
    "Western Europe",
    "France",
    "Germany"
  ],
  "topics": [
    "EU",
    "Climate Change",
    "Economy"
  ]
}
Source: Getty
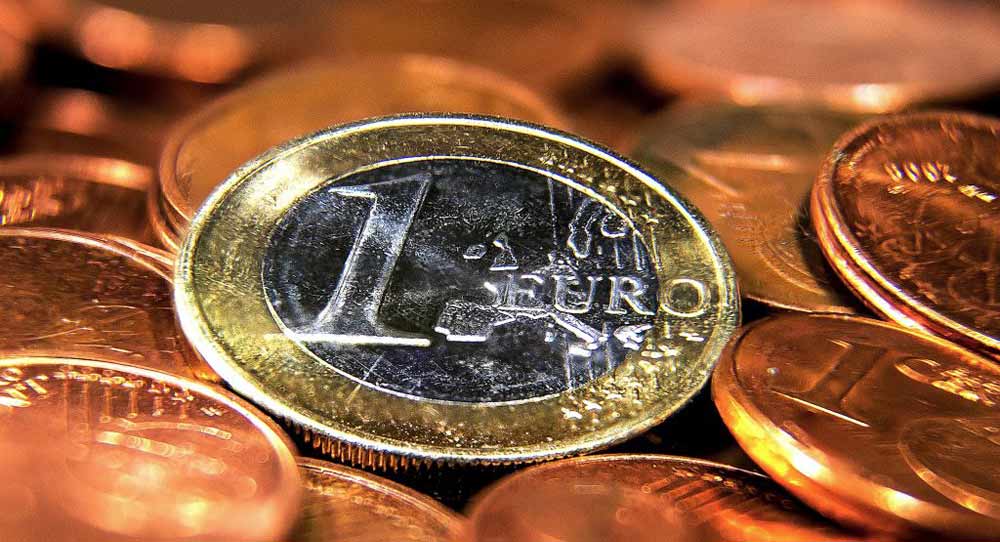
To increase its power in Europe and lessen German dominance, France needs to change itself and build a real European political union to underpin the euro.
One of the two remaining candidates in the 2017 French presidential election, Marine Le Pen of the far-right National Front, wants France to leave the eurozone. “We are at the mercy of a currency adapted to Germany and not to our economy,” she said at a campaign rally in April. In her view, a French exit is the only way to get rid of German dominance in the eurozone and restore French sovereignty. “The euro,” Le Pen added, “is mostly a knife stuck in our ribs to make us go where others want us to go.”
How ironic. France proposed the euro back in the 1980s. The currency was introduced in the 1990s under strong French pressure. The reason at the time: France wanted its sovereignty back from Germany.
Before the euro existed, most European countries had their own currency. The West German deutsche mark was stronger than the French franc. There were several reasons for this, one being that West Germany’s economic and monetary policies were more disciplined than France’s. In fact, the deutsche mark was so strong and stable that most of West Germany’s neighbors blindly followed the decisions of the German Federal Bank. Whenever the bank raised or lowered interest rates, neighboring central banks would follow suit the next day.
The German Federal Bank de facto governed Austria, Belgium, France, Luxembourg, and the Netherlands. These countries were in a deutsche mark zone—as Denmark now follows the eurozone’s policies without using the euro. Belgium and the Netherlands could live well with this monetary dependence. France could not; it is a big, proud country. This is why the idea of a common currency was so interesting for the French: by being jointly administered by West Germany and France, it would increase French monetary influence in Europe.
The Germans were not against the idea—a common currency would be a significant step toward more European integration, which they welcomed. However, they preferred to wait. They thought Europe’s economies were too divergent for one currency to be stable. Bonn wanted first to bring the economic and budgetary policies of participating countries closer together. In West Germany’s view, such a political union should precede a monetary union, while France wanted it the other way around.
Then, in 1989, the Berlin Wall came down. Suddenly, reunification of the two Germanys was the dominant issue in Europe. The French were not happy with this: a larger Germany would change the balance of power on the continent. But they understood that reunification would be unavoidable. So they said yes—on one condition: that the euro, which had been under discussion for some time between Bonn and Paris, would be introduced soon. For Germany, it was a high price to pay. But the Germans were willing to accept it provided the French agreed that work would start in parallel on a political union. The euro was established by the provisions of the Maastricht Treaty in 1992; coins and banknotes were introduced in January 2002.
German reunification gave France the chance to retrieve monetary power without reforming the economy, which would have been the best way to rebalance the Franco-German inequality. The euro is a continuation of the deutsche mark. The European Central Bank (ECB) is modeled on the German Federal Bank. But there is one fundamental difference: Germany doesn’t control the euro as it did the deutsche mark. It’s the ECB that governs the euro, and the French have a strong say. Put differently: with the introduction of the euro, Germany lost sovereignty, while France gained it.
Until the eruption of the euro crisis in 2010, little work was done on the political union. When France and Germany had excessive deficits in the early 2000s, they just changed the rules. Eurozone countries kept drawing up national budgets without any coordination. Interference from Brussels was unwelcome, not least in Paris. This is why the euro crisis struck so hard: the euro had no backup. The damage for the French economy was particularly severe, while the German economy rebounded faster. The crisis widened the gap between the two countries even further.
Today, in a way, France is back where it was before the introduction of the euro: feeling vulnerable and powerless. It lags behind Germany economically, having postponed necessary reforms. And yet again, the French reflex is to blame Germany. Le Pen argues that Germany should move first and make concessions, so France can exercise the power and influence it deserves. This was also the reasoning of eight of the other ten presidential candidates in the first round of the election.
Le Pen’s competitor in the second round, Emmanuel Macron, is the only candidate who has argued the other way around. He says that France must clean out its stables first and finally build a real European political union to underpin the euro. Macron understands that France can only increase its power in Europe—and lessen German dominance—by changing itself.
Macron is right. Exiting the eurozone would not bring France more sovereignty. On the contrary, it would further weaken the country. This would endanger the European project. If Le Pen’s furious demands prove anything, it is that the European project is still about the balance of power between France and Germany. If Macron loses, Europe will have an immense problem.
Caroline de Gruyter is a Europe correspondent for NRC Handelsblad based in Vienna.
Caroline de Gruyter
Caroline de Gruyter is the European affairs correspondent for the Dutch newspaper NRC Handelsblad.
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
With its public finances in shambles, the far right polling at 35 percent ahead of the 2027 presidential election, and a growing protest movement, is France’s crisis a threat to the EU’s geopolitical awakening?
Rym Momtaz, ed.
Ahead of a tough winter for Ukraine, Donald Trump’s swing back toward Russia bodes ill. But instead of panicking, Kyiv’s European allies are focusing on action.
Rym Momtaz
While the EU and European governments are embracing the much-lauded middle-power moment, this entails three difficult conundrums.
Richard Youngs
Much has been said of the changes Brussels is trying to make to the EU enlargement process. Here’s why gradual integration might—or might not—be the answer.
Dimitar Bechev
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.