

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "United States",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
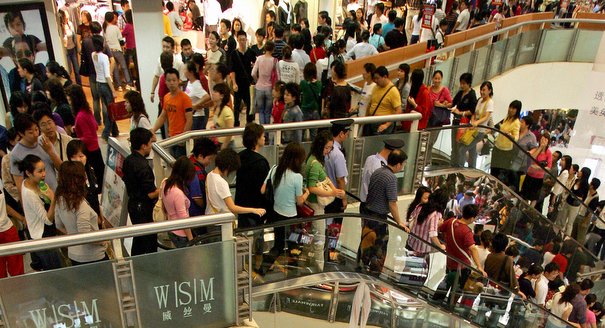
With little chance that China will be able to increase its consumption rate to compensate for increased U.S. savings rates, the world may face a period of slower growth.
Source: The New York Times

These policies inevitably require households to foot the bill, primarily through sluggish wage growth, low interest rates on their bank deposits, an undervalued currency and a weak social safety net. Since total savings is just the difference between what is produced and what is consumed, subsidizing producers at the expense of household consumers necessarily causes savings to rise.
But Beijing’s massive stimulus will probably prevent the necessary adjustment toward faster consumption growth from taking place in the near future. Instead of reversing those policies that shift income from households to producers, which might have also caused a surge in unemployment, Beijing forced through a large increase in investment.
As in the past, households will be forced to foot the bill for any misallocated investment or non-performing loans, which could be considerable, making it difficult for households to power consumption growth.
This will be a problem for China and the world. As the U.S. rebalances its economy toward higher savings rates, China has no choice but to rebalance toward higher consumption rates. This can happen either because of a sharp pick-up in consumption growth or, more likely, a sharp slowdown in GDP growth. I worry that China will find it difficult to generate the kind of consumption growth that will take up some of the American slack, and we may be locked into a period during which the world adjusts by growing more slowly.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
The EU can impose sanctions but struggles to enforce them without the United States. With Washington increasingly disinterested in backing European interests, the bloc must now fend for itself.
Nicu Popescu, Tiago Antunes
With its public finances in shambles, the far right polling at 35 percent ahead of the 2027 presidential election, and a growing protest movement, is France’s crisis a threat to the EU’s geopolitical awakening?
Rym Momtaz, ed.
Ahead of a tough winter for Ukraine, Donald Trump’s swing back toward Russia bodes ill. But instead of panicking, Kyiv’s European allies are focusing on action.
Rym Momtaz
While the EU and European governments are embracing the much-lauded middle-power moment, this entails three difficult conundrums.
Richard Youngs
Europe is facing rising populism internally as well as external pressures from Russia, China, Turkey, and the United States.
Dimitar Bechev