

Q&A
- +1
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}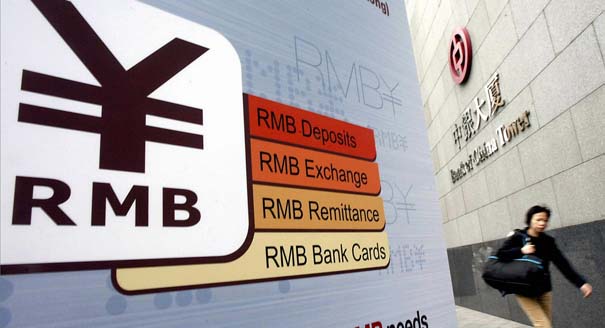
Source: Getty
The decision not to bail Chaori out is not a true test of Beijing’s commitment to allow the “market to play a decisive role” in resource allocation as announced last year in the third plenum.
Source: Financial Times
Whenever there is a sign of possible weakness in China’s financial armour there are voices that cry out that a crisis is brewing. The latest example is the recent default on a bond payment by Shanghai’s Chaori Solar Energy Science and Technology. This quickly prompted questions about whether this was China’s “Bear Stearns or Lehman moment”. Less alarmist views welcomed the default as a signal that the government wanted to instil a sense of prudent risk-taking.
Interpretations of Premier Li Keqiang’s statement that future defaults may be unavoidable also depended on one’s sentiments, with some seeing it as a sign of imminent problems and others dismissing it as an acknowledgment that defaults are part of every economy.
All this, however, may be missing the point.Although Chaori is a landmark as the first onshore bond default, it tells us little about China’s financial risks. After all, the problems of Chaori, and the solar sector more generally, are well known and their implications have long been factored into market expectations. No one in China’s financial markets is surprised that Chaori could not pay: it was always a question of whether it would be bailed out.
But the decision not to bail Chaori out is not a true test of Beijing’s commitment to allow the “market to play a decisive role” in resource allocation as announced last year in the third plenum. Chaori was an easy target as a relatively small private company in a major city that is not dependent on it for revenues or employment. Its bonds are held by retail investors with little clout. It is also in an industry with excess capacity that officials have earmarked for downsizing and consolidation.
Contrast this with the pre-third plenum case of LDK Solar, a large private company that employed 20,000 workers and accounted for 12 per cent of the taxes for the city of Xinyu in Jiangxi province, central China. Like Chaori and other solar businesses, LDK had financial difficulties. But given its importance to Xinyu, the municipal authorities passed a resolution guaranteeing repayments of Rmb500m in loans. In that case being private was not a barrier to a bailout as the firm was too big to fail. Chaori does not tell us whether that has changed since the third plenum.
In short, Chaori tells us nothing about the prospects of an impending financial crisis (which is unlikely) or whether market risks will now be more appropriately priced. But even if it had told us how Beijing chooses to deal with private firms, the much deeper issue is whether the party is willing to allow defaults by state-owned enterprises. Creative destruction is the heart of a thriving market economy, with bankruptcy and defaults creating opportunities for new entrants driving change – SOEs must not be exempted from that pressure.
More than a decade ago China launched a policy to reform SOEs by cutting back on direct subsidies and closing or privatising the poor performers under the slogan of “grasp the big, release the small”. The total number of SOEs fell from 260,000 in 1998 to about 145,000 in 2003. The creation of the State-Owned Assets Supervision and Administration Commission (Sasac) in 2003, with the mandate to represent state interests in the SOEs, slowed down exits, with the steep decline in the numbers of SOEs coming to a halt with about 115,000 by 2008.
But the SOE reform initiative had already made its mark by the time the global financial crisis hit. Returns on assets of industrial SOEs rose from 1 per cent in 1998 to more than 6 per cent by 2008, nearly closing the gap with private companies. But with the flood of financial support from the 2008 stimulus program, which was largely targeted at the state sector, incentives for more efficient SOE performance were seriously weakened.
The result has been a decline in returns on assets to about 4 per cent, while returns for private companies have continued to rise to roughly 11 per cent. This gap between the returns of private and public companies explains a significant part of the recent decline in China’s economic growth.
Financially, the discipline-weakening impact of the stimulus program and Sasac’s unwillingness to pressurise poor-performing SOEs to exit the scene have also taken their toll. Thus while overall, China’s industrial sector is not under unusual financial stress, the SOEs as a class are much more highly leveraged than private firms. At the end of 2012, SOE debt was 4.6 times their earnings compared with just 2.8 times for private businesses. The debt to profit ratio of private listed companies is 5 per cent lower than in 2008, before the crisis, compared with a 33 per cent rise for listed SOEs. Private businesses have 60 cents in operating cash flow for each dollar of current liabilities, while centrally owned SOEs have just 30 cents. Thus the more important candidates for defaults and restructuring, especially if implicit subsidies are factored in, lie in the state sector.
Will Beijing address seriously the need to encourage poorly performing SOEs – big or small – and not just the odd private firm, to exit? November’s third plenum decision does call for creating a “market exit mechanism”. If so, defaults will be taken much more seriously as credible evidence of the new government’s strategic objectives.
This article was originally published in the Financial Times.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Yukon Huang, Isaac B. Kardon, Matt Sheehan
With its public finances in shambles, the far right polling at 35 percent ahead of the 2027 presidential election, and a growing protest movement, is France’s crisis a threat to the EU’s geopolitical awakening?
Rym Momtaz, ed.
While the EU and European governments are embracing the much-lauded middle-power moment, this entails three difficult conundrums.
Richard Youngs
Europe is facing rising populism internally as well as external pressures from Russia, China, Turkey, and the United States.
Dimitar Bechev
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.
The domestic impacts of how long it is taking to end the war in Ukraine have pushed the French electorate to the political extremes and compromised the country’s diplomatic capacity.
Rym Momtaz