

Commentary
Yukon Huang, Isaac B. Kardon, Matt Sheehan
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
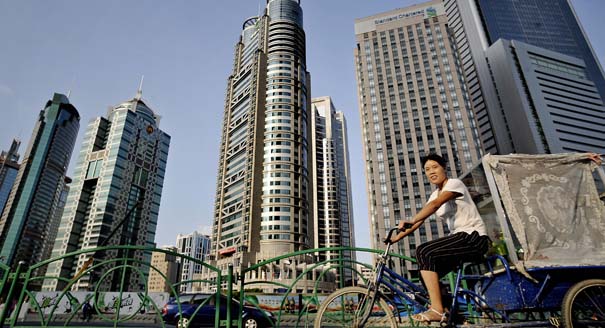
Though a correction is coming to China’s property market, the consequences will be more manageable than common sense might suggest.
Source: Wall Street Journal
Will China's property bubble trigger a financial crisis? Concern is high this year thanks to deteriorating sales figures and reports of large price cuts. But China really is different. Though a correction is coming, the consequences will be more manageable than common sense might suggest.
No real property market existed in China until housing was privatized more than a decade ago. Then came the 2008 global financial crisis and Beijing's credit expansion, after which Chinese land prices surged five-fold, triggering commensurate increases in property prices and other asset values. In other words, the market was trying to establish appropriate prices for an asset whose value was previously hidden by socialist fiat (a pattern also seen a decade ago in Russia).Instead of a bubble, therefore, China's sharp property-price increases could represent the real value of land in a densely populated country. If so, they would signal the Chinese economy's financial deepening, not the imminent onset of a financial collapse.
A main concern is that China has allowed housing construction to outpace requirements, especially in second- and third-tier cities, so prices will fall. But the correction may not be destabilizing because long-term trends in Chinese property prices don't fit the typical pattern of a bubble.

China's property market has seen cyclical downturns followed by rebounds, most recently when housing prices started falling in late 2011 and then turned upward again in the second half of 2012. It is hard to find past bubbles that experienced such significant and persistent price declines before reversing and continuing to inflate. When prices start falling in a bubble situation, investors typically rush for the door and cause a collapse.
That China's property market saw no such collapse in 2012 suggests that its high prices were supported by more than "irrational exuberance" and may be a reasonable floor—implying, in turn, that today's prices may fall by about 20% over the coming year but not more than 30%.
The China Household Finance Survey (published by Chengdu's Southwestern University of Finance and Economics) indicates that even after a 30% decline in prices, only 3% of households would be underwater thanks to high down payments and accumulated equity. The strength of household balance sheets has led the Bank of China 601988.SH +0.77% to estimate that a 30% drop would have a negligible impact on bank ratios of non-performing loans and thus would have only modest spillover effects.
Still, scaling back property construction will have a negative impact on growth. Construction and real estate have been gradually rising as a share of economic activity for three decades and today account for 13% of GDP. Contraction there will slow growth and have ripple effects on related industries.
But China's construction and real-estate boom, like its property market, does not fit the pattern common to bubble countries. As the nearby chart shows, the 1997 Asian financial crisis saw construction and real-estate activity in other Asian counries collapse after sharply increasing in previous years.
Estimates of China's excess property stock suggest that construction volume will fall by roughly 10%, subtracting two to three percentage points from GDP growth. Yet the full impact of the correction on GDP growth is likely to be spread out over several years. If uncompensated by other infrastructure investments, it could cause growth to fall toward 6% in the next year or two—but darker scenarios, in which growth collapses to 5% or less, are highly improbable.
Many China bears are nevertheless convinced that the only thing that has kept China's growth so high in recent years is the even faster growth of credit, and that eventually a credit curb will cause a sharp economic contraction. That pessimism isn't warranted given the link between credit expansion, property-price increases and GDP growth.
The credit expansion that has supported increases in property prices doesn't contribute to GDP growth but is reflected in China's increased fixed asset investment—which is why China's debt-to-GDP ratio has surged in recent years. But this increase is only a problem if rising asset values aren't sustainable. Rising debt-to-GDP isn't a problem if, despite whatever credit was wasted, the bulk of it was used productively and unlocked real value in land-related assets.
As such, most of the surge in Chinese credit since the global financial crisis can be considered healthy financial progress toward more market-based asset values. China's debt-to-GDP ratio is about what one should expect—lower than that of most developed countries but higher than that of most developing countries. In this context, China's property-related debt problem needs to be managed, but it isn't the catastrophe that some are warning about.
This article was originally published in the Wall Street Journal.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Yukon Huang, Isaac B. Kardon, Matt Sheehan
Yukon Huang, Genevieve Slosberg
The hybrid warfare landscape is evolving rapidly, leaving policymakers without clear strategies. To better inform their work in addressing emerging challenges, governments must dig deeper into the underlying dynamics at play.
Raluca Csernatoni, Alicia Wanless
As geopolitical rivalry weaponizes global supply chains, the EU’s true vulnerability lies in emerging-risk imports. For these goods, suppliers are growing more concentrated, substitution more difficult, and political risk is looming.
Sinan Ülgen
The EU is putting together a new security strategy to meet today’s myriad challenges. But for any proposal to be effective, the union needs to grapple with its identity and ambitions.
Pierre Vimont
Amid uncertainty caused by the Iran war, the global drive for nonproliferation has stalled. With Europe diplomatically marginalized and countries reassessing their nuclear options, efforts to curb the spread of nuclear weapons risk becoming irrelevant.
Jane Darby Menton
Between the United States’ market-driven approach and China's state-led industrial strategy, Europe is reckoning with how it can remain competitive in the global economy. But is Europe in danger of becoming a U.S. or China colony?
Noah Barkin, Anu Bradford