

Commentary
Uri Dadush
{
  "authors": [
    "Uri Dadush"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "Western Europe",
    "North America"
  ],
  "topics": [
    "Economy"
  ]
}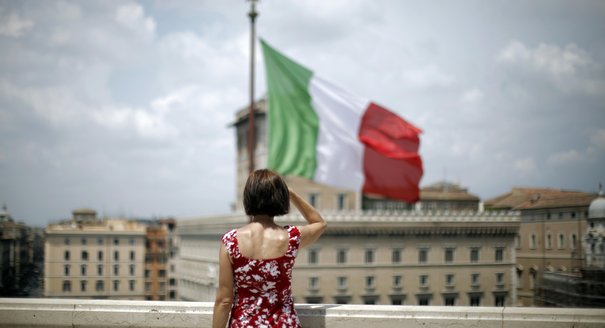
Source: Getty
Based on the experience of Greece, Ireland, and dozens of other countries that have had to resort to IMF-style rescue programs, Italy is unlikely to avoid a protracted and deep recession.
Source: L'Espresso

Less understood is that the traditional components of an IMF rescue program are also in place, though with one crucial difference. The first standard component was an explicit letter of intent from then prime minister Berlusconi to European Commission President Barroso detailing the measures that Italy intends to take and deadlines it intends to hit to put its fiscal house in order and make the economy competitive. The other standard component was the call on the IMF (and the EU) to exercise tight monitoring of the proposed Italian reform program in a bid to exercise discipline, bring technical expertise to bear, and, above all, reassure the markets. Together, these two elements comprise the conditionality that always accompanies IMF programs.
The crucial difference is that, unlike an ordinary IMF program, there is no loan to help Italy finance its deficit during the three years that are usually needed, if all goes well, to regain market access at reasonable interest rates. This is for a very good reason: neither the IMF nor the European Financial Stability Facility has enough money to rescue Italy. They are not structured to rescue a giant economy requiring a loan somewhere near a trillion euros.
Enter the European Central Bank (ECB). Instead of a loan, Italy may be able to count on the ECB to conduct emergency purchases of its bonds to avoid them hitting levels where Italy’s borrowing becomes unsustainable. Given Italy’s growth rate, inflation, and projected primary surplus, that limit—around 7percent on 10-year bonds—has already been breached, hopefully temporarily.
Two questions demand answers: first, what can Italy expect now that it is in a virtual IMF program? Second, what is the implication of having to rely on the ECB instead of a loan?
The first answer is that, based on the experience of Greece, Ireland, Portugal, and dozens of other countries that have had to resort to IMF programs, Italy is unlikely to avoid a protracted and deep recession. Once market confidence is lost, it is not quickly regained; and if the government has to pay 7 percent to borrow, how many firms and individuals can expect to pay less? Italy’s economy is in better shape than Greece’s and its banking system is in better shape than Ireland’s, but it is sobering to remember that private consumption has already fallen from by 15 percent in Greece and 20 percent in Ireland its 2007 peak. If Italy’s program does not work, as in the case of Greece, default on the debt and possible exit from the Euro zone will be the outcome.
The answer to the second question is unknown, because there is no precedent for a large country being bailed out by an international central bank—moreover, a central bank that is explicitly barred from doing so. What is certain is that the ECB’s purchases of government bonds is what currently stands between Italy (and the whole eurozone) and disaster.
Prominent observers such as Martin Wolf have argued that blanket guarantees of all members’ bonds by the ECB would end the crisis. But this is a pipe dream. Turning the ECB’s emergency purchases into a permanent arrangement does not deal with the underlying fiscal and competitiveness problems, and in fact removes the incentives for politicians to deal with them. Such a strategy will inevitably erode political support of the monetary union in the core nations—whose citizens know full well that their currency is being debased, and that their central bank is taking on extraordinary risks that they will have to bear.
The consequence of not reacting promptly to the crisis is that Italy’s future is now the stake of a giant poker game between the ECB, Italian political leaders, and the markets.
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Recent Work
Uri Dadush
Uri Dadush
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
Are Germany’s economic, industrial, and political struggles becoming a liability for the EU’s ability to rise to the geopolitical moment?
Rym Momtaz, ed.
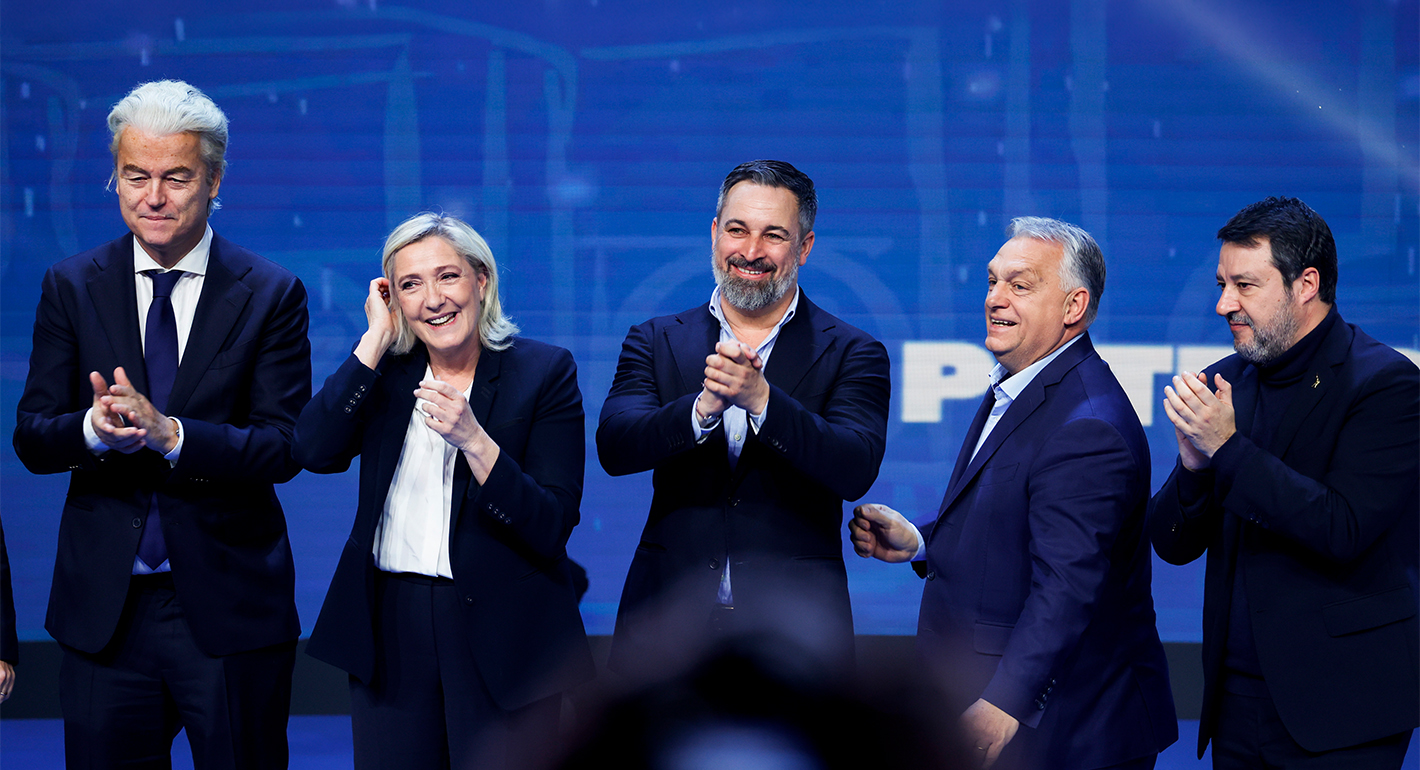
In supporting Europe’s far-right, MAGA and Russia both want the same thing: a weaker EU. Europe must defend itself without abandoning the openness these forces exploit.
Armida van Rij
As we close out another season of Strategic Europe, it is worth taking stock of the deep shifts underway.
Rym Momtaz
As the EU confronts profound challenges, several leaders have called for fundamental reform to the union’s model—but only modest, superficial changes have resulted. What if Europe really could be reimagined from zero today: What should such a redesigned European order look like?
Richard Youngs, ed.
Western Europe’s dual-use infrastructure melted down during its latest heat wave. If a predicted hot weather event can take the continent by surprise, what chance does it have to withstand unexpected geopolitical crises?
Rym Momtaz