

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "commentary",
  "blog": "Strategic Europe",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "Europe",
    "Asia"
  ],
  "topics": [
    "Economy",
    "EU",
    "Climate Change"
  ]
}
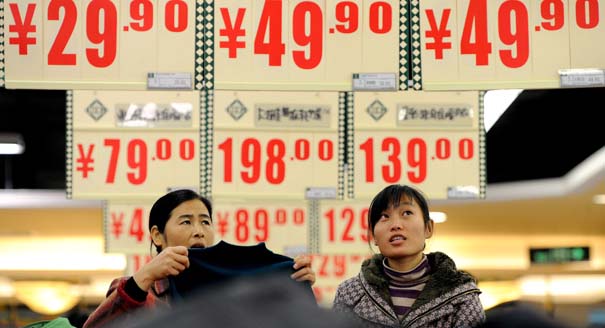
Source: Getty
Europeans are so concerned with the crises in peripheral economies that it will come as a surprise that we may be at the beginning of a developing crisis in China.
Europeans are so concerned with the crisis in Spain and in other peripheral economies that it will come as a surprise to many that we may be at the beginning of another developing crisis. This crisis is unfolding in China, a country that has long been seen, perhaps mistakenly, as a source of global stability and strength.
China’s problem is in some ways surprisingly similar to that of countries like Spain. For many years, low interest rates and rapid growth in loans led Spain into a consumption and investment boom. A large part of the investment boom, as always happens when loans grow too quickly, ended up being wasted in fraud and unprofitable projects.
China too, although for very different reasons, has had tremendous growth in the past decade, but unfortunately it turns out that much of this growth was also caused by wasted investment and fraud. For three decades Chinese growth was driven by very rapid loan growth at interest rates set artificially low by the central bank.
While this may have been a good strategy in the 1990s, when China needed more investment, in the past decade it has resulted in so much infrastructure, real estate, and manufacturing capacity that there is no way for China, and the world, to absorb it. As in Spain, when the money was spent it created rapid growth and great optimism, but now China’s banking system has to deal with a huge number of borrowers who have little capacity to repay the debt out of increased productivity.
But if China brings investment levels down, as Beijing clearly wants, this will bring growth down with it. This year, after growing 10 percent or more for many years, China’s official growth has slowed to 7.6 percent. Even this much lower number, however, underestimates the problem. Few economists believe the official numbers, with some estimates of China’s real economic growth at almost half that level.
The difficulty for China is that it is more reliant on investment to generate growth than any other country in history. It cannot continue to invest because this will lead to even more bad debt and capital losses, but it cannot stop investing because no other part of the economy is capable of generating sufficient growth.
As problems emerge, economists have sharply lowered their long-term growth expectations for China, from 8 to10 percent two years ago to 5 to7 percent today. But history suggests that when an economy like China’s changes its growth model, growth rates drop well below even the most pessimistic forecasts. In fact, I expect that over the next decade China will grow on average by no more than 3 to 4 percent a year.
This has important implications for the world. If Beijing responds to slower growth by protecting manufacturers and encouraging them to sell more abroad, global trade will suffer. If Beijing, however, responds to the slowdown by reforming the financial system and transferring wealth from the state to ordinary Chinese households—both of which are very difficult to do politically—it will create greater Chinese demand for global manufacturers.
For many years the world has been spending money foolishly. The financial crisis, which began in the United States, spread to Europe, and is now about to hit Asia, is simply the recognition of many years of bad policy. The United States is slowly and painfully emerging from its crisis, but Europeans should not be too quick to celebrate. There is still a lot more pain to come in Asia.

Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
Before the next wave of EU enlargement takes place, the union needs to grapple with thorny questions of how power is distributed among its members.
Emil Sondaj Hansen, Ditte Brasso Sørensen
A summer of escalation in the Black Sea has hurt Ukraine economically and is exacerbating world food security. A truce is needed—as is a broader reframing of Europe’s Ukraine strategy.
Thomas de Waal
Are Germany’s economic, industrial, and political struggles becoming a liability for the EU’s ability to rise to the geopolitical moment?
Rym Momtaz, ed.
European Commission President Ursula von der Leyen is about to give her annual address on the state of the EU. Here’s what she won’t—but should—say.
Rym Momtaz
The aftermath of the Ceuta crisis shows Europe has drawn the wrong lessons. Rather than doubling down on failed migration policies, the EU needs to address the underlying roots of such episodes.
Richard Youngs