

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy",
    "Foreign Policy"
  ]
}
Source: Getty
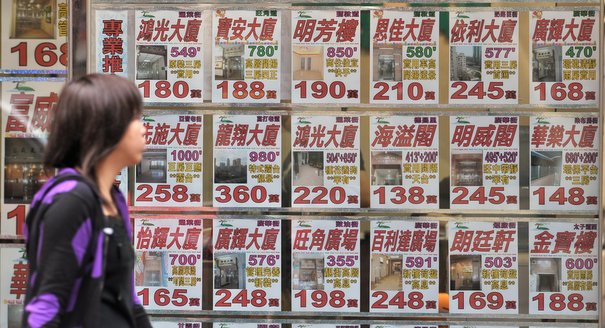
To rebalance an economy with excess capacity and to continue growing, China needs domestic consumption to grow much faster than domestic production for many years to come.
Source: Wall Street Journal Asia

To see why and how, start with an overview of China's current growth model. Policy makers have consistently encouraged high savings and investment for three decades. The result has been production capacity far in excess of Chinese consumers' willingness or ability to consume. So China has come to depend on exports, especially to the United States, to absorb that excess capacity -- something U.S. consumers were happy to do especially over the past decade. But the effects of jitters over the strength of that U.S. consumption shows that one of the most important reforms China needs now is to reduce its vulnerability to U.S. consumers by boosting consumption at home.
The problem is that government-directed or subsidized bank lending often has supported this buildup in capacity. This was especially the case in the 1990s. Chinese banks, acting mainly as policy arms of the government, poured loans into economically inefficient projects. One nearly inevitable consequence was a rise in nonperforming loans sharp enough to threaten the viability of the Chinese banking system. Credible estimates suggest that the losses on nonperforming loans exceeded 40%-50% of China's GDP.
Policy makers adopted a response to this that in retrospect undermined the growth of consumption. Beginning in the late 1990s and continuing for much of the past decade, bank regulators repaired bank balance sheets in part by using government resources to recapitalize the banks and in part by setting deposit rates much lower than lending rates. The spread between the two was kept wider than the market would otherwise have dictated to ensure high profits for the banks.
This hit consumption in two ways. By raising and transferring huge amounts of taxpayer resources to pay for expected losses, of course, the regulators captured a significant portion of Chinese income that could have gone to consumption. More significant may have been policies aimed at keeping corporate borrowing rates low to slow the growth rate of nonperforming loans, and deposit rates even lower to ensure bank profitability. In effect Chinese savers were forced into accepting brutally low returns on their savings to help recapitalize the banks via profits reaped on these wide spreads.
In the U.S., low rates would have rewarded consumption today over savings for tomorrow. But in China, where most savings are in the form of bank deposits and where earnings on savings are a significant portion of total household earnings, lowering deposit rates tends to increase the savings rate. As these and other policies boosted savings by constraining consumption, other policies, like those aimed at engineering massive loans to capital-intensive manufacturing at very low interest rates, forced rapid growth in domestic production. This aggravated the overcapacity problem that only domestic consumption can fix.
The difference now, as compared to the 1990s, is that the U.S. consumer won't be there to pick up the overcapacity this time. As American households repair their overextended balance sheets it is pretty clear that high and rising U.S. trade deficits are a thing of the past. To rebalance an economy with excess capacity and to continue growing, China needs domestic consumption to grow much faster than domestic production for many years.
This is why current stimulus policies are so risky. Although the surge in bank lending may temporarily cushion the impact of the global contraction on China's economy and employment, it will almost certainly lead to another surge in nonperforming loans. If this happens, in short order China will once again have to repair and rebuild bank balance sheets, either by directly recapitalizing the banks, or by forcing savers to subsidize profits, or, most likely, by a combination of the two.
These policies will limit future domestic consumption growth in the same way that they have in the past, and the greater the amount of nonperforming loans generated the tighter the constraints on consumption growth. And with China unable to rely on the U.S. to consume the gap between China's own consumption and its output, China will face GDP growth that is likely to be rigidly limited by the growth in domestic consumption.
In that case anything that limits future growth in Chinese consumption will necessarily limit Chinese economic growth. The explosion in new lending may do just that. In exchange for a temporary bounce, by encouraging a potential new round of massive capital misallocation China may have locked itself into many years of sub-par economic growth.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
Canadian Prime Minister Mark Carney has twice inspired praise for standing up to U.S. President Donald Trump: at the 2026 World Economic Forum in Davos and on Canada-U.S. trade negotiations. Is Carney showing a third way better than the EU has in dealing with the Trump administration?
Rym Momtaz, ed.
The EU’s responses to two recent incidents expose the gulf between European perceptions and capabilities. Unless the union can bridge that gap, it will never become a real geostrategic power.
Rym Momtaz
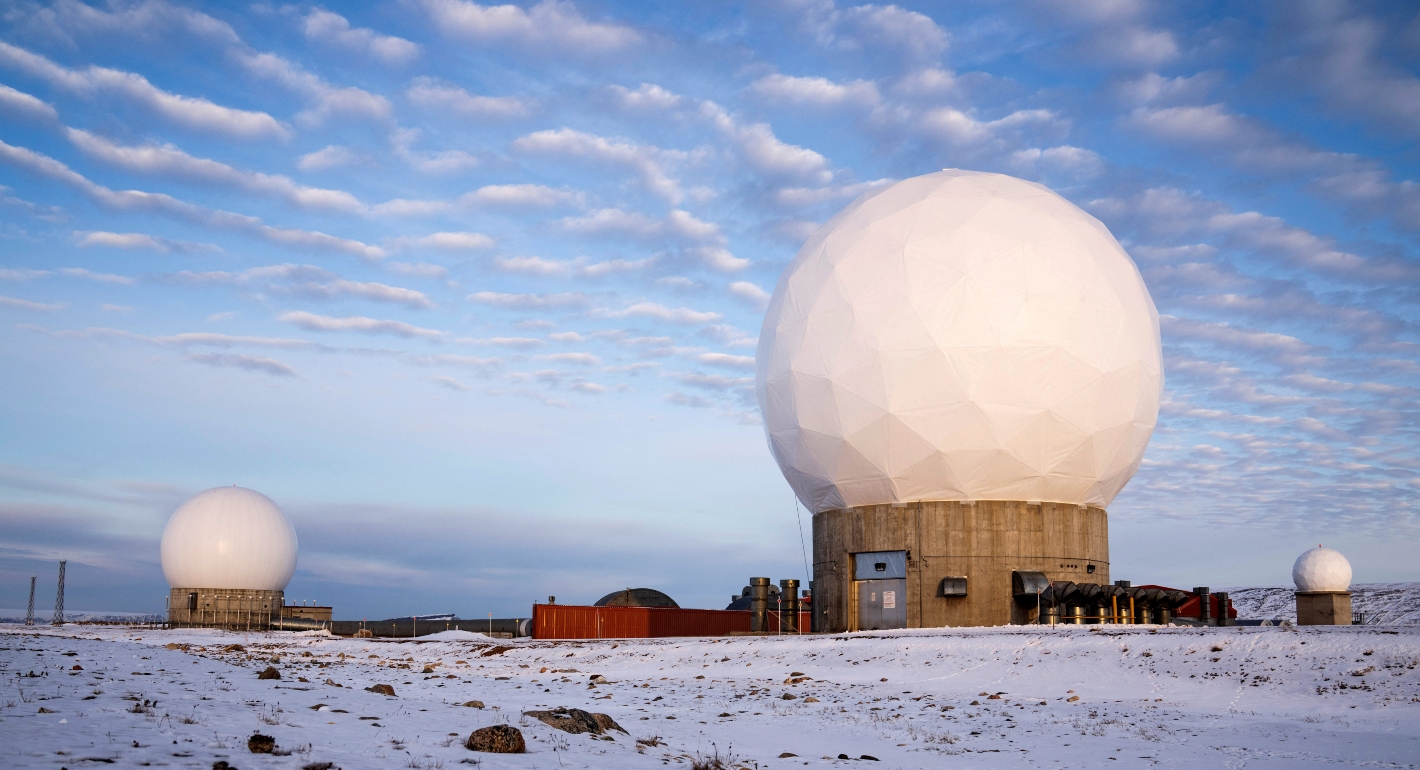
European states control several Overseas Countries and Territories around the world that carry strategic, economic, and environmental weight. As great powers challenge the rules-based order, defending them is a geopolitical imperative for Europe.
Marc Pierini
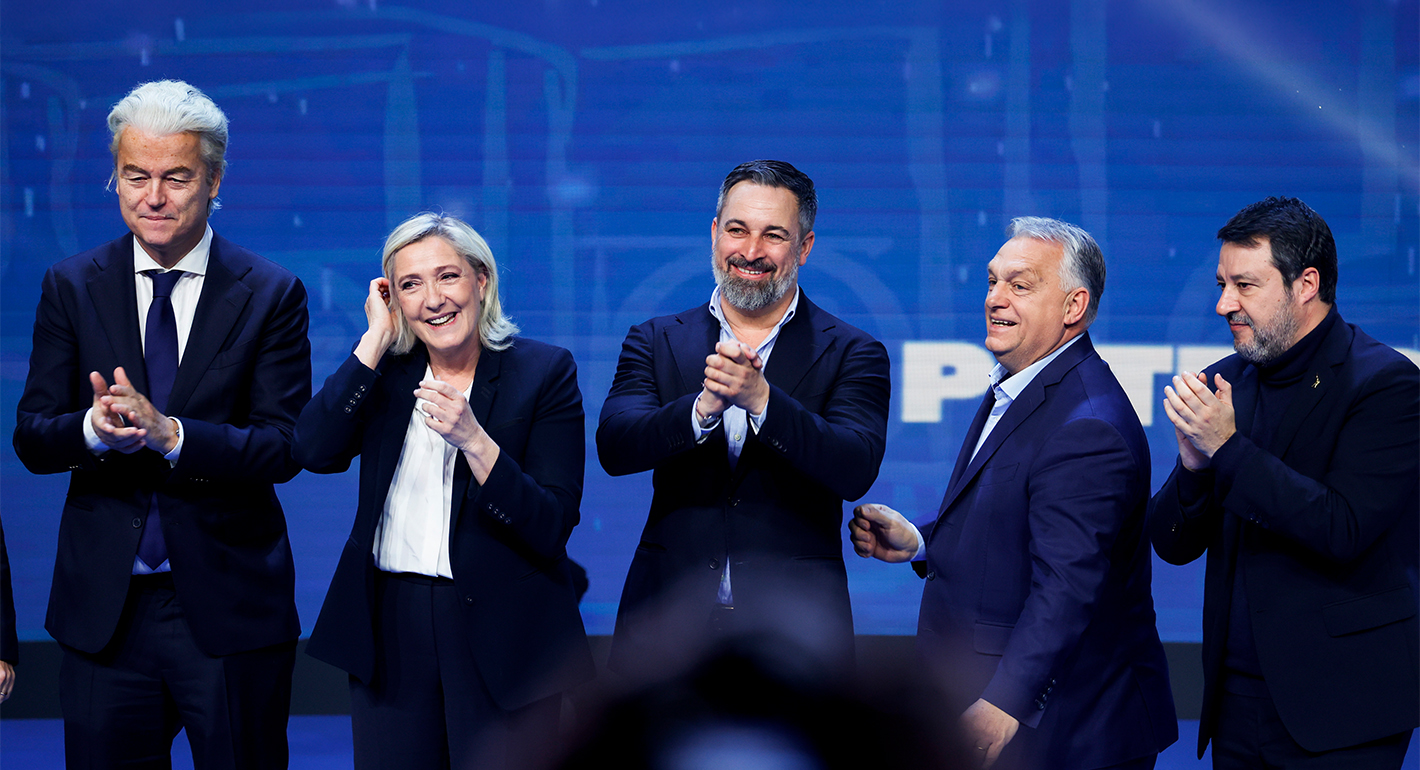
In supporting Europe’s far-right, MAGA and Russia both want the same thing: a weaker EU. Europe must defend itself without abandoning the openness these forces exploit.
Armida van Rij
As we close out another season of Strategic Europe, it is worth taking stock of the deep shifts underway.
Rym Momtaz