

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "North America",
    "United States"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
The U.S. trade deficit is not “caused” by Americans saving too little, nor will deficits disappear because Americans decide to spend less. Capital inflows determine U.S. savings rates.
Source: Bloomberg
Why does the U.S. run large trade deficits? As Harvard professor Martin Feldstein recently explained, the answer seems obvious: Americans save too little and consume too much. As a result, they must borrow from abroad to fund domestic consumption binges. Until Americans become a lot thriftier, Feldstein warns, U.S. trade deficits will remain high.
But this view is based on a model of global trade that has long been obsolete. In the 19th century, it's true, an unstable banking system left Americans saving far too little to fund the investment needs of a rapidly growing economy. Fortunately, that fast growth helped the U.S. offer the high returns needed to attract capital from Europe.
Today’s deficits are different. Since the 1980s, they've risen even when interest rates have fallen, suggesting foreigners are more eager to lend than Americans are to borrow. The need to deploy excess savings is driving countries to send capital to the U.S.
This flood of money has in turn suppressed U.S. savings. To understand why, it's important to note that for nearly a century U.S. financial markets -- the world's deepest and most flexible -- have automatically adjusted to resolve global savings imbalances. After the first and second world wars, for instance, when devastated economies were being rebuilt, they generated high savings as the U.S. became the leading capital exporter in the world. Over the subsequent five decades, when the world needed to sell goods and services, they produced low savings as U.S. trade deficits soared.
Consider what would happen today if the rest of the world suddenly increased the amount of capital it exported to the U.S. Would U.S. investment rise to accommodate the increased inflow? Certainly not. Interest rates have been close to zero for years, and yet U.S. businesses, flush with enormous amounts of cash, seem determined not to invest until profit opportunities reemerge. Simply making more foreign capital available is unlikely to change their minds.
This is what makes Feldstein’s model obsolete. It is true that in the 19th century, the U.S. was a net absorber of foreign capital, just as it is today, and that therefore domestic investment exceeded domestic savings, just as it does today. In the 19th century, however, because U.S. investment was constrained by the lack of capital, the inflow of foreign savings allowed capital-starved businesses and governments to invest more in infrastructure than they otherwise could. Foreign inflows pushed U.S. investment above U.S. savings.
This is no longer the case. In today’s world, the U.S. economy no longer faces a savings constraint. Businesses have more capital than they need, so additional foreign capital won't cause investment to increase. But if investment doesn’t increase in response to more foreign capital inflows, then of necessity savings must decline.
There are many ways foreign capital inflows can depress savings. They can inflate asset bubbles that encourage spending through wealth effects, for example, or they can strengthen the currency. They can reduce interest rates on consumer credit, or weaken lending standards, both of which boost borrowing by more profligate households. They can force up trade deficits that increase unemployment.
There are countless examples besides the U.S. in which this has happened. After Germany’s 2003 labor reforms caused German savings to rise, for example, German capital poured into the rest of Europe, quickly generating asset bubbles, real currency appreciation, low or even negative real interest rates, collapsing credit standards and eventually soaring unemployment. In every case, local savings rates collapsed, just as they had in the U.S.
There's a great irony here. One hundred years ago, Lenin described imperialism as an economic process in which the great industrial powers forced their colonies to sop up excess domestic savings and run trade deficits with the motherland. As economist Kenneth Austin noted in 2011, the U.S. now plays this role, absorbing nearly half of the world’s capital outflows, and so runs the corresponding trade deficit.
In today’s world, in other words, the U.S. trade deficit is not “caused” by Americans saving too little, nor will deficits disappear because Americans decide to spend less. As counter-intuitive as this may seem, foreigners, rather than U.S. thrift or profligacy, determine U.S. savings rates. If Americans tried to become thriftier, and foreign capital inflows remained at current levels, the economy would adjust to depress savings in some other way, probably through higher unemployment.
U.S. savings will automatically rise when foreign capital no longer pours into the country. Only then will the U.S. trade deficit decline.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
The domestic impacts of how long it is taking to end the war in Ukraine have pushed the French electorate to the political extremes and compromised the country’s diplomatic capacity.
Rym Momtaz
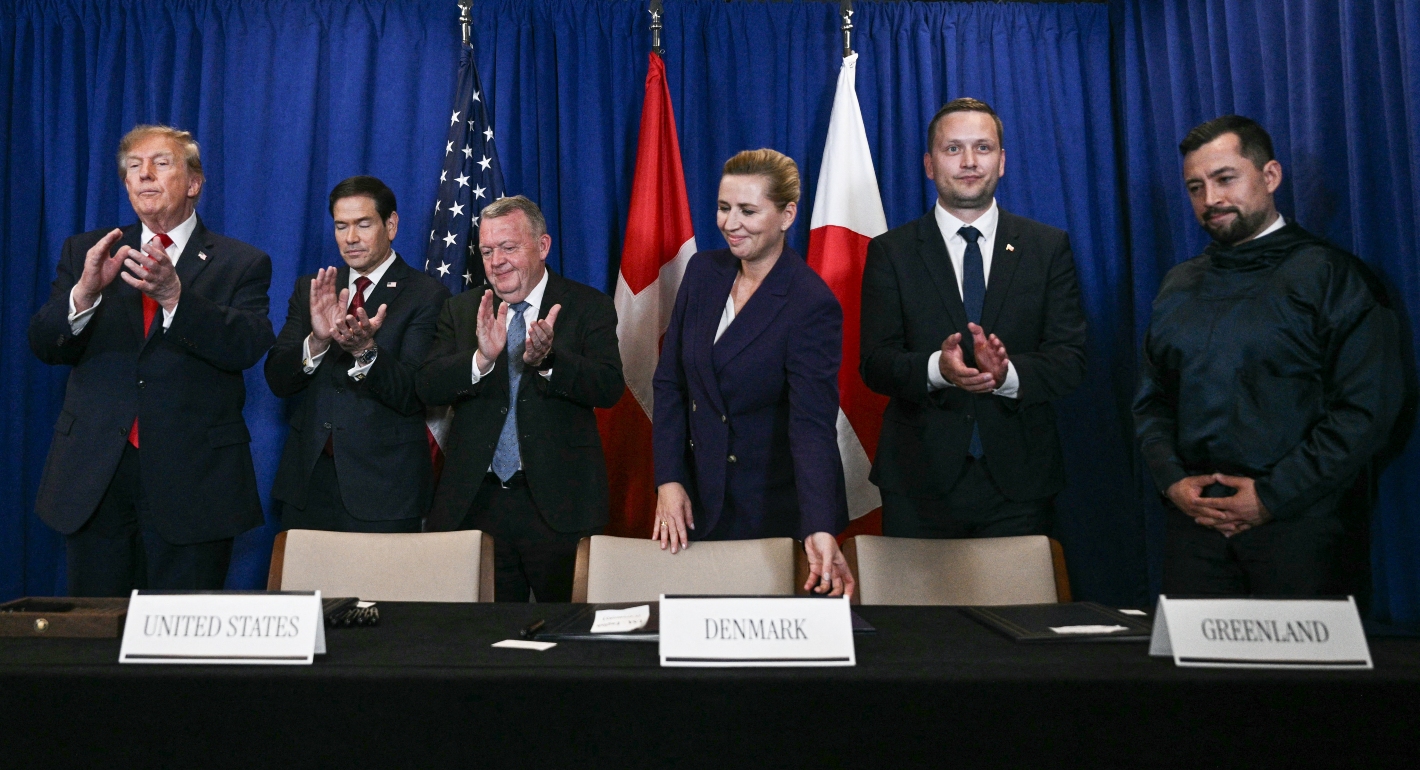
The new U.S.–Denmark–Greenland agreement will help Washington exert political, economic, and financial dominance under the guise of security. Yet, it acknowledged Copenhagen’s and Nuuk’s sovereignty on the island.
Marc Pierini
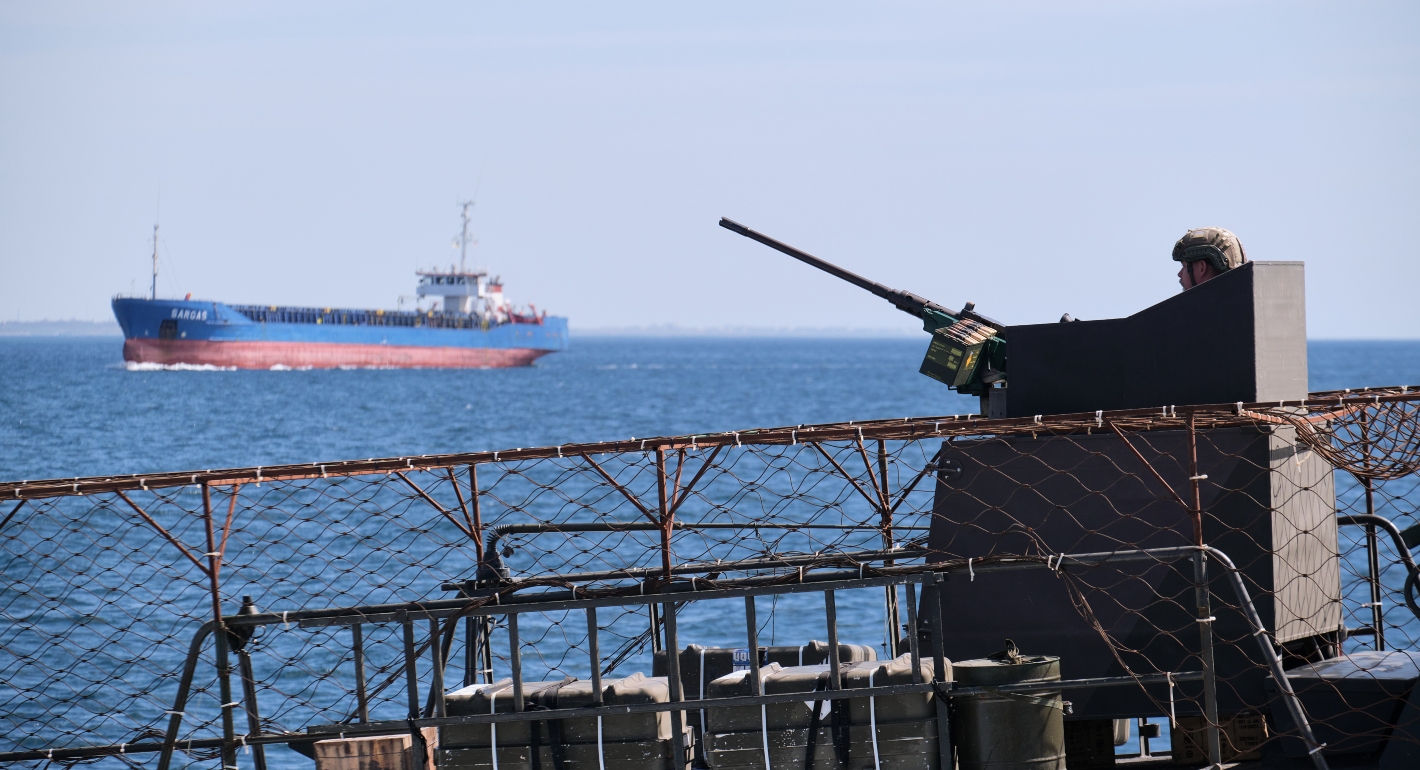
A summer of escalation in the Black Sea has hurt Ukraine economically and is exacerbating world food security. A truce is needed—as is a broader reframing of Europe’s Ukraine strategy.
Thomas de Waal
European Commission President Ursula von der Leyen is about to give her annual address on the state of the EU. Here’s what she won’t—but should—say.
Rym Momtaz
Radical-right parties are expected to do well in upcoming elections in four of the EU's biggest member states. If successful, they could prevent the union from addressing key challenges ahead.
Stefan Lehne