• Research
  • Strategic Europe
  • About
  • Experts
Carnegie Europe logoCarnegie lettermark logo
EUUkraine
  • Donate
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe",
    "Carnegie China"
  ],
  "collections": [
    "China’s Foreign Relations"
  ],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "Western Europe",
    "Asia",
    "Russia",
    "Europe",
    "India",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade",
    "Foreign Policy",
    "EU"
  ]
}
Source: Getty

In The Media
Carnegie China

A Bail-out by BRIC Nations Would Leave Europe Even Worse Off

Although tempting in the short run, a sudden influx of foreign capital into the European Union would raise both unemployment and debt without addressing the root of Europe's economic woes.

Link Copied
By Michael Pettis
Published on Sep 25, 2011

Source: Financial Times

As one European country after another finds its access to bond markets blocked, hopes are rising that the developing world might step in and relieve the crisis by buying the bonds European investors and official entities are unwilling or unable to buy. And why not? The Bric nations alone have more than $4,000bn in reserves between them. This can fund a lot of deficits.

But more foreign investment will not help Europe – and may make things worse. National governments, it turns out, are suffering from skewed incentives, so that actions benefiting individual countries in the short term may hurt Europe as a whole. If many governments take such action, everyone is worse off.
 
It would seem that a country struggling to fund itself at manageable interest rates should welcome any big new investor, no matter what his provenance, as a valuable resource.
 
But foreign investors are not the same as domestic investors. Any net increase in foreign purchases of euro-denominated local government bonds has an impact far beyond short-term funding. It also affects trade.
 
This is an automatic consequence of the way the balance of payments works. Today, Europe runs a current account surplus. By definition, this means that far from being starved of capital, European savings exceed European investment, and it exports the excess to the rest of the world.
 
Any big increase in the amount of official foreign capital directed at purchasing the bonds of struggling European governments – unless there were offsetting outflows – would inevitably cut the European trade surplus. What is more, if Europe began to import rather than export capital, the automatic corollary would be that its current account surplus would vanish and become a deficit.
 
How would this happen? There are many ways, but the most obvious is that as foreign central banks sell large amounts of dollars to buy euros, the euro strengthens against the dollar. As this happens, European manufacturers would become less competitive globally and their exports would drop.
 
This would cause a rise in European unemployment. It would also cause total European savings to decline as income drops more quickly than consumption. The only way to prevent a rise in unemployment is if all the new foreign funding was used to fund direct investment – which, given the need for transfer and welfare payments, is very unlikely.
 
In that case, the increase in foreign investment would simply be matched either by a reduction in domestic savings or an increase in domestic debt to counteract the rise in unemployment. So rather than easing the burden, foreign investment simply replaces domestic savings, undermines manufacturing and raises unemployment or debt.
 
Yet it is easy to see why desperate governments welcome official money from the developing world. European savers are increasingly refusing to provide financing, so any new source of funding is seen as a godsend.
 
But although afflicted European governments benefit in the very short term from the help of foreign investors, the adverse impact on European manufacturers and on European savings overall more than makes up for it. An increase in foreign funding creates slower growth and, with it, the need to increase fiscal deficits in order to prevent a rise in unemployment.
 
The idea that capital-rich Europe needs help from capital-poor Bric nations is absurd. European governments are unable to fund themselves not because Europe needs foreign capital but rather because many of them lack credibility.
Turning to foreign sources of capital will only aggravate the problem. Even assuming developing countries are willing to take on risks that Europeans find prohibitive, their help will not improve prospects for Europe. On the contrary, it will hurt growth prospects and make it harder than ever to resolve the debt crisis. The Bric nations should be exporting more demand, not more capital.
 
It is important that the desperate short-term funding needs of certain governments do not lead to a worse outcome overall for Europe. If Europeans do not want to fund credit-impaired governments, they should not ask foreigners to do so. Slower growth and foreign debt will not help resolve insolvency.

About the Author

Michael Pettis

Nonresident Senior Fellow, Carnegie China

Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets. 

    Recent Work

  • Commentary
    Who Paid for China’s Last Debt Cleanup, and Who Will Pay for the Next?

      Michael Pettis

  • Commentary
    Is China’s High-Quality Investment Output Economically Viable?

      Michael Pettis

Michael Pettis
Nonresident Senior Fellow, Carnegie China
Michael Pettis
EconomyTradeForeign PolicyEUWestern EuropeAsiaRussiaEuropeIndiaChina

Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
More Work from Carnegie Europe

  • Commentary
    Strategic Europe
    Taking the Pulse: Does the EU Have a Germany Problem?

    Are Germany’s economic, industrial, and political struggles becoming a liability for the EU’s ability to rise to the geopolitical moment?
      • Rym Momtaz

      Rym Momtaz, ed.

  • Commentary
    Strategic Europe
    The Speech Ursula von der Leyen Can’t Deliver

    European Commission President Ursula von der Leyen is about to give her annual address on the state of the EU. Here’s what she won’t—but should—say.

      • Rym Momtaz

      Rym Momtaz

  • Le Pen France Far Right
    Article
    How Europe’s 2027 Elections Could Test EU Governance

    Radical-right parties are expected to do well in upcoming elections in four of the EU's biggest member states. If successful, they could prevent the union from addressing key challenges ahead.
      Stefan Lehne
  • Commentary
    Strategic Europe
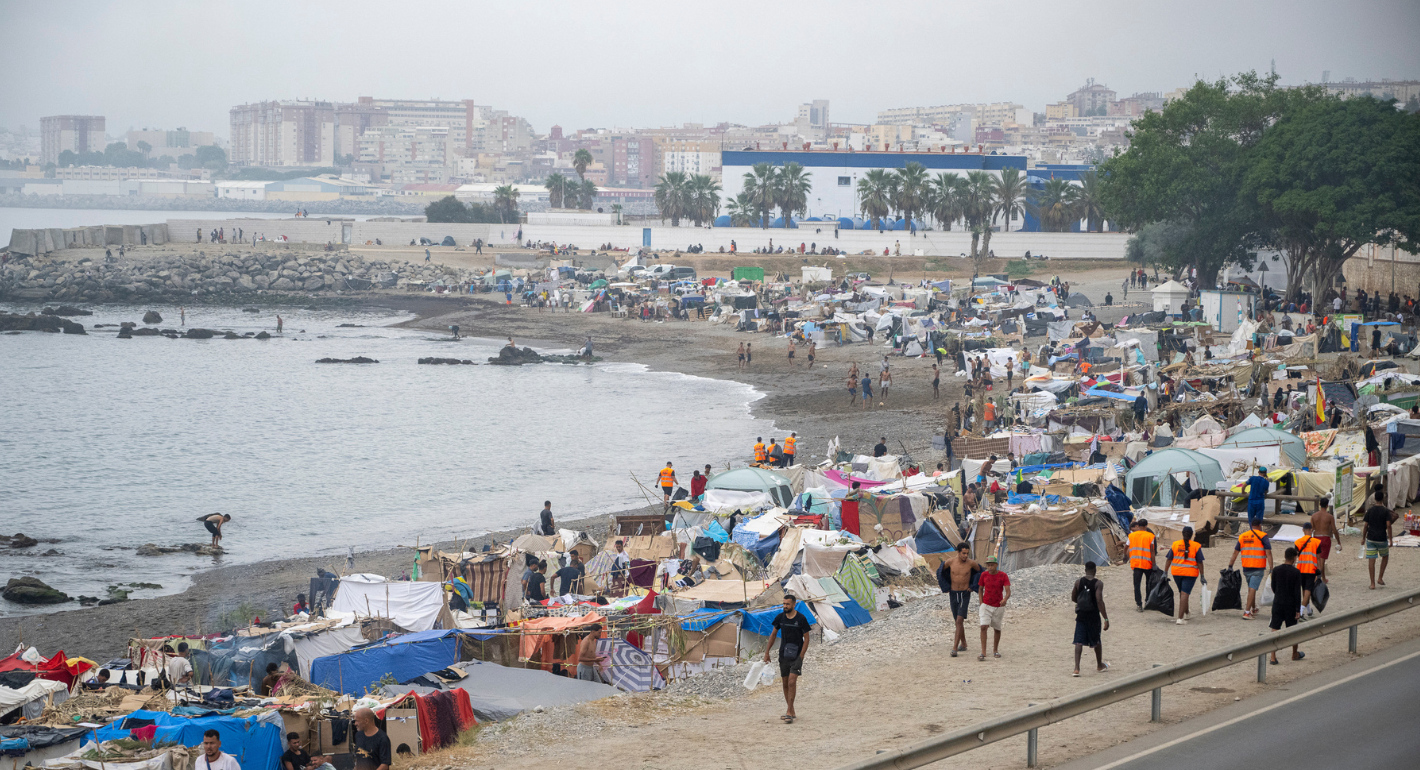
    Europe Fails to Learn the Lessons from Ceuta

    The aftermath of the Ceuta crisis shows Europe has drawn the wrong lessons. Rather than doubling down on failed migration policies, the EU needs to address the underlying roots of such episodes.
      Richard Youngs
  • Commentary
    Strategic Europe
    Germany’s Shattered Consensus

    An overwhelming victory by a far-right-wing party in a small state in eastern Germany will have major repercussions for Chancellor Friedrich Merz’s coalition.
      Judy Dempsey

Get more news and analysis from
Carnegie Europe
Carnegie Europe logo, white
Rue du Congrès, 151000 Brussels, Belgium
  • Research
  • Strategic Europe
  • About
  • Experts
  • Projects
  • Events
  • Contact
  • Careers
  • Privacy
  • For Media
  • Gender Equality Plan
Get more news and analysis from
Carnegie Europe
© 2026 Carnegie Endowment for International Peace. All rights reserved.