• Research
  • Emissary
  • About
  • Experts
Carnegie Global logoCarnegie lettermark logo
DemocracyIran
  • Donate
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China",
    "Western Europe",
    "Asia",
    "Europe",
    "North America"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty

In The Media

China Falls Victim to Greek Deficit Contagion

China’s steps to limit the damage from the Greek crisis will necessarily shift the brunt of the economic adjustment to other countries, unless the major trading powers can reach a burden-sharing agreement.

Link Copied
By Michael Pettis
Published on May 25, 2010
Program mobile hero image

Program

Asia

The Asia Program in Washington studies disruptive security, governance, and technological risks that threaten peace, growth, and opportunity in the Asia-Pacific region, including a focus on China, Japan, and the Korean peninsula.

Learn More

Source: Bloomberg

China Falls Victim to Greek Deficit ContagionChina is under growing pressure from Asia, Europe and the U.S. to revalue its currency. Until recently, it even looked like we were about to embark on a sustained process of yuan revaluation fairly soon.

The Greek crisis may have changed that. The 15 percent slide in the euro’s value against the yuan over the past six months has eroded Chinese competitiveness in the market of its largest trading partner: the European Union. More importantly, many trade-deficit countries in Europe -- such as Greece, Portugal and Spain -- are having difficulty financing themselves. Without net capital inflows, these countries can no longer run current-account shortfalls.
Not surprisingly, concerns in China about euro weakness have fueled calls for caution in any decision to realign the currency. The yuan has already strengthened significantly in trade-weighted terms and the potential contraction in demand from China’s main trading partner could put serious pressure on Chinese exporters even before a yuan revaluation.
 
One school of thought says to allow more yuan appreciation might create a drag on the economy, just as the Chinese government is trying to wean itself off a massive, and perhaps toxic, dose of investment. China will probably be hurt by the impact of the Greek crisis, and it should try to limit the pain.
 
The reasoning sounds plausible and even responsible, but it might only exacerbate the problem for China over a longer horizon by increasing trade tensions, which historically have been especially damaging to surplus countries.

Shift Burden

China plays a huge role in the global balance of payments. The Greek crisis and the larger European response will adversely affect existing trade. Limiting the damage for China necessarily means shifting the brunt of the adjustment to other countries.
 
Something similar happened in 1930 when the U.S., the leading trade-surplus nation at the time, foolishly used the Smoot-Hawley Tariff Act in an attempt to protect itself from the trade consequences of a collapse in the ability of European trade-deficit countries to finance themselves. U.S. protective measures implicitly required other deficit countries to absorb the full brunt of the impact, and this caused them to retaliate with tariffs, currency depreciations and import quotas.
 
What does all this have to do with Greece? For the foreseeable future, the major trade-deficit countries in Europe are going to find it very difficult to attract net new financing. At best they will be able, with official help, to refinance part of their existing liabilities.

New Capital Inflows

If they can’t attract net new capital inflows, they can’t run current-account deficits. There must be an equal, obverse reaction in the global balance of trade if there is a contraction in these large trade gaps, now equal to two-thirds that of the U.S. Either the trade surpluses of Germany and other European surplus countries must shrink by the same amount, or Europe’s overall surplus must expand by the same amount.
 
We will probably see a combination of the two, but a weaker euro -- as well as credit contraction, rising unemployment and a German reluctance to reverse policies that constrain domestic consumption -- will push most of the adjustment abroad via an expanding European current-account surplus.
 
If Europe’s current-account surplus grows, there must be a trade adjustment elsewhere. Either the current-account surplus of countries such as China and Japan must contract by the same amount, or the current-account deficits of countries such as the U.S. must grow (or some combination of both).

Trade Wars

Should China resist a contraction of the current-account surplus by postponing a yuan revaluation, lowering real interest rates (which have already declined this year), slowing credit contraction, and otherwise trying to maintain exports -- let alone grow them -- most of the adjustment will be shifted to countries that don’t intervene in trade directly. The most obvious are current-account-deficit countries.
 
This would cause a sharp increase in their current-account deficits, but these countries are likely to resist by intervening in trade themselves. Unlike many other countries, the U.S. has limited ability to use interest rates or currency intervention to affect trade, so it must use tariffs. As happened in the 1930s, this would probably set off higher tariffs in other countries that couldn’t regain export competitiveness through currency intervention.
 
The Greek crisis is forcing a much more rapid adjustment in trade than the world is easily able to absorb. As in the 1930s, each country seems eager to pursue policies to avoid adverse trade effects, but these policies can only work by pushing the burden of adjustment onto other, equally unwilling, entities.
 
The only way to overcome a beggar-thy-neighbor crisis is if the major trading powers -- the U.S., China, Japan, Germany and the EU -- work out a plan in which the adjustment process is slowed as much as possible and the burden is shared. Is it possible for them to come up with something fair and equitable? Perhaps not, but unless they try, the world will adjust much more painfully.

About the Author

Michael Pettis

Nonresident Senior Fellow, Carnegie China

Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets. 

    Recent Work

  • Commentary
    The Plaza Accord and Its Relevance for China

      Michael Pettis

  • Commentary
    Who Paid for China’s Last Debt Cleanup, and Who Will Pay for the Next?

      Michael Pettis

Michael Pettis
Nonresident Senior Fellow, Carnegie China
Michael Pettis
EconomyTradeEast AsiaChinaWestern EuropeAsiaEuropeNorth America

Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
More Work from Carnegie Endowment for International Peace

  • Commentary
    Turning Russian Assets into Financing for Ukraine Now

    Funding Ukraine remains a priority for European leaders. As Russia’s war of aggression heads into another winter, two feasible options to mobilize support for Kyiv should be fast-tracked.
      Vladyslav Rashkovan, Gregory P. Wilson
  • Commentary
    Carnegie Politika
    Stalled at the Front, Russia Seeks to Undermine Ukraine’s Economic Capacity

    Russian strikes are weakening the economy sustaining Ukraine’s war effort. Closing the growing funding gap will require more European support and politically contentious reforms in Kyiv.
      Balázs Jarábik
  • Commentary
    Strategic Europe
    The EU’s Middle-Power Puzzle

    While the EU and European governments are embracing the much-lauded middle-power moment, this entails three difficult conundrums.
      Richard Youngs
  • The Scramble for Europe. Russia, China, and Turkey Challenging Regional Order
    Book
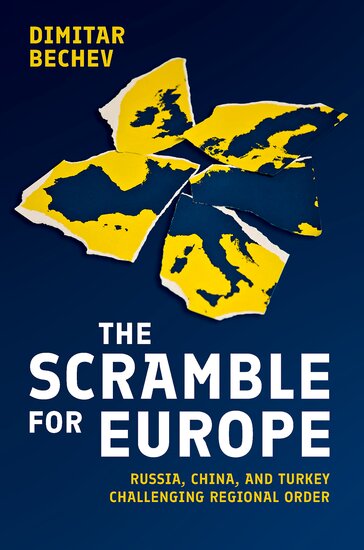
    The Scramble for Europe. Russia, China, and Turkey Challenging Regional Order

    Europe is facing rising populism internally as well as external pressures from Russia, China, Turkey, and the United States.
      Dimitar Bechev
  • European Union EU democracy Parliament citizens assembly
    Article
    Europe’s Tide of Citizen Assemblies: Unsung Success or Anticlimax?

    A notable degree of participative democracy has firmly arrived in Europe. But to have more far-reaching impact, democratic deliberation needs to move into a radically new phase.

      Richard Youngs

Get more news and analysis from
Carnegie Endowment for International Peace
Carnegie global logo, stacked
1779 Massachusetts Avenue NWWashington, DC, 20036-2103Phone: 202 483 7600
  • Research
  • Emissary
  • About
  • Experts
  • Donate
  • Programs
  • Events
  • Blogs
  • Podcasts
  • Contact
  • Annual Reports
  • Careers
  • Privacy
  • For Media
  • Government Resources
Get more news and analysis from
Carnegie Endowment for International Peace
© 2026 Carnegie Endowment for International Peace. All rights reserved.