

Commentary
It should address the shortcomings of previous crisis communication efforts and adapt to the demands of frontier AI.
Lucy Luo
{
  "authors": [
    "Uri Dadush",
    "Moisés Naím"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe"
  ],
  "collections": [
    "Transatlantic Cooperation"
  ],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "Western Europe",
    "France",
    "Germany",
    "Europe"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
When rethinking the institutional arrangements that underpin their monetary union, Europeans should take note of the California’s experience during the Great Recession.
Source: The Wall Street Journal

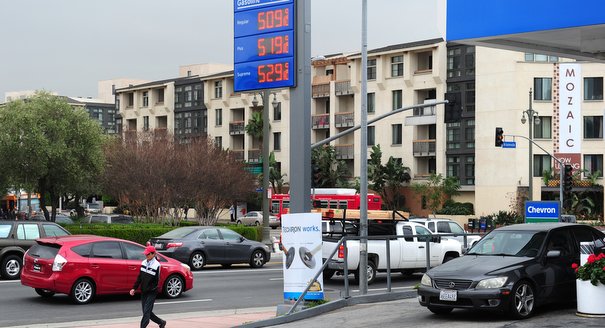
Paradoxically, despite this grim picture, it is actually Europe that should be envious of California. In fact, as countries in the euro area rethink the institutional arrangements that underpin their monetary union, there is a lot that Europeans could learn from the vicissitudes of America's Golden State.
This year's sovereign-debt crisis in the European periphery was triggered by the same global recession that engulfed California. The deeper roots of Europe's woes, however, lie in the loss of competitiveness of Greece, Ireland, Italy, Portugal, and Spain relative to Germany and the European core. With growth stifled and debt rising rapidly, the overextended governments in these countries have lost the confidence of financial markets.
In California, this has not happened. Prices and wages in California have moved roughly in line with those of the rest of the U.S., whereas Greek and Italian labor costs, for example, have risen by more than 25% relative to Germany's since they adopted the euro a decade ago. Financial markets are treating California—whose economy is larger than Spain's—far more leniently than they treat Europe's stricken countries. California's debt trades at spreads less than 1% higher than those of AAA states, whereas the bonds of the aforementioned countries trade at an average 3.5% spread vis-à-vis Germany.
What explains this difference in performance in the face of similar shocks? A more resilient institutional design that will allow California to emerge from its crisis stronger and faster than Europe's worst fiscal performers.
Despite its record budget shortfall, California's debt is now less than 5% of its GDP. In contrast, the five most troubled European nations have debt burdens that are the roughly same size of their economy. This is because federal spending accounts for about 55% of all public expenditures in California while the state's own spending is just 20% (the rest is spent by autonomous municipalities). So in California public spending footed by the state is only 7.9% of its GDP. In Europe, national spending typically represents about 50% of GDP while the budget of the European Commission—the closest analog to a European federal government—accounts for just 1%.
The U.S. federal system thus ensured that the safety nets available to Californians continued to operate throughout the crisis even as its residents contributed less to it. Europe's decentralized fiscal system guarantees no such stability. To be sure, a fiscally more centralized euro zone would also mean spreading countries' debts and risks around. But California's experience suggests that in a monetary union it is important to be able to pool risks: being part of a much larger entity that retains AAA rating and controls its currency reassures financial markets.
Importantly, state laws prevent California's debt from spiraling out of control and require a balanced budget. The Financial Stability Pact, Europe's closest equivalent, does not have the same force of law, and has been repeatedly and spectacularly flouted. And whereas in the United States there is no legal procedure to deal with the default of one of its states (it has never happened during the union's 234 years), financial markets expect that the process would be handled by the federal government and that it would be modeled after the procedure that already exists for municipal bankruptcy (Chapter 9 of the bankruptcy code). If a European country defaulted, there is complete uncertainty about who would be in charge or how creditors would be treated, which makes the risk all the more unattractive.
Crashing California is also better suited to deal with economic shocks thanks to its labor-market flexibility: Employers can more easily reduce payrolls in a downturn, and wages adjust more rapidly. Moreover, though labor mobility across state lines in the U.S. has declined with the recession, workers there still move much more fluidly than across European frontiers. Partly because both workers and firms are exposed to more competition, American firms have restructured faster: U.S. GDP has declined by only 1.2% from the second quarter of 2008 through the second quarter of 2010, while European GDP fell by 3.2%. Meanwhile, since bottoming out in the second quarter of 2009, investment in the U.S. grew by 23% through the second quarter of this year, compared to a rise of 8% in the EU.
Though a U.S.–like political union is not imaginable for Europe, the Continent can replicate some of the institutional arrangements that allowed California to better weather the storm. Improving labor-market flexibility, increasing the funds available to support stricken regions, adopting better rules that ensure and enforce fiscal discipline, and establishing a process to restructure sovereign debts are some of the innovations that would boost Europe's resiliency to future shocks.
Some of these measures are now being hotly debated by EU leaders. Even if they are adopted, they will not fully immunize Europe against economic shocks. But without these reforms, there will surely be more pain than there needs to be.
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Distinguished Fellow
Moisés Naím is a distinguished fellow at the Carnegie Endowment for International Peace, a best-selling author, and an internationally syndicated columnist.
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
It should address the shortcomings of previous crisis communication efforts and adapt to the demands of frontier AI.
Lucy Luo
If the Russian-speaking community in Latvia cannot articulate their interests without being seen as disloyal, they could end up embracing a pro-Kremlin agenda.
Sergejs Potapkins
Washington’s decision to support some UN functions while letting others wither is pulling the organization apart at the seams.
Stewart Patrick, Theodore Zaritsky
While there are notable demographic, economic, and geographic divides over AI, there is also substantial alignment between Republicans and Democrats.
Ian Klaus, Mark Baldassare, Rachel George, …
Are Germany’s economic, industrial, and political struggles becoming a liability for the EU’s ability to rise to the geopolitical moment?
Rym Momtaz, ed.