

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "East Asia",
    "China",
    "Asia"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
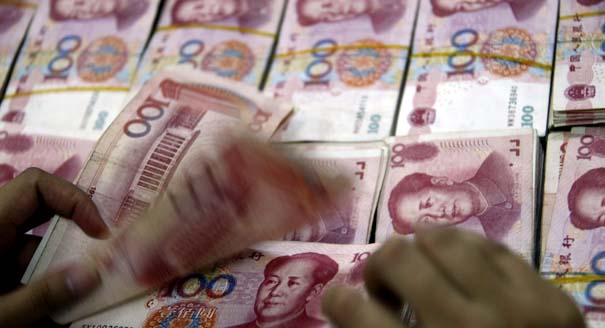
Chinese production continues to rise faster than domestic consumption, and even if China allows the renminbi to appreciate against the dollar, a rising trade surplus could lead to another increase in tensions.
Source: The New York Times

If the renminbi appreciates while real interest rates decline, as currently seems to be happening, the positive impact of a rising renminbi can be more than easily offset by the lower cost of capital for manufacturers. In this case we could easily see a rising renminbi coincide with a rising trade surplus, much as we saw from July 2005 onwards, when a rising renminbi and declining real interest rates, along with a vibrant U.S. consumer financing market, saw a surge in China’s trade surplus.
The recent thaw in trade tensions is likely to be very temporary. Ultimately what drives trade conflict is when the trade surplus country cannot adjust quickly, while high unemployment in the trade deficit country creates impatience for rapid change. China needs several years to make what will be a difficult adjustment toward a more balanced economy, but with high unemployment in the U.S. likely to persist for several more years, it is not clear that the U.S. will be willing to wait.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
For every ruble allocated to social policy, health, and education in 2027, double that amount is earmarked for the army, the police, and the security services.
Alexandra Prokopenko
The acknowledgment has sparked fears of a new arms race with China and Russia.

Chris O’Meara
Smaller powers cannot go it alone, but Canadian history shows that integration with the United States will not always be benign.
Paul Samson
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.
The summit may be remembered as a fatal blunder, when Washington, Beijing, and the AI industry collectively chose ceremony over action.
Jeffrey Prescott