

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
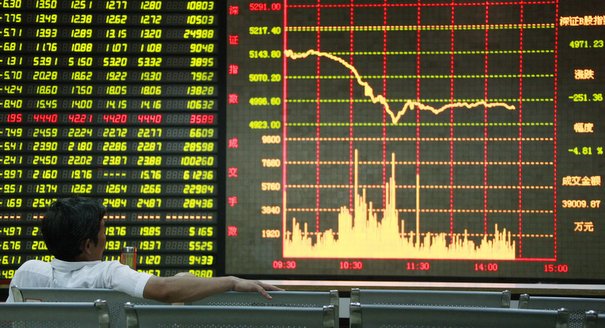
Since China’s stock market is driven mainly by speculators instead of fundamental or value investors, it does not serve as a good indicator of the country’s long-term growth prospects.
Source: Financial Times

Probably not. We normally assume that stock prices represent the market's best estimate of growth prospects, but this is not always the case. It depends on the mix of investment strategies that characterise the market. An efficient and well-functioning market is comprised largely of three types of investment strategies, often in combination, and each has a different role in determining how markets perform and what they tell us.
The first type, speculative strategies, requires information about changes in supply or demand factors that immediately affect prices. Speculators provide liquidity and disseminate information rapidly.
Arbitrage or relative value strategies exploit pricing inefficiencies in an asset class, ensuring markets provide clear pricing signals and function in unity, rather than as unlinked markets for each individual asset.
Finally, fundamental or value strategies involve buying assets to earn the economic value created. By taking capital from less profitable companies and channelling it to more profitable ones, this strategy - most famously characterised by the likes of Warren Buffett - gives the market its predictive ability. Fundamental and value investors turn the market into a machine that discounts long-term cash-flow expectations, and makes predictions about the future.
All three types of strategies require different kinds of information. In a well-functioning market these various strategies interact, ensuring that markets are reasonably liquid, reasonably consistent, and reasonably able to allocate capital efficiently. But from time to time, liquidity shocks or sharp increases in financial distress can undermine the value of certain information, especially information necessary to fundamental investors, and so shift the whole market into speculative mode.
Well-functioning financial markets can and do break down, but when they return to stability they do a fairly good job of allocating capital. But for a market to perform this role well, fundamental investors must have the necessary tools and information to profit from their capital allocation decision. The most basic requirements for fundamental investing are good macroeconomic data, accurate and intelligible financial statements, a stable regulatory framework, limited government intervention, and a clear understanding of the corporate governance structure.
China lacks all of these. Macroeconomic data is improving, but is still quite poor, which is perhaps to be expected in a country changing so rapidly. Financial statements are often questionable, in no small part because Chinese universities are unable to produce as many accountants as China needs. The regulatory framework is changing and evolving quickly, and often in unexpected ways, and the government has little hesitation in intervening in markets for policy reasons.
Most importantly the corporate governance structure is opaque. It is not clear whether managers act to maximise shareholder value, enterprise wealth, local employment, or other factors not subject to economic analysis. All this uncertainty means that fundamental investors must use too high a discount rate, in effect, pricing themselves out of the market except when it is trading at extraordinarily low levels.
In other words, in China it is very difficult to follow a fundamental investment strategy. Speculators, on the other hand, have a huge variety of tools at their disposal. Insider trading is common. Opaque corporate governance and ownership structures can cause sharp fluctuations in corporate behaviour. Illiquid and fragmented markets allow determined traders to cause large price movements. Regulations change often.
In addition, the single most important participant in the market, the government, often behaves in ways that are not subject to economic analysis. Take most fund managers out for late-night drinks and they will readily admit that the two most useful pieces of information that they crave is information about changes in underlying liquidity conditions and information about which way the government would like to see markets go.
A market driven mainly by speculators, and with little to no participation by fundamental or value investors, is not a market that spends much effort evaluating and discounting long-term growth prospects. It is driven largely by fads, technical factors, liquidity shifts, and government signalling. These markets may tell us many things, but they are not telling us much about growth prospects.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
It should address the shortcomings of previous crisis communication efforts and adapt to the demands of frontier AI.
Lucy Luo
China’s police training infrastructure construction projects provide benefits to recipient countries, promote China’s image as a major global security provider, and are likely to reinforce alignment between Beijing’s security priorities and those of countries in the Global South.
Cameron Waltz, Sheena Chestnut Greitens, Kim Nguyen, …
AI capabilities are moving fast. Most institutions—including governments—can’t keep up.
Anton Leicht, Scott Singer
The Bureau of Industry and Security needs to adjust its focus and practices to maintain its position as the U.S. government’s primary champion of international technological competition.
Geoffrey Irving
Depleted financial reserves and a shrinking tax base mean it is no longer possible to simultaneously deliver high defense spending, price stability, and economic growth.
Alexandra Prokopenko