

Commentary
Uri Dadush
{
  "authors": [
    "Uri Dadush"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "Western Europe",
    "France",
    "Germany",
    "North America"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}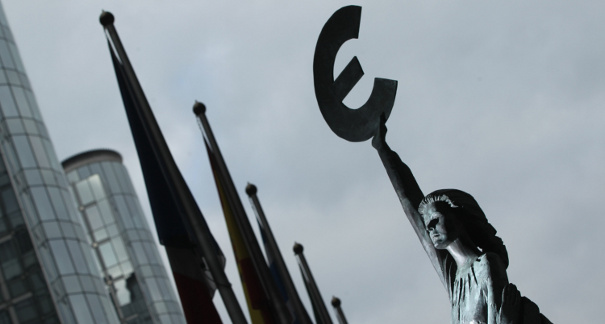
Source: Getty
The current Euro crisis will either cause the European monetary union to collapse, leading to sovereign defaults across Europe, or it will force European countries to take real steps toward fiscal union and tighter economic coordination.
Source: Il Sole

It will end soon in one of two ways: either the European monetary union will collapse and the crisis will morph into a bigger monster combining sovereign defaults in Europe and a Lehman-class global banking meltdown; or its protagonists will unequivocally signal that they will integrate more closely, by which I mean take a big step toward fiscal union and tighter economic coordination.
The break-up of the eurozone is not inevitable—far from it—but it may be imminent, a matter of months or weeks. Just as the shooting of an Archduke in Sarajevo once triggered the war no one wanted, it could be the surprising result of any number of possible accidents: a lethal confrontation between police and rioters in Salonikko, failure of a French bank, inability of Spain or Italy to place a big bond issue, or a “no” vote to yet another emergency rescue package in the Bundestag.
The hysterical reaction of global markets last week to both good news—the German Supreme Court’s half-hearted endorsement of the bailouts—and ostensibly bad news (I am not sure it was)—the resignation of inflation-super-hawk Jurgen Stark from the European Central Bank (ECB) executive committee—is an important signal of how finely poised the situation is.
The consequences of a break-up of the eurozone would be so calamitous that they require little elaboration. Two implications should be made crystal clear: it will be accompanied by large-scale public- and private-sector defaults as countries leaving the zone could not repay Euro and dollar loans with devalued currencies. And the effects would be global, as the continent accounts for several trillion dollars of direct and indirect exposures of banks in the rest of the world, including insurance the banks have written on its debts.
Such a “Clear and Present Danger” requires an immediate response. If the response is convincing, the Euro crisis as we know it could abate, though it will not be the end of the story. A protracted and painful adjustment in the periphery economies lies in store anyway. Moreover, a complex and drawn-out negotiation to reform the eurozone, one resembling the long run-up to the Euro’s creation, will still have to take place. And failure to move forward steadily on one or both fronts could trigger a relapse.
There are three main elements of a response that could retain the Euro and contain the crisis.
First, there should be a commitment to a much larger bailout fund that could credibly support Spain and Italy as well as other periphery countries if they need it (what former U.S. Treasury Secretary Hank Paulson called the “bazooka” that you will not have to use). Such a fund would be able to provide emergency financing of a sovereign or of individual banks. It would probably run into 2 trillion Euros ($2.8 trillion), of which the eurozone countries could credibly provide perhaps half—with contributions by the United States, Japan, China, the UK, and others, working bilaterally or through an expanded International Monetary Fund (IMF), providing the rest.
Second, procedures would be put in place for a managed exit from the eurozone of countries (Greece?) that are unable to service their debts and/or recover their competitiveness in a fixed exchange rate regime.
Third, the eurozone countries would commit to a fiscal union to start now and be completed by 2025. The fiscal union would include legally binding disciplines on the member states (such as a balanced budget provision in the constitution and ex ante peer review of budgets). It would involve issuance of Euro bonds equal to, say, half the new financing requirements of eurozone governments (about 850 billion Euro or $1.2 trillion a year) with corresponding proportional guarantees. Collateral could be posted in support of the fund. Part of the package would be to accord the ECB the flexibility to intervene as a last resort to support both member governments and the collective issuing Eurobonds.
The support of the non-eurozone countries would be conditional on progress on the second and third elements of the plan. The latter would require a change in the EU treaties and ratification by parliaments. Though this will take years to achieve, I believe that beginning the process now, together with the establishment of the larger bailout fund, would be enough to calm the waters.
No one should be under any doubt. These changes would move the EU toward a United States of Europe. But isn’t that what the creators of the Euro really wanted?
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Recent Work
Uri Dadush
Uri Dadush
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
For every ruble allocated to social policy, health, and education in 2027, double that amount is earmarked for the army, the police, and the security services.
Alexandra Prokopenko
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.
Cargo traffic through Russia’s Northern Sea Route has increased because of the disruption caused by the conflict in the Middle East, the Ukraine war, and U.S.-China tensions.
Mikhail Korostikov
The domestic impacts of how long it is taking to end the war in Ukraine have pushed the French electorate to the political extremes and compromised the country’s diplomatic capacity.
Rym Momtaz
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis