

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
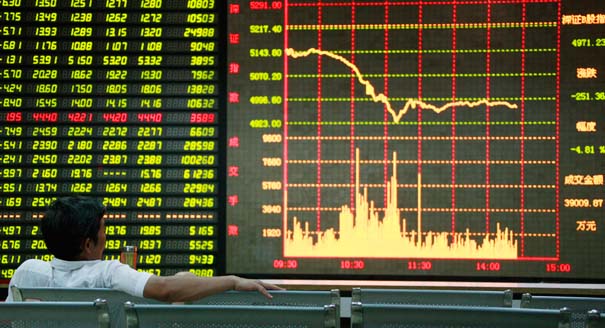
A lower growth expectation for China does not imply a gloomy picture. Rather, significantly reduced economic growth is a necessary consequence of China's much-needed rebalancing.
Source: Interpreter

Unfortunately, even just two or three years ago, when China hype was still cresting, any scepticism about Chinese growth branded one as outrageously pessimistic. This no longer seems to be the case.
Although my long-term growth expectations for China may be lower than that of most other economists, they don't imply a gloomy outcome for China. Much slower economic growth is a necessary consequence of China's rebalancing, but since rebalancing requires that household income growth exceed GDP growth by a substantial margin, the wealth of ordinary Chinese households can continue growing at enviable rates. This, and not reported GDP, is what really matters.Nor is rebalancing bad for the rest of the world (although hard commodity producers will suffer). The idea that China is the global engine of growth is based on confused arithmetic. What the world needs from China is not more growth. It needs more net demand, and a rebalancing China, even with much slower growth, will provide just that.
But even as conditions have changed it is still not clear that the China bulls understand how difficult rebalancing will be. Grenville has argued many times, for example, that it is much easier for Beijing to bring down the national savings rate than for the US to raise its savings rate. But this assumes that high Chinese savings rates are a cultural or personal choice that can be reversed with the right exhortations or administrative policies.
They aren't. I argue, as Grenville notes, that consumption-constraining policies are at the heart of the Chinese growth model, and reducing the savings rate can only happen with an elimination of those polices, which also means eliminating the policies that generated rapid Chinese growth (and even more rapid growth in Chinese debt). This cannot occur except at much lower growth rates.
The historical evidence supports this argument. Since 2005, when household consumption dropped to then-shocking level of 40% of GDP, Beijing has made reducing the savings rate an urgent priority. But in seven years the national savings rate has continued increasing, with household consumption now an astonishing 35% of GDP. The US, on the other hand, in spite of plenty of ham-fisted policies, has managed to raise its savings rate. This should at least suggest just how hard it is for Beijing to rebalance its economy away from excess savings.
Clearly I have a number of disagreements with the China bulls on the outlook for China's economy, but aside from those disagreements I think it is unfair of Grenville to suggest that I have 'tweaked' my long-term growth forecasts in response to a changing reality. This is simply not true and is based, I think, on a misunderstanding of what rebalancing in China means.
I have always argued that it is very unlikely that any real adjustment will start before 2013. The adjustment will be extremely difficult economically and even more so politically, and so is unlikely to happen before the new leadership takes power. From time to time on my blog I have sloppily used the phrase 'this decade' to describe the period of slower growth (I write a great deal on my blog and often quickly), but for Grenville to imply that my first projection was based on the calendar decade and only later, as I was proven wrong, did I push the date back, is wrong and, I think, unfair.
On the contrary, it has been the China bulls that have constantly revised their forecasts downwards. This happened as the Chinese economy progressively ran into the series of problems – rising debt, a declining consumption share, misallocated investment – that the sceptics warned about and that the bulls seemed unable to understand or foresee. In 2009, for example, it was hard to find many economists who did not expect medium to long-term GDP growth for China in the 8-10% range.
By now most analysts have sharply lowered their forecasts to 5-7%, with the bulls still at the high end, without however explaining what they know today that they didn't know in 2009. Debt has surged, it is true; the banking system is insolvent and increasingly illiquid; policy measures are losing traction; and wealthy Chinese are pulling money out of the country. But these were long predicted by the sceptics as automatic consequences of the investment-heavy growth model China had pursued for too long. None should have been unexpected.
Of course I think the current consensus of 5-7% average growth for the next ten years is still too high, and the historical precedents make it clear that we tend to underestimate sharply the cost of an adjustment of this nature (think for example of the USSR in the early the 1960s, Brazil in the late 1970s or Japan in the late 1980s, all of whom suffered far more difficult subsequent adjustments than even the sceptics had expected). Already this year Beijing has announced growth rates for China of 7-8%, but a large number of economists in China, based on alternative measures of economic activity, doubt the accuracy of the official numbers, with some arguing that real growth this year may be as low as half the posted rates.
I am not smart enough to say if they are right or wrong, but one way or the other I expect growth forecasts among China bulls to continue declining over the next few years. If, as I expect, Beijing seriously begins to rebalance its economy in 2013, I believe as I always have that the average annual growth rate over the following ten years will not exceed 3-4%.

Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
With the growth in points of friction between the great powers, organizations like the SCO will continue to play a role in the strategic adaptation of the smaller powers caught between them.
Temur Umarov
Amid celebrations of bilateral ties was a deeper focus on stability in the Middle East.
Amr Hamzawy
Xi, Putin, and other regional leaders are back-slapping in Bishkek, but the SCO has yet to answer the most serious questions about continental Asia's economic future.
Evan A. Feigenbaum
The conflict has sent economic and political shock waves through a country with no representation at the negotiating table—and Kenya is not alone.
Georgia Schaefer-Brown, Jane Munga
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.
Michael Pettis