

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}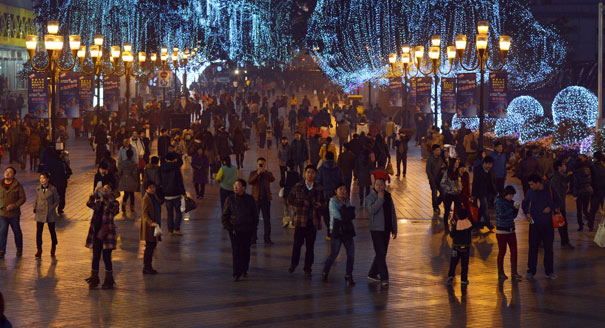
Source: Getty
China’s economy is at a turning point, shifting from growth driven by exports and investment toward growth based on household spending. Low growth is China’s new normal.
Source: Foreign Policy
In the months leading up to last week's liquidity crunch, in which the cost of short-term loans in China spiked and roiled global markets, most financial institutions had been lowering their growth forecasts for China. In mid-June, the World Bank revised its 2013 Chinese growth forecast from 8.4 percent to 7.7 percent; HSBC, Credit Suisse, and Goldman Sachs, among others, have also downgraded their Chinese growth forecasts several times over the last two years, as quarterly data have kept revealing lower-than-expected economic growth and higher-than-expected credit growth. Many banks now estimate around 7 percent to be the new normal.
But the banks' numbers are likely still too high. China's economy is at a turning point in its transformation from one driven by export and investment to one driven more by domestic household spending. Growth predictions are underestimating the impact of this shift.The recent liquidity crunch, and its cause, illustrates some of the difficulties China's economy will face in the future. Over the last two years, and especially in 2013, mainland corporations with offshore affiliates had been borrowing money abroad, faking trade invoices to import the money disguised as export revenues, and profitably relending it as Chinese yuan. As China receives more dollars from exports and foreign investment than it spends on imports and Chinese investment abroad, the People's Bank of China, the central bank, is forced to buy those excess dollars to maintain the value of the yuan. It does this by borrowing yuan in the domestic markets. But because its borrowing cost is greater than the return it receives when it invests those dollars in low-earning U.S. Treasury bonds, the central bank loses money as its reserves expand. Large companies bringing money into the mainland also force the central bank to expand the domestic money supply when it purchases the inflows, expanding the amount of credit in the system.
In May, however, the authorities began clamping down on the fake trade invoices, causing export revenues to decline. Foreign currency inflows into China dried up, as did the liquidity that had accommodated rapid credit growth. The combination of rapidly rising credit and slower growth in the money supply created enormous liquidity strains within the banking system. This is probably what caused last week's liquidity crunch and this week's market convulsions.
The surprising thing about this process has been the government's determination to see it through. Policymakers in Beijing have not backed down from the implications of rebalancing China's economy away from its addiction to investment and debt, even though economic growth is slowing and banks are pleading with the government to turn back on the liquidity spigots. Whereas the administration of President Xi Jinping's predecessor, Hu Jintao, never allowed growth to slow much before losing its nerve and increasing credit, Xi seems determined to stay the course.
There are two important lessons to be drawn from last week's panic. First, the central bank and the leadership in Beijing seem determined to try to get their arms around credit expansion -- even if that means, as it absolutely must, that growth will suffer and the banks will come under pressure. The extent of the freezing of the money markets on June 20 surprised many, including probably the central bank itself, but there will likely be more disruption in the markets over the next few years as Beijing tries to control what has become a runaway process.
Second, reining in credit won't be easy: the financial system and a whole host of borrowers -- including real estate developers, capital-intensive manufacturers, and local and municipal governments -- are too addicted to rapid credit expansion. Attempts to constrain credit growth will create significant strains in the financial sector, as borrowers find it hard to roll over debt that they cannot otherwise repay. Constraining credit growth will also mean a significant reduction in economic activity over the next decade.
Last week is a reminder that Beijing is playing a difficult game. The rest of the world should try to understand the stakes, and accommodate China's transition to a more sustainable growth model. As policymakers in China continue to try to restructure the economy away from reliance on massive, debt-fueling investment projects that create little value for the economy, the United States, Europe, and Japan must implement policies that reduce trade pressures. Any additional adverse trade conditions will further jeopardize the stability of China's economy, especially as lower trade surpluses and decreased foreign investment slow money creation by China's central bank. A trade war would clearly be devastating for Beijing's attempt to rebalance its economy and have potentially critical implications for global markets.
Regardless of what happens next, the consensus expectations that China's economy will grow at roughly 7 percent over the next few years can be safely ignored. Growth driven by consumption, instead of trade and investment, is alone sufficient to grow China's GDP by 3 to 4 percent annually. But it is not clear that consumption can be sustained if investment growth levels are sharply reduced. If Beijing can successfully manage the employment consequences of decreased investment growth, perhaps it can keep consumption growing at current levels. But that's a tricky proposition.
It's likely that the days of the super-powered Chinese economy are over. Instead, Beijing must content itself with grinding its way through the debt that has accumulated over the past decade.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Russia’s banking sector is sinking ever deeper into a crisis that the authorities are simply managing rather than trying to fix.
Alexander Kolyandr, Alexandra Prokopenko
Even if the administration maintains its broader trade policy, it should use tariffs more strategically and work with U.S. partners, not against them.
Barbara Weisel
Safa Naser
Two decades since Washington elevated West African oil as a strategic priority, the frontier has reemerged as a promising alternative for U.S. energy security.

Judd Devermont, Gabrielle Posner
Geoengineering is becoming a geopolitical question as much as a climate one. The way states and the private sector pursue these technologies, assess risks, and drive research increasingly appears focused on gaining a strategic edge. In a field where governance in lagging behind, Europe should keep track of the geopolitical implications if it is to develop effective regulatory frameworks.
Olivia Lazard, ed.