

Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Russia Eurasia Center"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}
Source: Getty
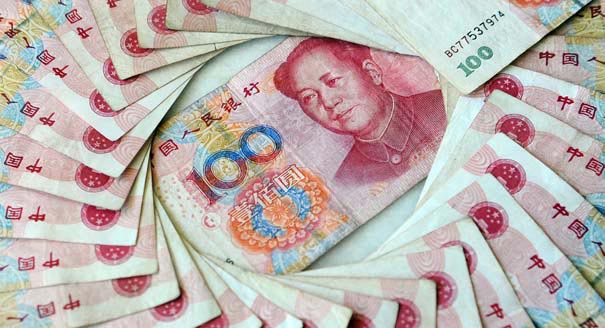
Given China’s surplus economy, a weak currency could undermine growth and incite a trade war.
Source: Wall Street Journal
China’s central-bank governor, Zhou Xiaochuan, consistently denies that the country can devalue its way to faster growth, arguing that a falling yuan would harm the economy. From a purely economic point of view, Mr. Zhou is right. But that hasn’t stopped a growing number of analysts from calling for a substantially weaker currency.
The arguments in favor of devaluation are straightforward. China’s economy is slowing sharply, in part because of declining exports. After many years of current- and capital-account surpluses, the past two years have seen a large balance-of-payments deficit, and China’s central bank had to intervene heavily to support the yuan.Developing economies usually respond in such situations by devaluing their currencies. Supporters of devaluation claim that China should do the same to regain export competitiveness and reverse capital outflows.
This comparison is mistaken. China is the world’s second-largest economy and runs the second-largest trade surplus in history. Developing economies that devalued successfully were much smaller, which made it easier for the world to absorb their export surge. They also devalued only after their overvalued currencies had caused persistently large deficits.
In contrast, the yuan is not overvalued. In fact it is undervalued, as Governor Zhou all but acknowledged in an interview with China’s financial magazine Caixin three months ago.
The current account shows why: China enjoys low unemployment and brisk wage growth. Economic activity is growing 6% to 7% while debt is growing two to three times faster. China’s trade partners, on the other hand, suffer high unemployment and can barely eke out 1% or 2% growth.
Normally China would import far more than it exports. But rather than running large deficits, China has large surpluses. While its exports declined last year, global exports declined even more. China is gaining export market share and its trade surplus is growing, neither of which suggests an overvalued currency.
To keep the yuan from falling the central bank has spent about $1 trillion of its $4 trillion in reserves. But China’s shrinking reserves are driven by net capital outflows. If money went abroad mainly because Chinese investors think foreign assets are relatively cheap, a weaker yuan would reduce capital leaving China by making foreign assets more expensive. But this isn’t the reason for the capital outflows.
Money leaves China partly to buy strategic assets, partly to hedge against rising political and financial uncertainty, and partly to reverse the notorious “arbitrage” of earlier years. From 2012 to 2014, some $1 trillion poured into China to speculate on an appreciating, higher-yielding yuan.
Chinese investors don’t care about the relative value of the yuan. Rather than restrain them, a devalued yuan might actually speed up their exit. This is what happened immediately after the change in the currency regime in August. Capital restrictions had to be tightened significantly to prevent even more money from leaving.
The main reason to oppose devaluation is that rather than boost growth, a weaker currency makes a surplus economy more precarious. Instead of changing relative prices, devaluation shifts income from consumption to savings.
In deficit countries—where savings are insufficient to fund investment—slowing growth scares off foreign inflows, causing investment to decline, which slows the economy further. By redirecting income from consumption toward savings, devaluation reduces dependence on foreign capital and keeps investment from dropping.
Surplus countries, however, don’t suffer from insufficient savings, and China’s savings are excessive. Yuan devaluation would simply reduce already-low domestic consumption and increase China’s reliance on investment and exports. This happened in Japan, where a substantially weaker yen further diminished consumption without kick-starting growth. For surplus countries, devaluation replaces sustainable demand—namely consumption—with the unsustainable demand of investment and trade surpluses.
In a global economy with growing trade tensions and weak demand, a devaluation that substantially boosts China’s trade surplus may ignite a trade war. If weak currencies only benefit much smaller economies with overvalued currencies and large current account deficits, it is hard to imagine why Beijing would risk devaluation.
The past three years have been terrible for international trade. China isn’t the only major economy suffering from weak domestic demand, but it has behaved far more responsibly than Europe and Japan, which have forced their adjustment costs onto the rest of the world. Maintaining the yuan’s value has been good for both China and the world. It wouldn’t help for Beijing to change strategy.
This article was originally published by the Wall Street Journal.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
For every ruble allocated to social policy, health, and education in 2027, double that amount is earmarked for the army, the police, and the security services.
Alexandra Prokopenko
The acknowledgment has sparked fears of a new arms race with China and Russia.

Chris O’Meara
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.
The summit may be remembered as a fatal blunder, when Washington, Beijing, and the AI industry collectively chose ceremony over action.
Jeffrey Prescott
Cargo traffic through Russia’s Northern Sea Route has increased because of the disruption caused by the conflict in the Middle East, the Ukraine war, and U.S.-China tensions.
Mikhail Korostikov