

Commentary
Uri Dadush
{
  "authors": [
    "Uri Dadush"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Europe"
  ],
  "collections": [
    "Transatlantic Cooperation",
    "Brexit and UK Politics"
  ],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "North America",
    "United States",
    "Western Europe",
    "United Kingdom",
    "France",
    "Germany",
    "Europe"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
The economies of the United States and Europe are tightly linked via trade, investment, and financial markets. If the Euro crisis spreads, U.S. banking and export sectors will suffer.
Source: Council on Foreign Relations

In fact, the euro crisis has already had a significant impact on the U.S. economy: Since late November, the euro has lost 17 percent of its value vis-à-vis the dollar, making U.S. exports less competitive, even as the Obama administration's goal is to double exports in five years. U.S. exports are also adversely affected by Europe's sluggish recovery--in the first quarter, European GDP was up only 0.3 percent on the same quarter a year before, compared to a 2.5 percent rise in the United States and 11.9 percent in China. U.S. investors in Europe should expect to take large balance sheet and income translation losses due to the lower euro.
But the most important effects of the euro crisis on the United States will operate not through the real channels of trade and foreign direct investment, but through broader effects on confidence and banks. Stock market volatility (as measured by the VIX index) has more than doubled in the last two months, and the confidence that banks have in lending to each other--measured by the TED spread (the difference between three-month inter-bank lending rate and the yield on Treasury Bills) was as wide as 30.8 basis points at the end of last week, a nine-month high, up from this year's low of 10.6 basis points in March.
This is against a backdrop of a crisis largely confined thus far to Greece, a country accounting for a mere 2.6 percent of the eurozone GDP. Imagine what would happen if the crisis spread to Spain or Italy, countries five or six times larger. Though the exposure of U.S. banks to the most vulnerable countries in Europe is limited--about $176 billion, or 5 percent of their total foreign exposure--the indirect exposure is much larger, since U.S. banks do business with all the large international banks, which are themselves exposed to these vulnerable countries.
A spreading euro crisis would hurt U.S. interests in another way. Although U.S. government debt may increase in popularity initially due to a safe haven effect, a spreading crisis would likely eventually place the spotlight on rising U.S. debt as well, aggravating the country's unstable debt dynamics.
Originally published by the Council on Foreign Relations, May 14, 2010
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Recent Work
Uri Dadush
Uri Dadush
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
Radical-right parties are expected to do well in upcoming elections in four of the EU's biggest member states. If successful, they could prevent the union from addressing key challenges ahead.
Stefan Lehne
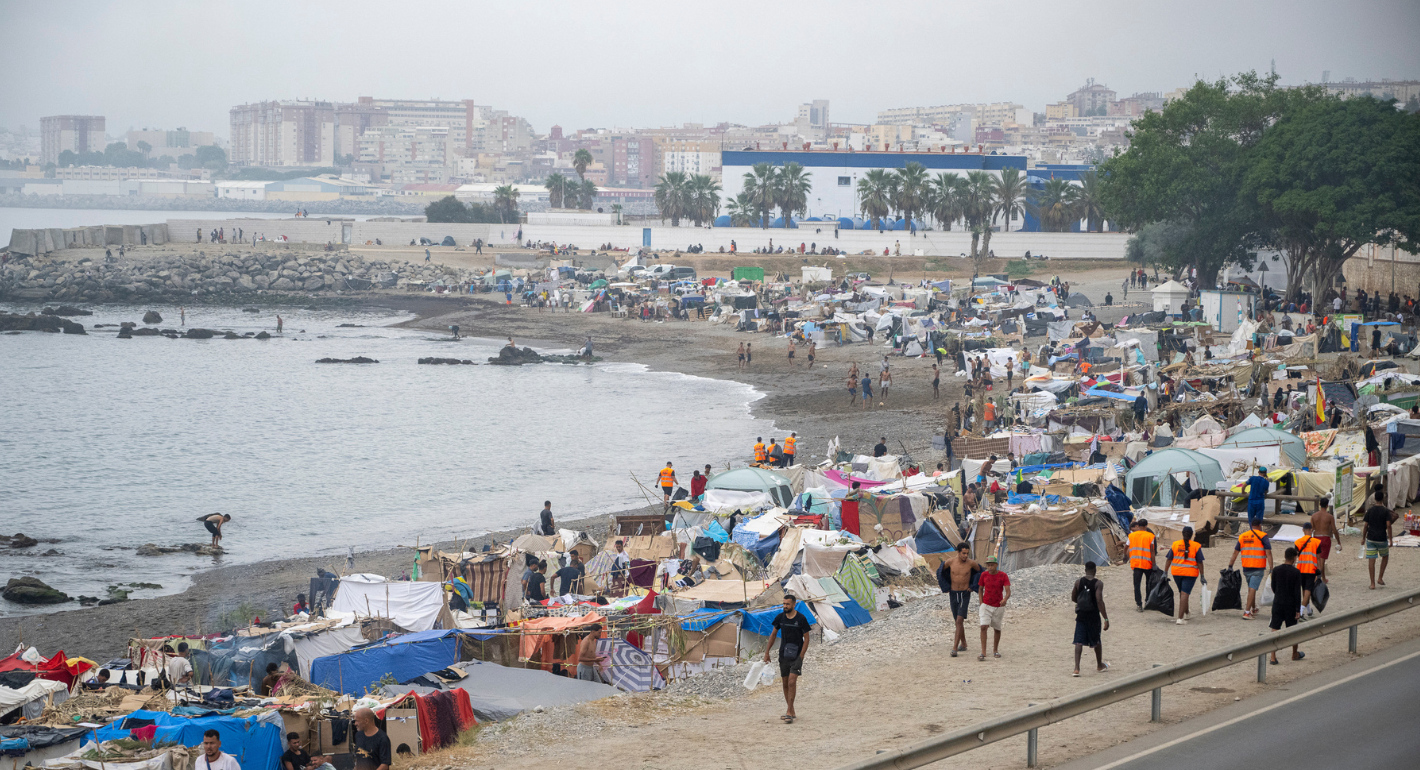
The aftermath of the Ceuta crisis shows Europe has drawn the wrong lessons. Rather than doubling down on failed migration policies, the EU needs to address the underlying roots of such episodes.
Richard Youngs
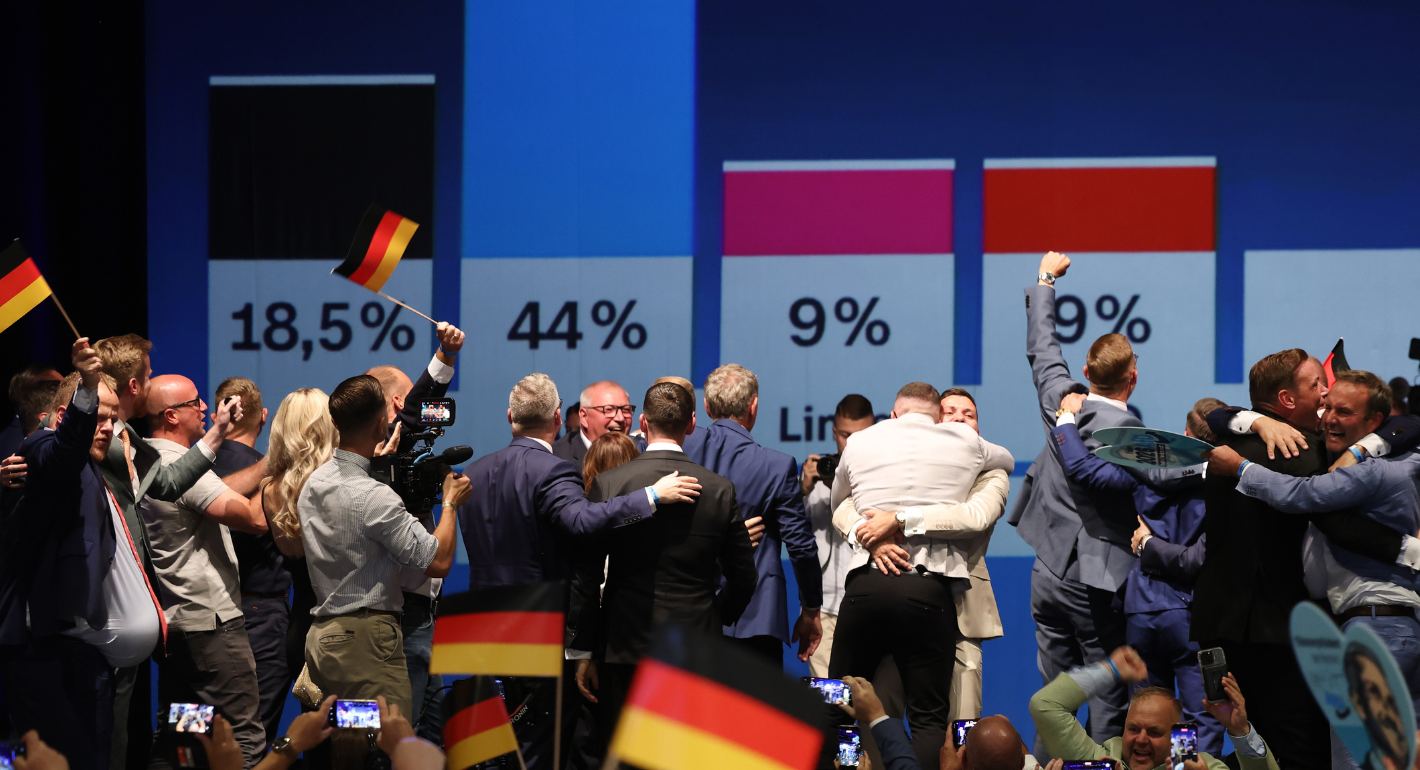
An overwhelming victory by a far-right-wing party in a small state in eastern Germany will have major repercussions for Chancellor Friedrich Merz’s coalition.
Judy Dempsey
Canadian Prime Minister Mark Carney has twice inspired praise for standing up to U.S. President Donald Trump: at the 2026 World Economic Forum in Davos and on Canada-U.S. trade negotiations. Is Carney showing a third way better than the EU has in dealing with the Trump administration?
Rym Momtaz, ed.
The EU’s responses to two recent incidents expose the gulf between European perceptions and capabilities. Unless the union can bridge that gap, it will never become a real geostrategic power.
Rym Momtaz