

Commentary
Amid celebrations of bilateral ties was a deeper focus on stability in the Middle East.
Amr Hamzawy
Source: Getty
Encouraging developments in new jobless claims, non-manufacturing surveys, and industrial output lifted hopes of recovery; however, persistently weak job markets setback consumer confidence.
The Real Economy: Output, GDP, and Inflation
Encouraging developments in new jobless claims, non-manufacturing surveys, and industrial output lifted hopes of recovery; however, persistently weak job markets setback consumer confidence.
Initial jobless claims in the U.S. fell to 565,000 in the latest week from a revised 617,000 the previous week, the first week claims fell below 600,000 since January. The pace of contraction in the non-manufacturing sector also eased, indicating some stabilization in consumer spending. The Institute for Supply Management’s non-manufacturing PMI rose to 47 in June from 44 in May, reaching a 9 month high. The trade deficit narrowed 9.7 percent in May to $26 billion, the lowest level in 10 years. Exports were up 1.6 percent to $123.3 billion while imports continued to decline for the tenth straight month.
Yet, despite these improvements, consumer sentiment decreased on concerns of a rising U.S. unemployment level. The University of Michigan index of consumer sentiment fell to its lowest level since March, dropping to 64.6 in July, down from 70.8 in June.
A recent surge in industrial output spurred hopes of recovery in the euro-zone. Industrial production (IP) in Germany jumped 3.7 percent in May from a month earlier, the fastest rate in nearly 16 years. Auto parts manufacturers had been the drivers of output growth, spurred by the government's car-scrapping premium, which has raised domestic demand for vehicles. Meanwhile, new industrial orders rose 4.4 percent (m/m) in June. The improvement in industrial output was not confined to just Germany. French IP climbed 2.6 percent in May, the first time in nine months. Italian IP remained unchanged in May and the 1.1 percent increase in April was revised up to 1.2 percent.
Car sales in China surged 36 percent (y/y) in June, the fourth consecutive month that car sales exceeded 1 million units helped by tax breaks on small cars and subsidies for vehicle purchases in rural areas. In contrast, car sales in Russia shrank 56 percent in June (y/y), while sales in India rose 7.8 percent(y/y) in the same period.
Economic Policy
As the global economy begins to show early signs of stabilization, central banks around the world continued to keep their rates unchanged. Central banks in Australia, Korea, and the UK left their target rates unchanged once again.
China’s central bank announced plans to resume monetary tightening with the auction of $7.3 billion in bills, the first issue since sales were suspended in mid-November. India unveiled its budget for 2009-10, which will push the fiscal deficit to 6.8 percent of GDP, and announced plans to borrow a record $93 billion to fund the shortfall.
The Group of Eight (G8) summit ended last week with a pledge to mobilize $20 billion over the next three years to increase food production in developing nations, up from an initial $15 billion target.
Financial markets
Global equity markets fell last week on fears that the economic recovery will be slower than anticipated and corporate earnings will remain poor. For the week, the Dow lost 1.6 percent, the S&P 500 index slid 1.9 percent, and the NASDAQ fell 2.3 percent. The Dow and the S&P 500 have now fallen for fourth straight weeks.
In Europe, the UK FTSE 100, the German DAX, and the French CAC fell by 2.6 percent, 2.8 percent and 4.4 percent respectively. In Asia, the Nikkei 225 was down by 5.4 percent.
In currency markets, Japanese yen strengthened against major currencies. It rose to a five-month high against the U.S. dollar, as U.S. equities fell and IMF upgraded Japan's growth forecast. The yen rose 4.1 percent and 3.8 percent against the euro and the dollar, respectively. The dollar closed the week only marginally firmer against the euro and UK pound. The dollar advanced 0.4 percent against the euro to close at $1.39.
Over the past week, yields of major sovereign bond markets extended the previous week’s declines. The yield on U.S.10-year treasury bills fell to 3.3 percent, down 20 basis points over the week. Japan’s 10-year bond yield fell modesty by 4 basis points. The UK 10-year bond yield was unchanged at 3.74 percent.
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
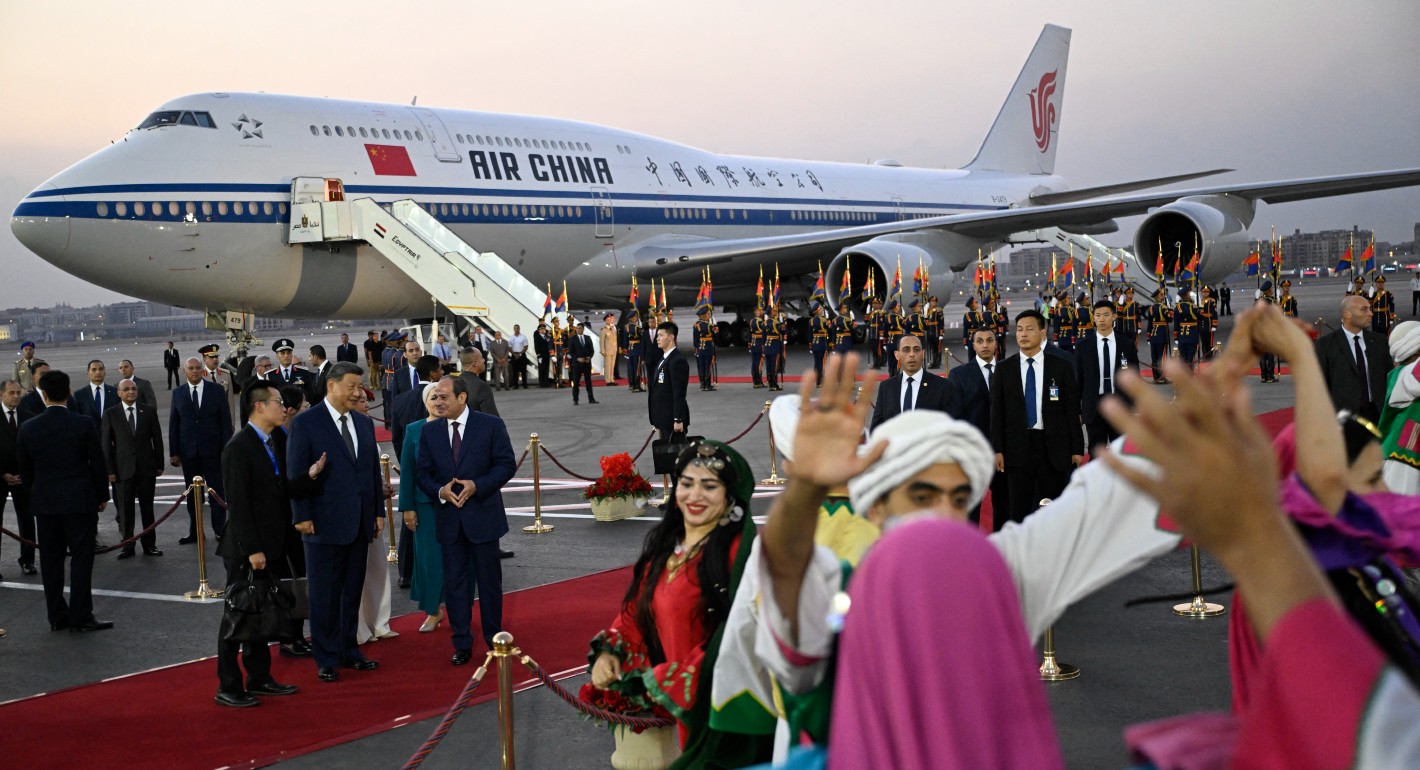
Amid celebrations of bilateral ties was a deeper focus on stability in the Middle East.
Amr Hamzawy
Xi, Putin, and other regional leaders are back-slapping in Bishkek, but the SCO has yet to answer the most serious questions about continental Asia's economic future.
Evan A. Feigenbaum
The conflict has sent economic and political shock waves through a country with no representation at the negotiating table—and Kenya is not alone.
Georgia Schaefer-Brown, Jane Munga
China’s banking crisis in the 2000s was resolved by transferring the costs to households through financial repression—a decision that recapitalized the banks while exacerbating the structural imbalances that continue to shape the Chinese economy today.

Michael Pettis
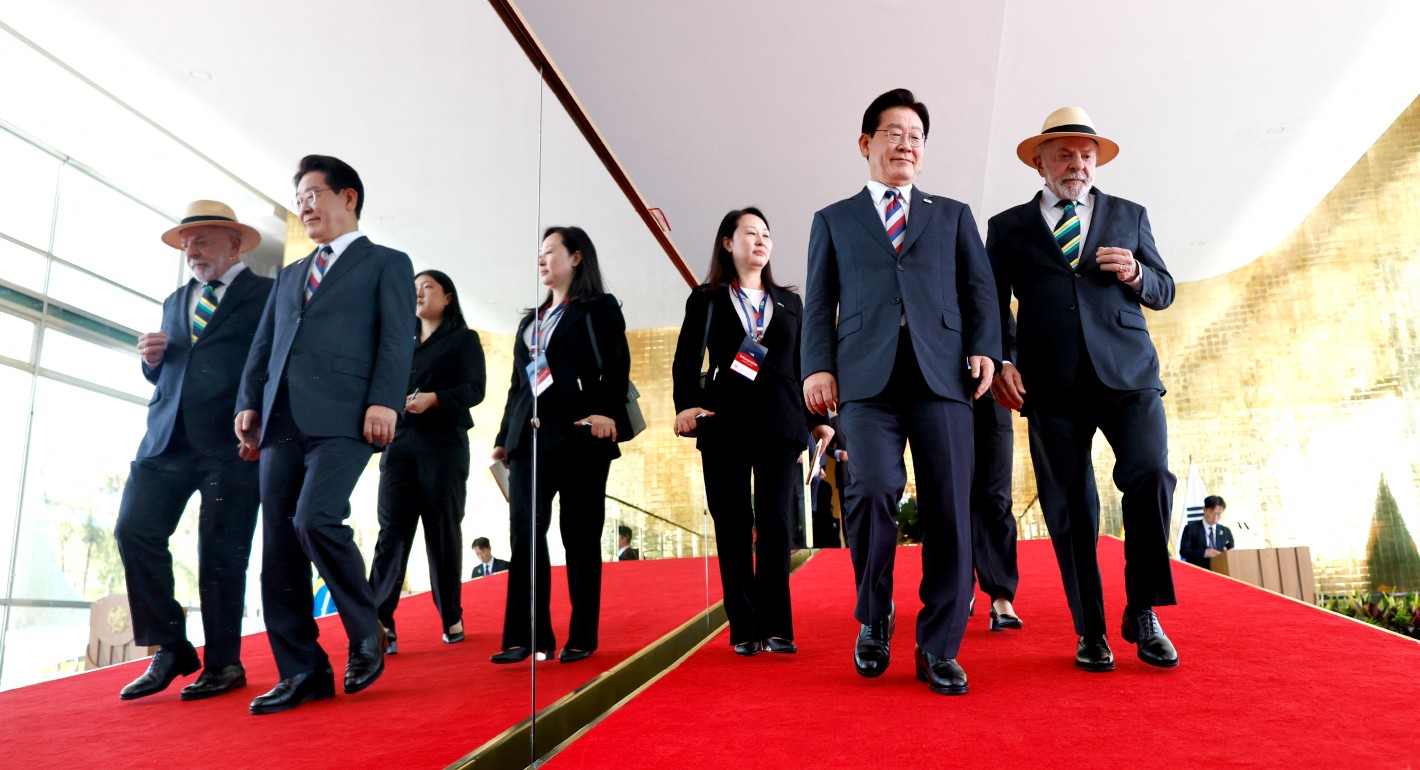
Lee’s tour shows how Seoul is reorganizing its diplomacy away from Pyongyang and toward industrial networks and the geography of the compute economy.
Darcie Draudt-Véjares