

Q&A
- +1
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
{
  "authors": [
    "Yukon Huang"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie China",
    "Carnegie Russia Eurasia Center"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie China",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China"
  ],
  "topics": [
    "Economy"
  ]
}
Source: Getty
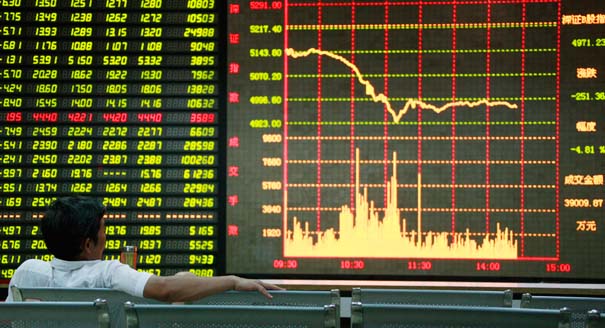
Beijing’s efforts to liberalize its financial markets have become much more complicated and increased volatility has been the result.
Source: Wall Street Journal
Global financial markets have been rattled by the extreme volatility in China’s equity markets and by pressures for the yuan to depreciate more than just a few percentage points. Some observers interpret the turbulence as evidence of a possible economic collapse with global repercussions. Others believe Beijing intends to use currency depreciation to buoy up exports, potentially triggering rounds of competitive devaluations. Both perceptions are largely misguided.
China’s current stock-market gyrations are unrelated to the state of its real economy, which is in little danger of collapsing, though the slowdown will persist. Nor will such a modest depreciation significantly impact trade balances when other Asian currencies have experienced much sharper declines. Then why have these largely China-specific events shaken global markets?Some see the turbulence as an overreaction. But this can’t be the full story given a similar round of swings last summer. Others see more fundamental problems involving Beijing’s unwillingness to allow market forces to guide its economy. Yet China’s strong past performance was due to its receptivity to market-based reforms. China is in fact coming closer to being a more “normal,” market-driven economy. Like other market economies, it is less able to manipulate prices and economic aggregates. This, coupled with globalization, makes China vulnerable to economic cycles.
Meanwhile, its current problems stem from being neither a true market economy nor completely state-controlled. Hence the uncertainty.
China’s slowdown will be protracted because it involves a longer-term structural shift to more service-driven growth and a shorter-term cyclical adjustment to balance the overbuilt property market. The hope is that this process will be smooth, but underlying pressures shaping these trends suggest that volatility should be expected.
Beijing’s actions have complicated matters. Its eagerness to internationalize the yuan before the requisite institutions could be put in place has accentuated risks and limited options. When the International Monetary Fund approved the inclusion of the yuan in the special drawing rights basket of reserve currencies, it didn’t do China any favors by interpreting the eligibility rules so liberally. One of the two technical conditions for inclusion is that the currency be “freely available,” which generally means that currency transfers aren’t restricted by capital controls. This clearly isn’t the case in China.
Chinese firms and households are eager to move funds abroad as the country transforms from a state-planned economy reliant on capital controls into a more market-based economy where investors can diversify their holdings abroad. As long as there is pressure for the yuan to depreciate, a freely available currency will be nearly impossible.
In the past, this pressure was largely contained because returns were much higher in China than abroad. Property prices were soaring, and persistent trade surpluses pushed the value of the yuan upward.
But with the slowing economy, declining property prices and narrowing interest-rate differentials, incentives for Chinese firms and households have reversed. Beijing’s efforts to liberalize its financial markets are now much more complicated. The result is increased volatility.
Volatility is also heightened on China’s equity markets because of government interventions. The Shanghai Stock Exchange continues to be dominated by state-owned firms even as the economy has become driven by the private sector.
Meanwhile, movements in the exchange are shaped more by unsophisticated investors with a gambler’s mentality than by economic fundamentals. And by intervening after this summer’s collapse with state purchases and bans on large-scale selling, the government has artificially propped up prices, almost guaranteeing that there will be major periodic sell-offs.
Some volatility is always to be expected, but trying to reverse the direction of market-driven shifts only leads to more extreme adjustments in the future. Beijing would be better off letting the equity market find its own equilibrium while strengthening its regulatory and institutional foundations so that eventually these fluctuations will be driven by economic fundamentals.
Dealing with volatility in the exchange-rate market is more complicated. China is moving away from a peg to the U.S. dollar and toward a more flexible system linking the yuan to a basket of currencies. If successful, the yuan would be stabilized relative to this basket but allowed to fluctuate more widely relative to the dollar. This is a sensible way to transition to a free-floating exchange-rate system that isn’t possible at China’s current stage of financial development.
In the interim, Beijing is trying to create a mechanism to link the yuan to this currency basket and determine its appropriate value. The market is signaling that this will require depreciation, but the big question is by how much. If it’s modest, a process of gradual adjustments might work. But if the gap is large, then more actions like the ones we saw recently to counteract market pressures for depreciation are unlikely to be sustainable.
This article was originally published in the Wall Street Journal.
Senior Fellow, Asia Program
Huang is a senior fellow in the Carnegie Asia Program where his research focuses on China’s economy and its regional and global impact.
Recent Work
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
Yukon Huang, Isaac B. Kardon, Matt Sheehan
The real test may come after the leaders leave the room.
Sheena Chestnut Greitens, Oriana Skylar Mastro, Yukon Huang, …
The nuclear relationship between China and the United States is increasingly shaped by widening perception gaps rather than deliberate strategic design.
Tong Zhao
A summer of escalation in the Black Sea has hurt Ukraine economically and is exacerbating world food security. A truce is needed—as is a broader reframing of Europe’s Ukraine strategy.
Thomas de Waal
Why governance of rapidly evolving technology will be distributed and complex.
Stewart Patrick, Scott Singer
It should address the shortcomings of previous crisis communication efforts and adapt to the demands of frontier AI.
Lucy Luo