

Commentary
For every ruble allocated to social policy, health, and education in 2027, double that amount is earmarked for the army, the police, and the security services.
Alexandra Prokopenko
Source: Getty
Large industrialized nations like the United States, Japan, and Germany have benefited from increasing global demand for relatively stable economies in which to invest.
Leaders of the G8 nations meeting in L'Aquila Italy acknowledged in a joint statement that there are signs the world economy is stabilizing, but cautioned that "significant risks remain."
Analysis from Carnegie's International Economic Bulletin supports this conclusion, finding that although the preconditions for economic recovery have begun to develop, it is still too early to say that a sustained global recovery is imminent.
The Bulletin explores how the impact of the crisis and the chance for recovery vary in regions around the world, with a particular focus on Africa, Central Asia, China, the Middle East, and Russia. It shows that although the United States is at the epicenter of the global economic crisis, it is one of the countries least affected by the financial fallout. Large industrialized nations like the United States, Japan, and Germany have benefited from increasing global demand for relatively stable economies in which to invest. Instead, it is several developing countries, notably those with vulnerable capital accounts and weak macroeconomic fundamentals, that are experiencing severe economic downturns disproportionate to their roles in the crisis.
| Rank | Country | Currency Depreciation(%) | Equity Market(%) | Bond Spreads(Bps) |
|---|---|---|---|---|
|
1
| Ukraine | -59.9 | -66 | 733 |
|
2
| Argentina | -21.4 | -58 | 735 |
|
3
| Hungary | -18.9 | -58 | 283 |
|
3
| Poland | -35.2 | -53 | 127 |
|
5
| Jamaica | -20.4 | -51 | 439 |
|
6
| Ghana | -28 | -35 | 448 |
|
7
| Russia | -22 | -44 | 144 |
|
8
| Kazakhstan | -26 | -34 | 167 |
|
9
| Bulgaria | -1.5 | -51 | 175 |
|
10
| Mexico | -22.6 | -35 | 73 |
| * The difference between a country's bond interest rate and the interest rate on the U.S. treasury bond. The higher the number, the less confidence there is that a country can repay its loan. | ||||
Both rankings were determined by comparing currency devaluations, equity market declines, and rising sovereign bond spreads because these measures tend to track developments in the real economy during times of economic crisis when financial strain handicaps consumption, investment, and in many cases government spending, which limits GDP and employment growth.
| Rank | Country | Currency Depreciation(%) | Equity Market(%) | Bond Spreads(Bps) |
|---|---|---|---|---|
|
1
| China | 0.3 | -11 | -31 |
|
2
| Japan | 9.2 | -17 | -5 |
|
3
| United States | 0 | -24 | 0 |
|
3
| South Africa | 1.5 | -20 | 39 |
|
5
| Peru | -0.4 | -15 | 42 |
|
6
| Philippines | -0.1 | -21 | 53 |
|
7
| Malaysia | -0.9 | -12 | 81 |
|
8
| Germany | -1.2 | -34 | 0 |
|
9
| Colombia | -3.4 | -10 | 63 |
|
10
| France | -1.2 | -34 | 11 |
| * The difference between a country's bond interest rate and the interest rate on the U.S. treasury bond. The higher the number, the less confidence there is that a country can repay its loan. | ||||
The economic crisis has shown that even when a crisis originates in industrialized countries, developing countries pay the highest price and underlines why developing countries have a crucial interest in the financial soundness of large economies like the United States. This helps explain why the G20, rather than the G8, is leading the effort to design a regime to govern international finance. Or that Brazil, Russia, India, and China (the BRICs) organized their first summit to discuss, among other things, the role of the dollar as its reserve currency.
Former Senior Associate, International Economics Program
Dadush was a senior associate at the Carnegie Endowment for International Peace. He focuses on trends in the global economy and is currently tracking developments in the eurozone crisis.
Lauren Falcão
Former Junior Fellow, Trade, Equity, and Development Program
Shimelse Ali
Carnegie does not take institutional positions on public policy issues; the views represented herein are those of the author(s) and do not necessarily reflect the views of Carnegie, its staff, or its trustees.
For every ruble allocated to social policy, health, and education in 2027, double that amount is earmarked for the army, the police, and the security services.
Alexandra Prokopenko
The European Commissioner for Trade is headed to China. But after President Xi’s bridge-building visit to Washington, can a more isolated EU overcome Beijing’s stranglehold on critical raw materials? Who will blink first?
Rym Momtaz, ed.
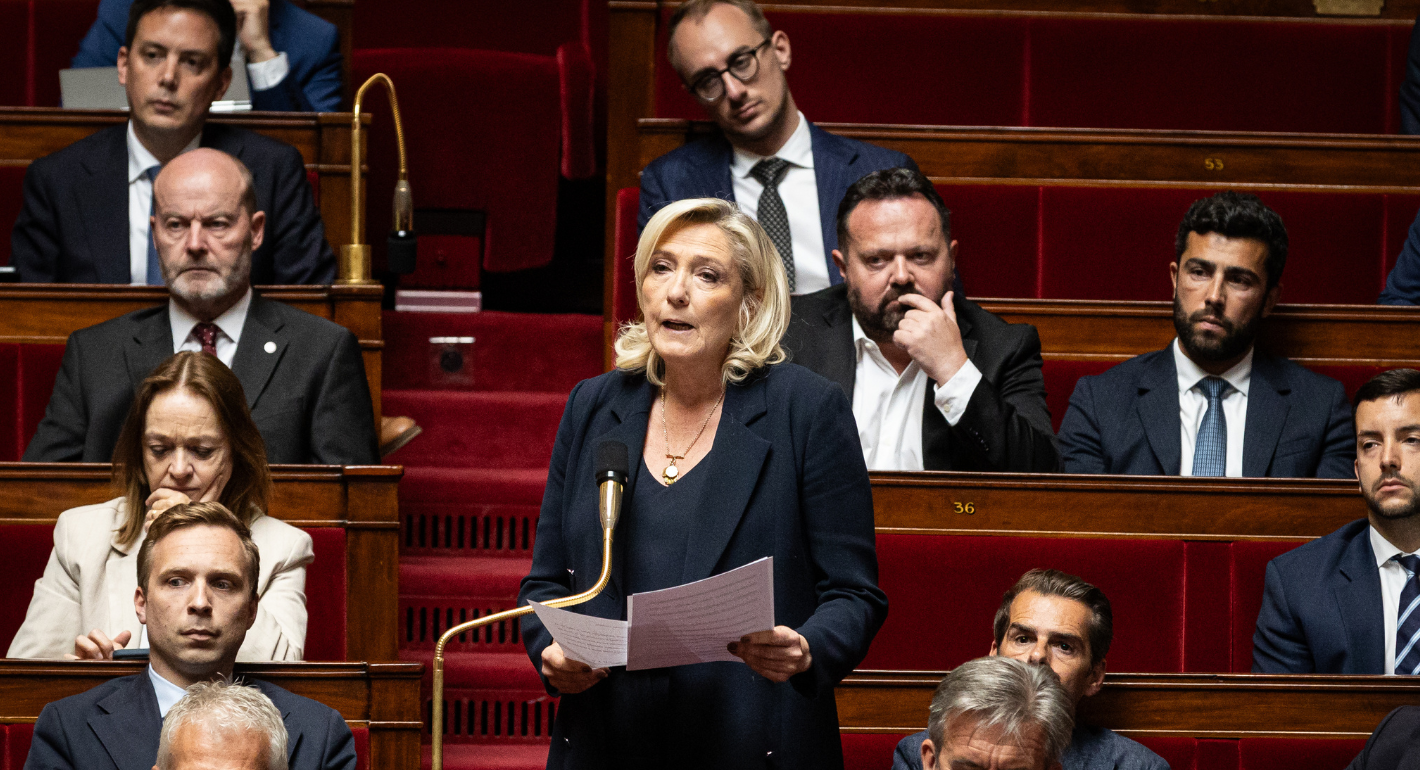
The domestic impacts of how long it is taking to end the war in Ukraine have pushed the French electorate to the political extremes and compromised the country’s diplomatic capacity.
Rym Momtaz
The Plaza Accord was not an externally imposed punishment of Japan but part of a broader restructuring that Japanese economists and policymakers themselves recognized was necessary. Its effects were undermined, however, when Tokyo responded to the resulting slowdown with policies that exacerbated investment, credit expansion, and the very imbalances the adjustment was intended to resolve.
Michael Pettis
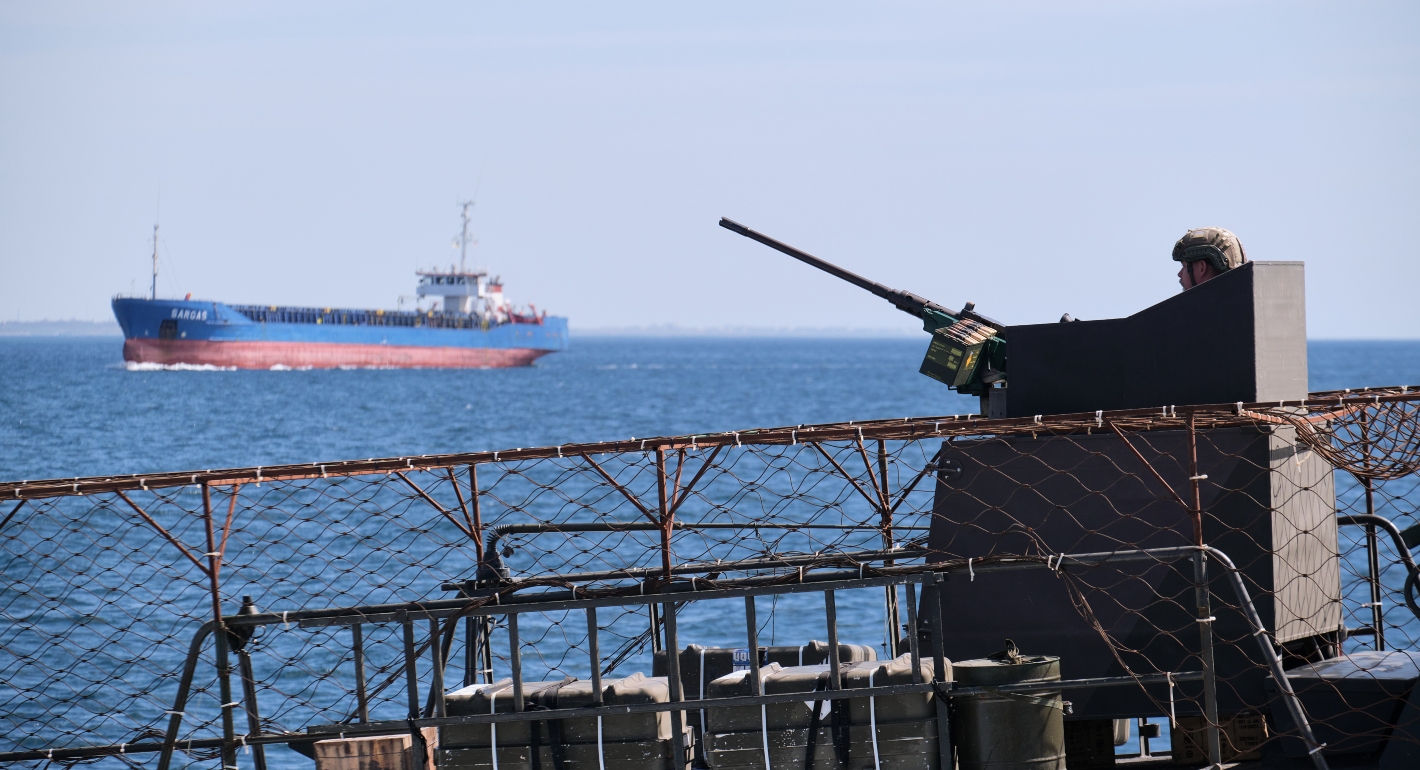
A summer of escalation in the Black Sea has hurt Ukraine economically and is exacerbating world food security. A truce is needed—as is a broader reframing of Europe’s Ukraine strategy.
Thomas de Waal