
Commentary
Michael Pettis
{
  "authors": [
    "Michael Pettis"
  ],
  "type": "legacyinthemedia",
  "centerAffiliationAll": "dc",
  "centers": [
    "Carnegie Endowment for International Peace"
  ],
  "collections": [],
  "englishNewsletterAll": "asia",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "AP",
  "programs": [
    "Asia"
  ],
  "projects": [],
  "regions": [
    "East Asia",
    "China",
    "Japan"
  ],
  "topics": [
    "Economy",
    "Trade"
  ]
}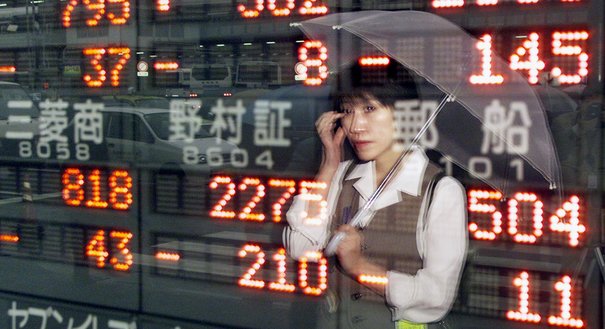
Source: Getty
Chinese policymakers looking to learn from Japan's policy missteps should recognize that Japan's lost decade grew out of its failure to implement early and gradual economic adjustment policies, not its decision to reevaluate the yen.
Source: South China Morning Post

After five years of strong growth and surging stock and real estate markets, in 1990 Japan was forced into a painful 20-year adjustment.
For many Chinese, there was a causal connection between the two events. The post-1985 rise in the yen, they believe, caused the bubble whose subsequent collapse ended Japanese growth and threw the country into a lost decade.
This view is mistaken. What is worse, to the extent that it affects Chinese policy it almost certainly increases the chances that China will suffer its own lost decade.
It was not the post-1985 rise of the yen that caused Japan's lost decade. Tokyo had waited so long before the inevitable currency adjustment that policymakers were then forced to choose between a sharp slowdown and a disastrous policy response. They chose the latter.
For Japan in the mid-1980s, a sharply undervalued currency and extremely low interest rates had helped to generate tremendous growth in the previous 15 years. But as in China today, this growth came with low and declining household consumption as a share of GDP. This left Japan extraordinarily dependent on investment and on a large trade surplus to generate growth.
Once it became clear, however, that the rest of the world, especially the United States, was unable to absorb Japan's rising trade surpluses, in 1985 under threat of trade sanctions Tokyo allowed the yen to soar in value against the dollar.
This should have caused Japan's trade surplus to fall sharply, and with it Japanese growth should also have dropped sharply.
But in an attempt to forestall the drop, Tokyo turned to the only set of policies that might reverse the impact of the devaluation. It reduced interest rates and forced banks to expand credit dramatically.
But Tokyo overdid it. The net result was the economy and asset markets soared. This in no way resolved Japan's underlying imbalances. In fact, it made them worse than ever.
Investment always causes growth, but misallocated investment always subtracts more growth from the future than it causes in the present. Japan's economy grew ferociously for five years, to the astonishment and admiration of the rest of the world, but at the cost of sharply worsening imbalances and massively wasted investment.
Finally in 1990, worried about rising risks, Tokyo finally did what it should have done years earlier. It began to raise the cost of capital in an attempt to choke off the out-of-control investment spree.
It was too late. Years of wasted investment had to be paid for, and they were paid for by a suffering household sector. Japan rebalanced the only way it could, with an even sharper contraction in economic growth.
The lesson of the 1980s is not that Japan should have resisted US demands to appreciate. It had no choice. Trade surplus countries have no bargaining power in a trade war.
Instead, the lesson is first, that Japan should have begun the rebalancing process much earlier, and second, that once the yen was forced to appreciate, it should not have responded by lowering interest rates and forcing investment to surge. This is the real lesson for China, although it will be a tough one to learn.
Nonresident Senior Fellow, Carnegie China
Michael Pettis is a nonresident senior fellow at the Carnegie Endowment for International Peace. An expert on China’s economy, Pettis is professor of finance at Peking University’s Guanghua School of Management, where he specializes in Chinese financial markets.
Recent Work
Michael Pettis
Michael Pettis
Rubio’s recent visit brought welcome attention, but more capital requires governance changes that may be a hard sell for regional governments.
Jennifer B. Murtazashvili
Japan’s long-term security policy is driven by concerns about China, and there is little appetite for (or interest in) pursuing a confrontation with Moscow.
James D.J. Brown
China has showcased its engineering prowess with small modular reactor demonstration projects. But turning these technological achievements into commercial success will be a greater challenge.
Tong Zhao
Despite public disputes over trade and immigration, the strategic partnership’s foundations remain sturdy.
Sameer Lalwani
With its public finances in shambles, the far right polling at 35 percent ahead of the 2027 presidential election, and a growing protest movement, is France’s crisis a threat to the EU’s geopolitical awakening?
Rym Momtaz, ed.