

Commentary
Alexander Gabuev
{
  "authors": [
    "Alexander Gabuev"
  ],
  "type": "commentary",
  "centerAffiliationAll": "",
  "centers": [
    "Carnegie Endowment for International Peace",
    "Carnegie Russia Eurasia Center"
  ],
  "collections": [],
  "englishNewsletterAll": "",
  "nonEnglishNewsletterAll": "",
  "primaryCenter": "Carnegie Endowment for International Peace",
  "programAffiliation": "",
  "programs": [],
  "projects": [],
  "regions": [
    "East Asia",
    "China",
    "Russia"
  ],
  "topics": [
    "Economy",
    "Trade",
    "Foreign Policy"
  ]
}
Source: Getty
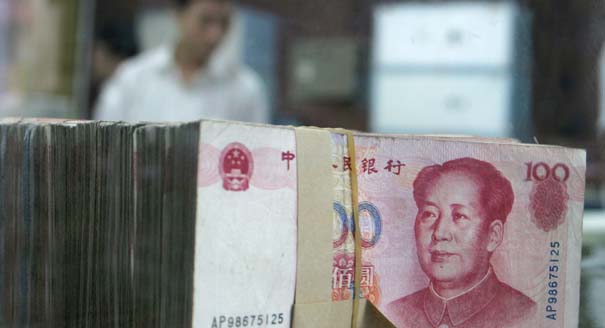
As new rounds of Western sanctions seem more likely, some large Russian companies are moving their cash reserves away from Western banks and currencies. In the long run dependence on China’s money and its financial institutions may be a new reality for Russian leaders for decades.
As new rounds of Western sanctions seem more likely, some large Russian companies are moving their cash reserves away from Western banks and currencies. Russia’s second largest mobile phone operator Megafon has announced that it had converted 40 percent of its cash holdings from U.S. dollars and Euros into Hong Kong dollars. Foreign cash reserves of Megafon (about 400 millions euros) will be held in Chinese bank accounts in Hong Kong, with the remaining 60 percent being held in roubles in Russian banks. Companies which follow suit include world’s largest nickel producer Norilsk Nickel and Novatek, Russia’s largest natural gas producer after Gazprom. Hong Kong dollars seem to be a reasonable alternative for them. Hong Kong dollar is pegged to the U.S. dollar and hence predictable; financial authorities of the city proved to be capable even during Asian financial crisis in 1998.
But it’s more than just a group of Russian oligarchs and CEOs of large state-owned companies trying to hedge their risks of being completely shut out of U.S. dollar and Euro funding markets or their accounts in Western banks being frozen. The current trend may have much broader implications for the Russian economy.
For about two decades, Russian companies (both state-owned and private) used Western markets to get access to cheap and reliable financing. The U.S. dollar was the currency of choice for the majority of transactions (including some domestic). London became a favorite destination for Russian IPOs and also key center for managing the huge wealth of the Russian elite.
Against this background early attempts of Beijing to promote the yuan (RMB) and Chinese financial centers in Russia were not very successful. Only after the global crisis of 2008-2009 did Russian companies start to explore new opportunities. New York and London were struggling with the consequences of the credit crunch and margin calls of some Russian borrowers. At the same time in 2009 Hong Kong became a top global IPO fundraising center (the city has kept this position for two more years), and in 2010 Rusal, the world’s largest aluminium producer, was the first Russian company to sell its shares in Hong Kong (the company is registered in Jersey). In October 2009 Chinese Development Bank lent a Russian oil-company Rosneft and oil-pipeline monopoly Transneft an unprecedented 25 billion dollars in exchange for oil supplies to China. A year later Moscow and Beijing signed an agreement to promote trade in national currencies. And in December 2010 Moscow Stock Exchange and Chinese CEFTS launched direct trade of the yuan and rouble.
Initially these experiments were small. In 2012 daily trade volume of the RUR/CNY currency pair in Moscow was less than 1 million dollars. Less than 1 percent of bilateral trade was settled in roubles or RMB. Rusal’s successful IPO was an exception: none of the large Russian companies followed suit and even Rusal’s majority shareholder Oleg Deripaska didn’t succeed in listing his holding company En+ there. But for Beijing even these small-scale experiments were of great value: Chinese authorities used Russia as a testing ground in their ambition to turn RMB into a fully convertible global currency somewhere around 2020. This year China signed deals with London, Singapore and Frankfurt to make these cities new centers for RMB financing and clearing in addition to its own offshore center in Hong Kong.
Western sanctions against Russia will help China to increase the scale of this experiment. In October Chinese and Russian Central Banks plan to sign a currency-swap deal which will give business operators bigger access to roubles and RMB liquidity. Chinese UnionPay system is expanding in dramatic pace as VISA and MasterCard may leave the market. Russia’s 6th richest man Gennady Timchenko (on EU and US sanctions lists) abandoned his MasterCard and VISA to become customer of UnionPay. Some Russian corporations (like state-owned Joint Shipbuilding Company) are planning to move their cash reserves into RMB. Although, emotional and political, these decisions have economic background as well. Companies can save up to 5 percent on conversion omitting U.S. dollars. China has been Russia’s largest trading partner for the last 4 years (trade exceeded 89 billions dollars in 2013) with the majority of Russian exports to China being commodities, and the majority of imports—machinery and manufactured goods. Russian oil and gas companies are talking to their Chinese colleagues about the possibility of selling at least part of their Russian oil for Chinese yuan, not U.S. dollars—they can use RMB to buy drilling equipment made in China. With Western companies limiting their technological exports to Russia (due to sanctions and their own risk calculations) their market niche is being taken by Chinese competitors, which come with cheap RMB-denominated loans.
This process will be slow. Russia needs to address some challenges, like lack of expertise (talents who both speak fluent Mandarin and have financial degrees are in short supply in Russia) or the careful approach of Chinese investors towards Russian risks. But in the long run as Russia and the West are slipping into a new cold war, dependence on China’s money and its financial institutions may be a new reality for Russian leaders for decades.
Alexander Gabuev is deputy editor-in-chief of Kommersant Vlast.
Director, Carnegie Russia Eurasia Center
Alexander Gabuev is director of the Carnegie Russia Eurasia Center. Gabuev’s research is focused on Russian foreign policy with particular focus on the impact of the war in Ukraine and the Sino-Russia relationship. Since joining Carnegie in 2015, Gabuev has contributed commentary and analysis to a wide range of publications, including the Financial Times, the New York Times, the Wall Street Journal, and the Economist.
Recent Work
Alexander Gabuev
Alexander Gabuev
European Commission President Ursula von der Leyen is about to give her annual address on the state of the EU. Here’s what she won’t—but should—say.
Rym Momtaz
Depleted financial reserves and a shrinking tax base mean it is no longer possible to simultaneously deliver high defense spending, price stability, and economic growth.
Alexandra Prokopenko
Huawei pushed hard to enter the Egyptian data centers market, until the Americans made a better offer.
Angie Omar

The books, podcasts, and films that explain the world it made.
Andrew Leber
Blurring the line between humans and animals is a long-standing tradition in social utopian prose. In his latest novel, Leonid Bershidsky reminds us that in social experiments, people are often treated no differently than animals.
Alexander Baunov